Looking for a Swap Pricer?
Check out our tutorial on how to use our Interest Rate Swap Calculator.

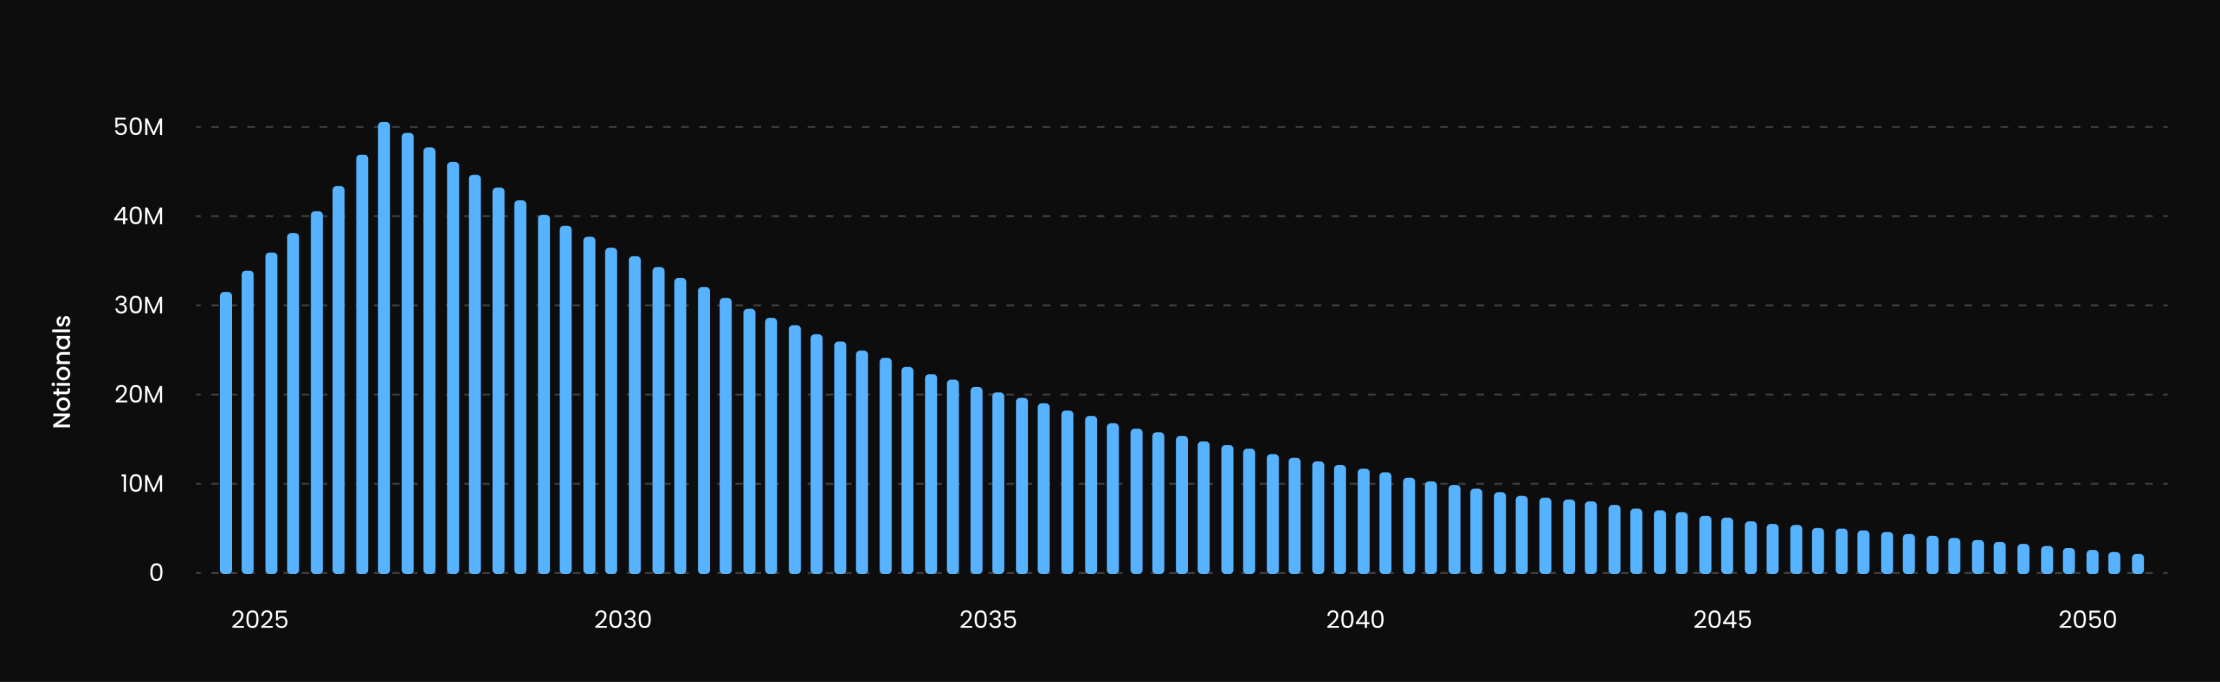
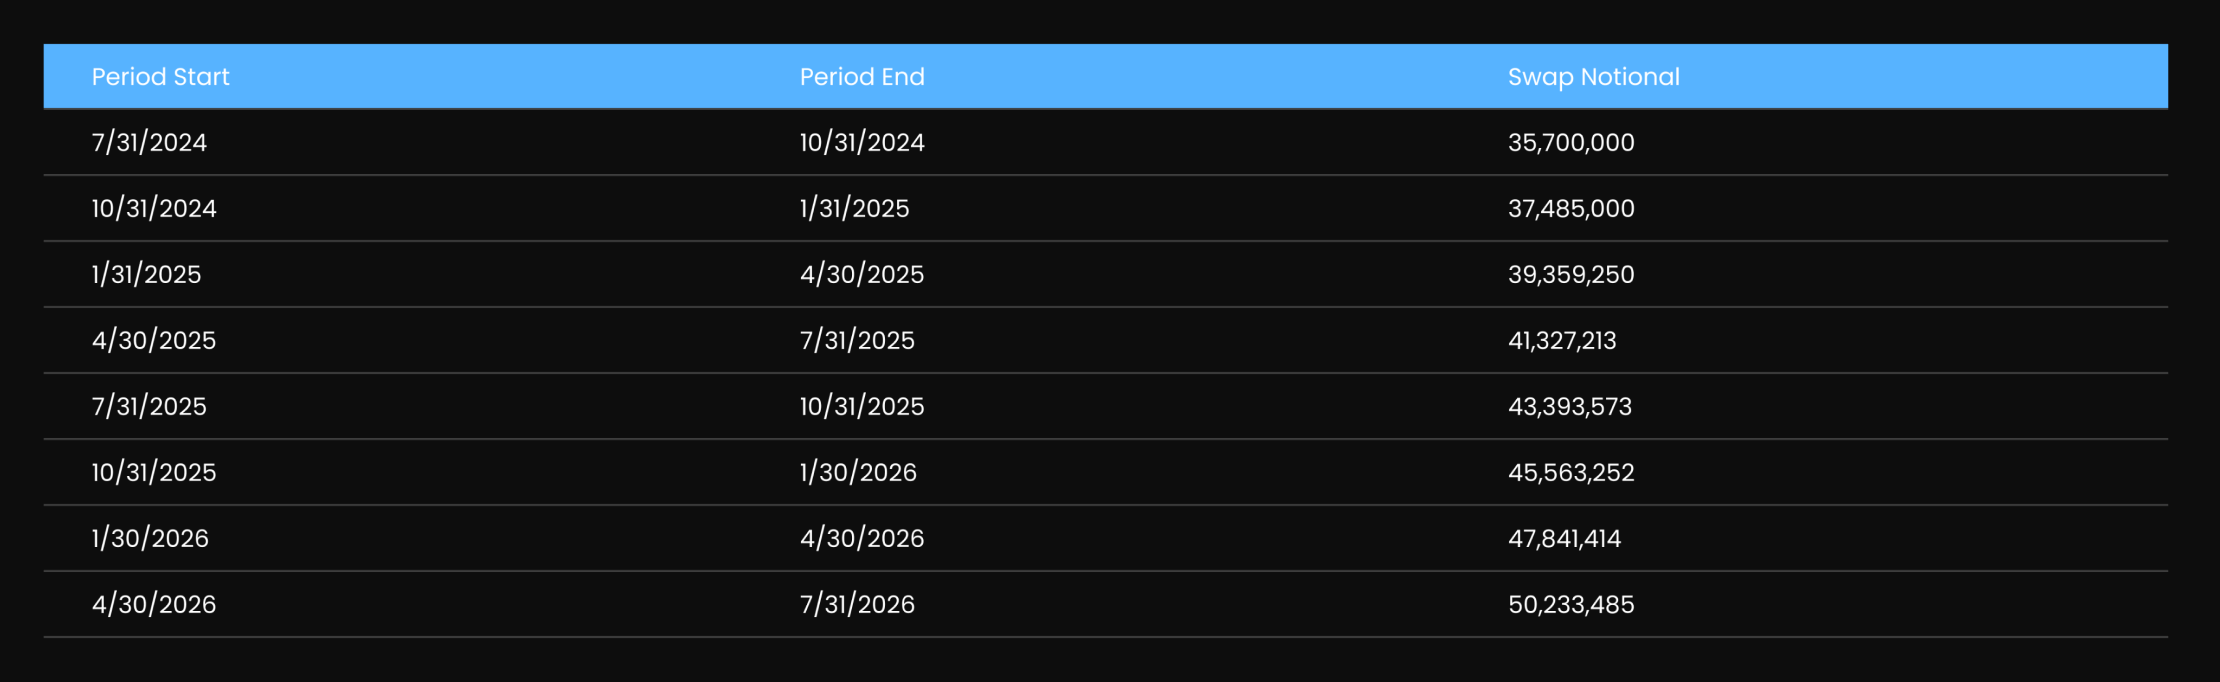
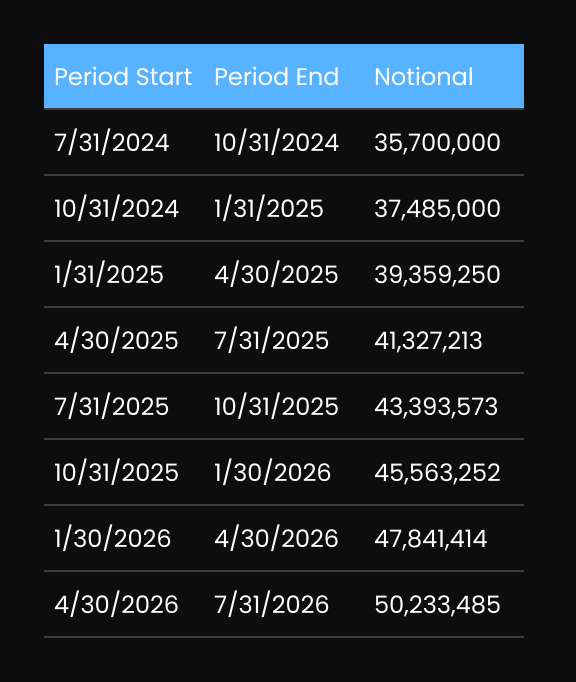
Accurately price interest rate swaps for complex debt structures.
Model various debt scenarios with multiple swap schedules.
Store and manage multiple Interest Rate Swaps.
Calculate swap rates for 30+ currencies including EURIBOR, SOFR, and SONIA.
Access live market data, refreshed about every 30 seconds for major benchmarks.
Share projects across the team for better collaboration
trusted by





FAQs
Within a basis point of bank mids on the curves customers test. The bank's quote adds its margin, including any credit charge, on top of the mid, so the gap you see is what you are paying for execution.
Yes. Enter the notional schedule your debt uses, whether amortising, sculpted or stepped, and the pricer returns the fair rate at mid for that exact profile.
The fair rate, the swap's value on today's curve, its sensitivity to a one basis point move, and the full cashflow schedule, so you can check each payment the bank's term sheet implies.
30+ currencies, including SOFR, SONIA, €STR and EURIBOR. Each index carries its market conventions for day counts, payment frequency and calendars, so a quote is priced the way the bank prices it.
Most major benchmarks refresh about every 30 seconds in market hours. Every price carries its timestamp, so you can show exactly which curve a number came from.
See it in practice
Real tasks this feature was built for, from the use-case library.
"The bank just sent a swap quote. Is it fair?"
Upload your exact amortising notional profile and get the live mid swap rate from the same interbank market the banks use. The gap to the quote is the bank's margin.
See how →"We're refinancing. What's the breakage on the existing swap?"
Load the existing swap to see its live mark-to-market and how breakage evolves over time, so you can negotiate the exit or time the refinancing yourself.
See how →"I need the expected IRR on a new debt deal before it goes to committee"
Project floating-rate coupons off the live forward curve, price the hedge on the actual amortising profile, and archive the as-of-date curve behind the committee paper.
See how →