My client asked: should we cap or swap?
Price both yourself, on the same structure, at the same moment. Read the cap premium across tenors and out-of-the-money strikes, put the live swap rate beside it, and show the committee what each costs if rates fall, hold or rise. Executable quotes come later, if the client trades.
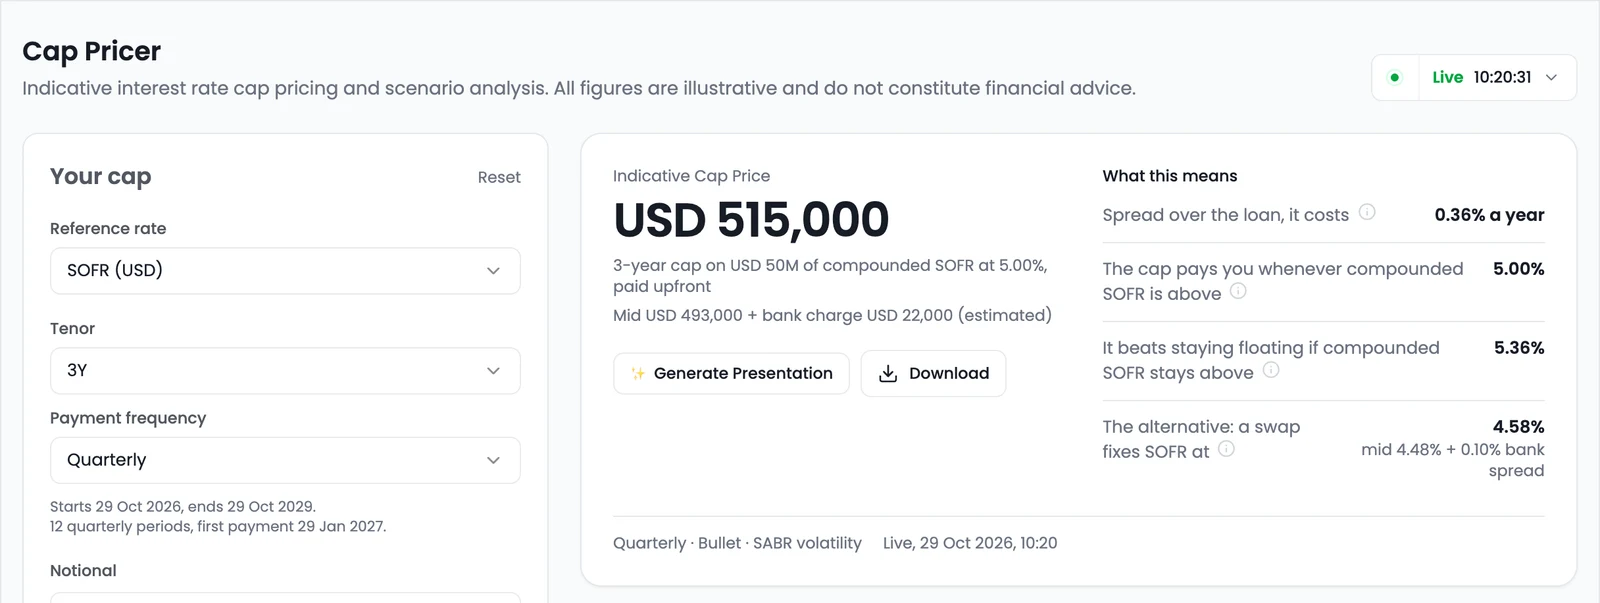
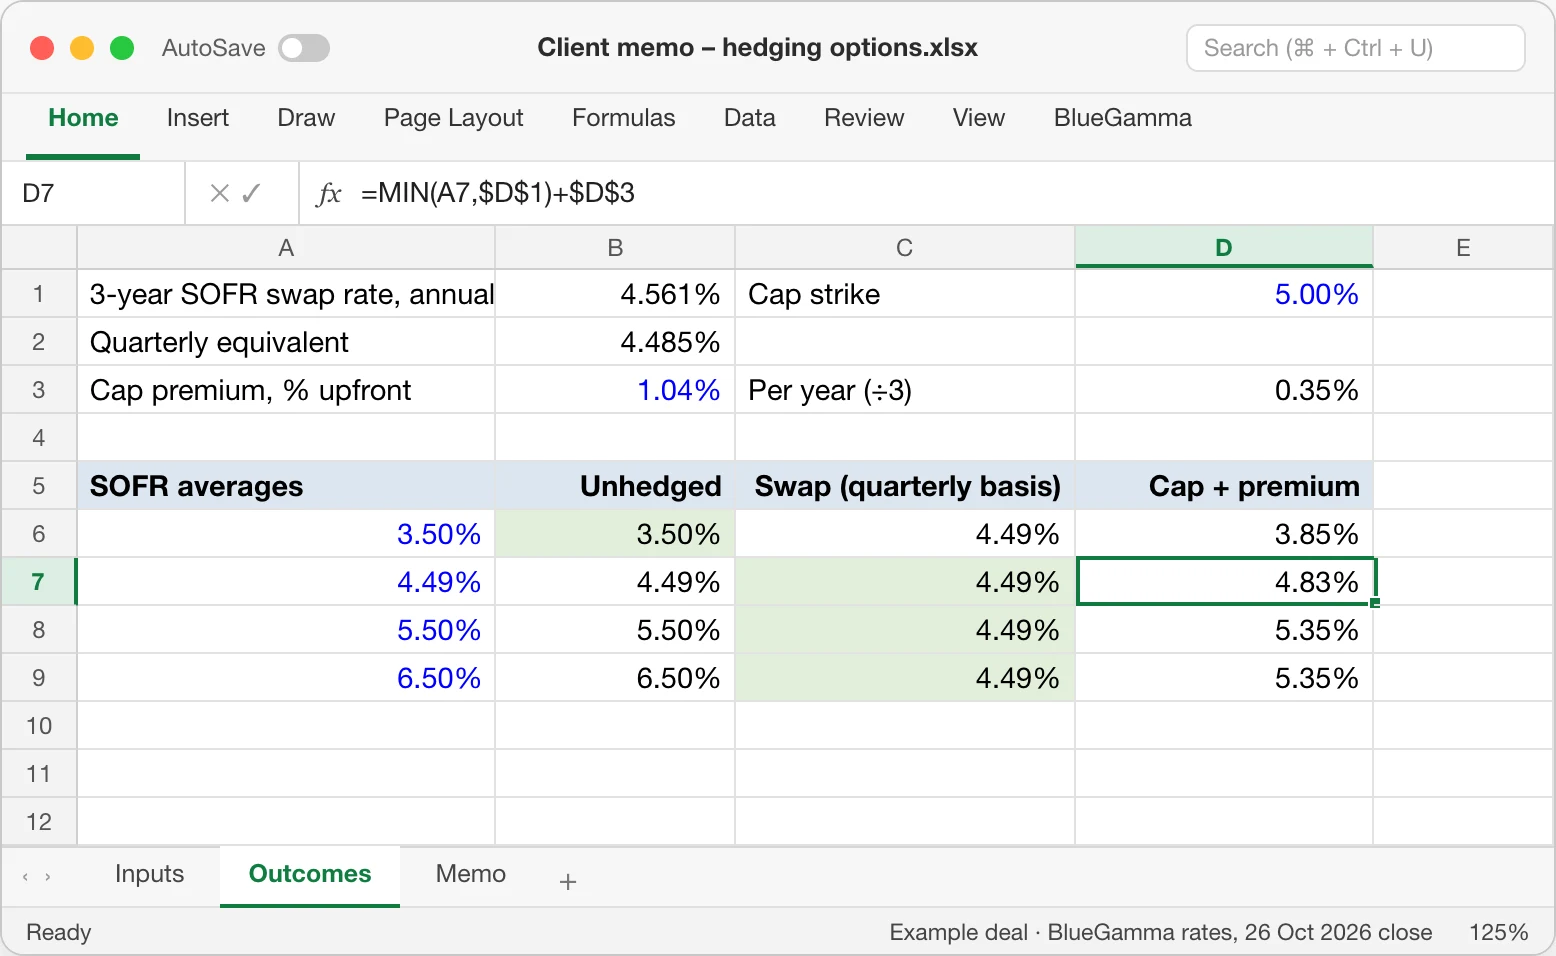
- $520kupfront for a 3-year 5.0% SOFR cap on $50m, 26 Oct close
- 4.561%3-year SOFR swap rate, the alternative, 26 Oct close
- 35bpa year: the 5.0% cap premium spread over its 3 years
- 1.04%of notional at a 5.0% strike, against 3.25% at 3.5%
Today, and with BlueGamma
How it usually gets done
- Asking a relationship bank for an indicative quote on a trade it won't win.
- Quoting an at-the-money cap against the swap rate, which nobody buys.
- Cap prices and swap rates from two sources on two different days.
With BlueGamma
- A premium grid by tenor and strike, GBP, EUR and USD included.
- The live swap rate on the same notional profile, on the same screen.
- Outcomes under falling, flat and rising rates, ready for the memo.
Not the right fit if you need an executable cap price today. That still comes from the bank; BlueGamma tells you whether it is fair.
How it works
- 01
Set up the cap the client would actually buy
Pick the index (SONIA, EURIBOR, SOFR and more), term and notional. Amortising? Paste the schedule from your model.
Read the premium across strikes 0.25% and 0.50% above the money: how much cheaper protection gets per step of headroom.
bluegamma.io/calculators/interest-rate-cap-calculator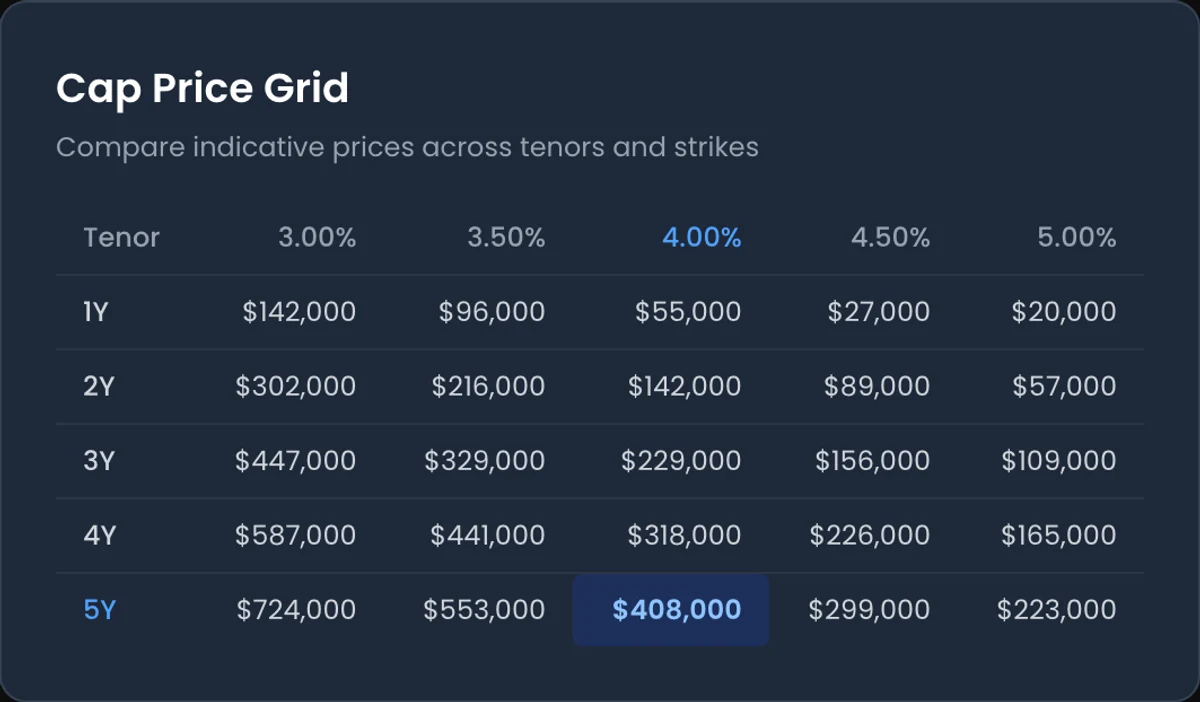
- 02
Put the swap rate next to it
Price the mid swap rate on the same structure: same start, same payment dates, same amortisation. Both refresh every 30 seconds, so the memo uses one market moment.
app.bluegamma.io/cap-pricer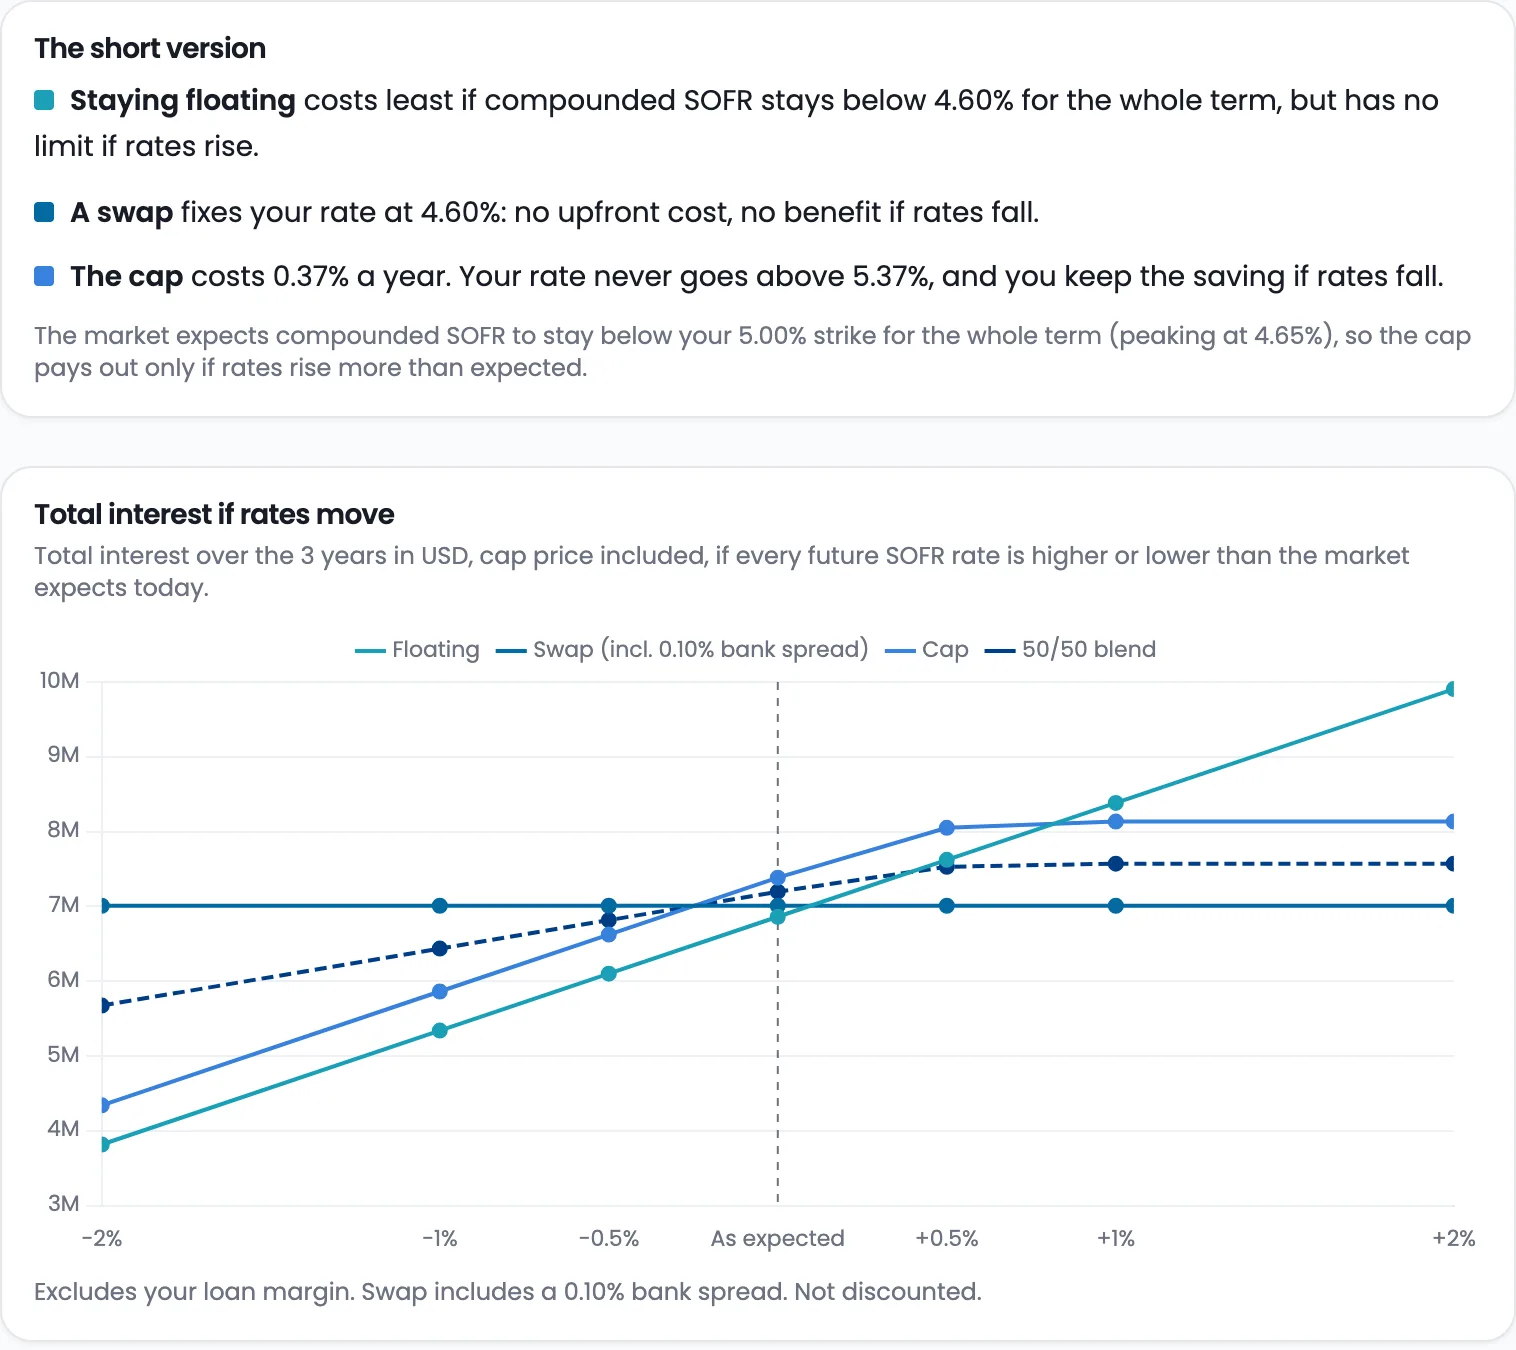
- 03
Show what each costs under a few rate paths
The committee isn’t choosing a product; it’s choosing which outcomes it can live with. Put the unhedged, swapped and capped cost side by side for falling, flat and rising rates.
Check the facility first: a loan floor, an early sale or a lender’s requirement can settle it before the numbers do.
$50m of SOFR debt, three years
In their words
“That's almost always a feature of the quotes that we need to raise, a variety of strike rates. So they can evaluate which makes the most sense. It's a useful matrix for sure.”
“We might know they're gonna go with the swap, in which case we may not necessarily want to reach out to our relationship contacts knowing full well they're not gonna get any business from us.”
“There is a floor of, I think it's gonna be 1% on EURIBOR on our private credit facility. And they're just suggesting that we might be better off looking at interest rate caps rather than swaps.”
Where else the cap price would come from
A bank only prices the strikes you ask for, and building a model takes months. BlueGamma shows every strike next to the swap rate in minutes.
| Criterion | BlueGamma | Indicative quote from a bank | Terminal | Building your own model |
|---|---|---|---|---|
| Which currencies can you price caps in? | 30+ currencies | Whatever the desk will quote | Most major currencies | Only those you buy volatility data for |
| Can you see several strikes at once? | Yes, a full grid by tenor and strike | Only the strikes you ask for | No, one structure at a time | Once you have built it |
| Is the swap rate shown alongside? | Yes, on the same screen at the same moment | No, it's a separate request | No, you put it together yourself | Only if you build it |
| What does each quote cost? | Nothing extra, it's in the subscription | Goodwill, if no trade follows | Nothing extra | Nothing extra |
| How long does it take? | Minutes, refreshed every 30 seconds | Hours to days | Instant, if you have a seat | Months, plus a developer |
Questions teams ask
It depends on where the strike sits against the forward curve, the term, the notional profile and volatility on the day: the further above the forwards and the shorter the term, the cheaper. For reference, on 26 Oct 2026 a 3-year SOFR cap on $50m struck at 5.0% cost about $520k upfront, 1.04% of notional. BlueGamma prices your exact structure live, with the surrounding strikes and tenors in one grid.
A swap fixes the rate with no upfront premium, but it carries breakage if the loan repays early and gives up the benefit of falling rates. An out-of-the-money cap costs a premium upfront, limits the worst case and keeps the benefit of falling rates, with no breakage. Lender requirements and prepayment plans usually decide it.
Borrowers buy caps out of the money, commonly 0.25% or 0.50% above the at-the-money level, sometimes further out as pure disaster insurance. An at-the-money cap is rarely bought, so quoting one against the swap rate misrepresents both options.
Often, yes. If the facility floors EURIBOR at 1%, a vanilla swap leaves the borrower paying the floored rate on the loan while receiving the lower market rate on the swap once rates fall below the floor, so the hedge and the loan stop matching. That is why advisers often steer floored private-credit borrowers towards caps.
Advisers who see both sides put the flow at roughly 60/40 swaps to caps, split largely by sector. Real estate borrowers like caps because the premium can be capitalised into the financing and kept out of interest-cover calculations, and a cap has no breakage if the asset sells early. Corporates more often prefer the certainty of a swap.
Not to build the recommendation. Price the cap and the swap independently, put the scenarios to the committee, and involve a desk only once the client decides to trade. That protects goodwill with a bank you already know won't win the trade.
Related guides
Price the cap and the swap before the next committee memo
Cap pricer, live swap rates and amortising profiles, all in the trial.