We're refinancing. What's the breakage on the existing swap?
Breakage is the swap’s mark-to-market, and you can calculate it yourself. Load the existing swap, read the live mid MtM and its PV01, and the gap to the bank’s number is its unwind charge. Then price the exit you actually want: terminate, roll, blend or buy down.
- ~1bpfrom the bank's own mid on a matched trade
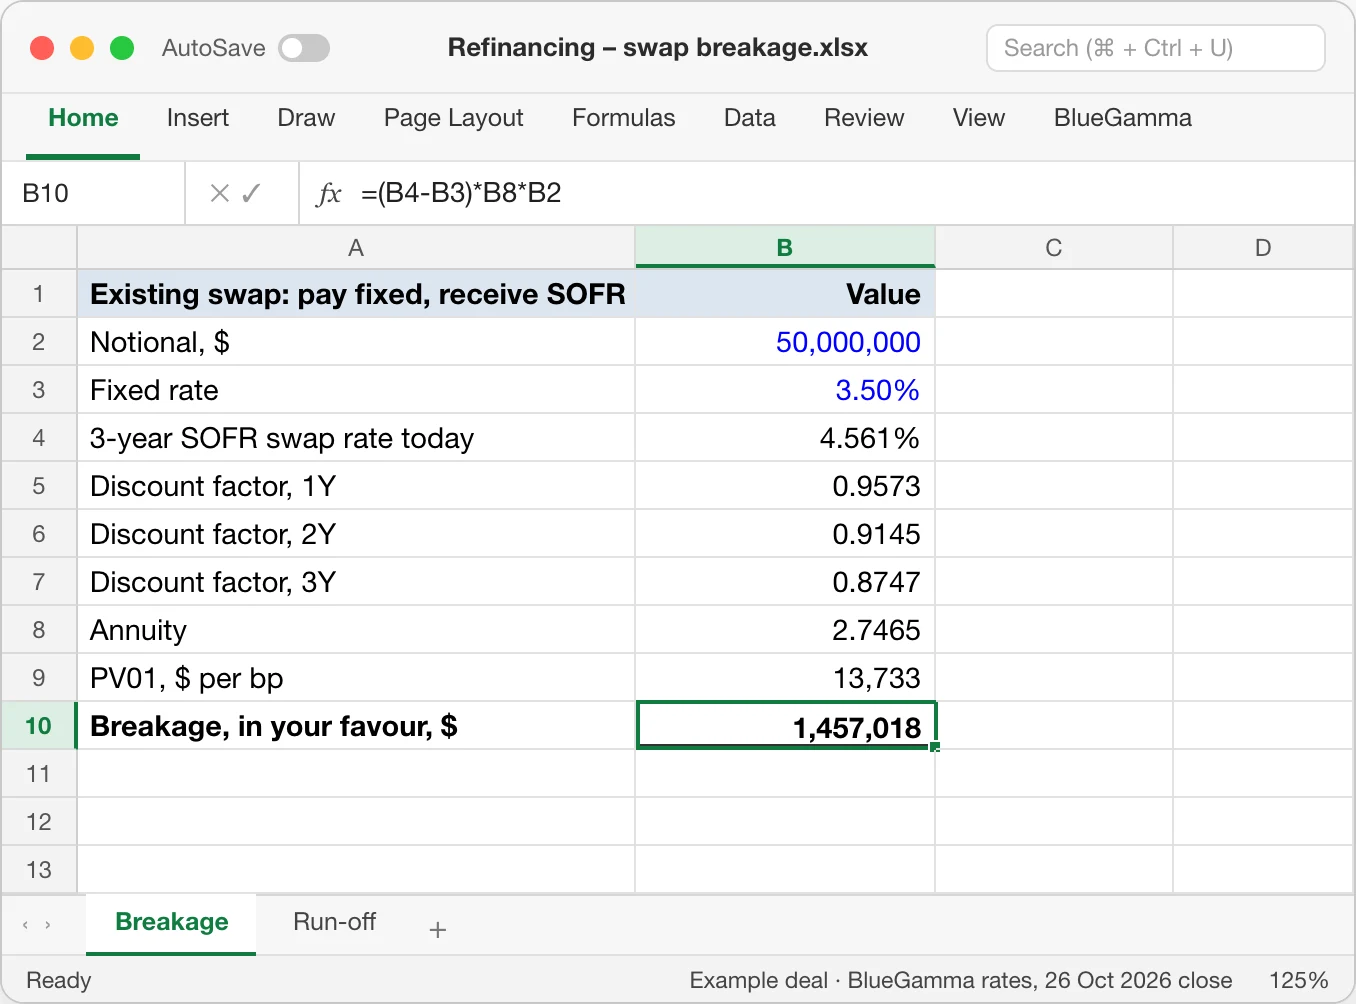
- $1.46mbreakage in your favour on the example $50m swap, 26 Oct close
- $13.7kper bp on $50m with 3 years left
- 30 secrefresh, so the weekly re-run takes minutes
Today, and with BlueGamma
How it usually gets done
- Asking the bank you're leaving what it costs to leave, and taking its number.
- A homemade Excel MtM that's stale before it's pasted.
- No way to price the restructure: blend-and-extend, top-ups or buy-downs.
With BlueGamma
- The live mid MtM on your exact profile, within about 1bp of the bank's mid.
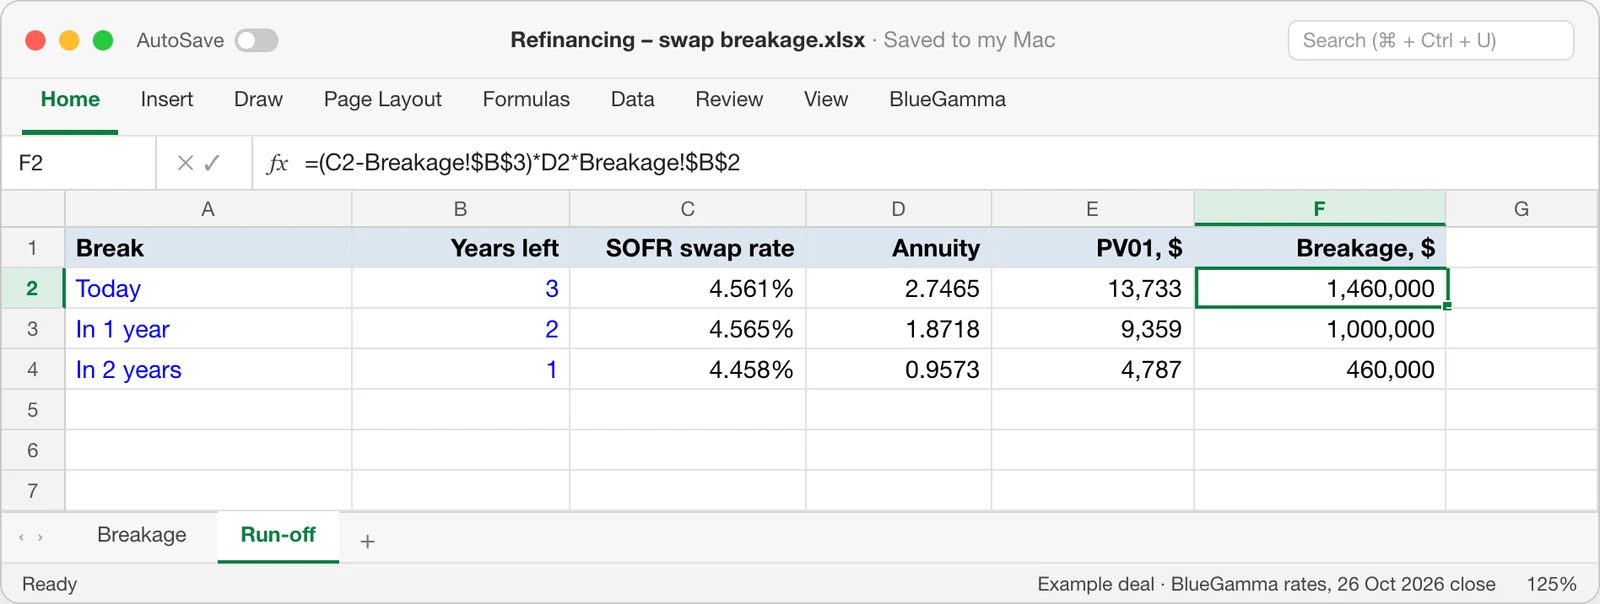
- A forecast of the breakage as each payment drops away.
- Terminate, roll, blend or buy down, priced off the same curve.
Not the right fit if the swap has months left and the bank's number is all you need.
How it works
- 01
Load the existing swap
Enter the trade once: start, payment dates, day count, fixed rate and the real notional profile. Amortising? Paste the outstanding balance schedule from your loan model.
bluegamma.io/calculators/interest-rate-swap-calculator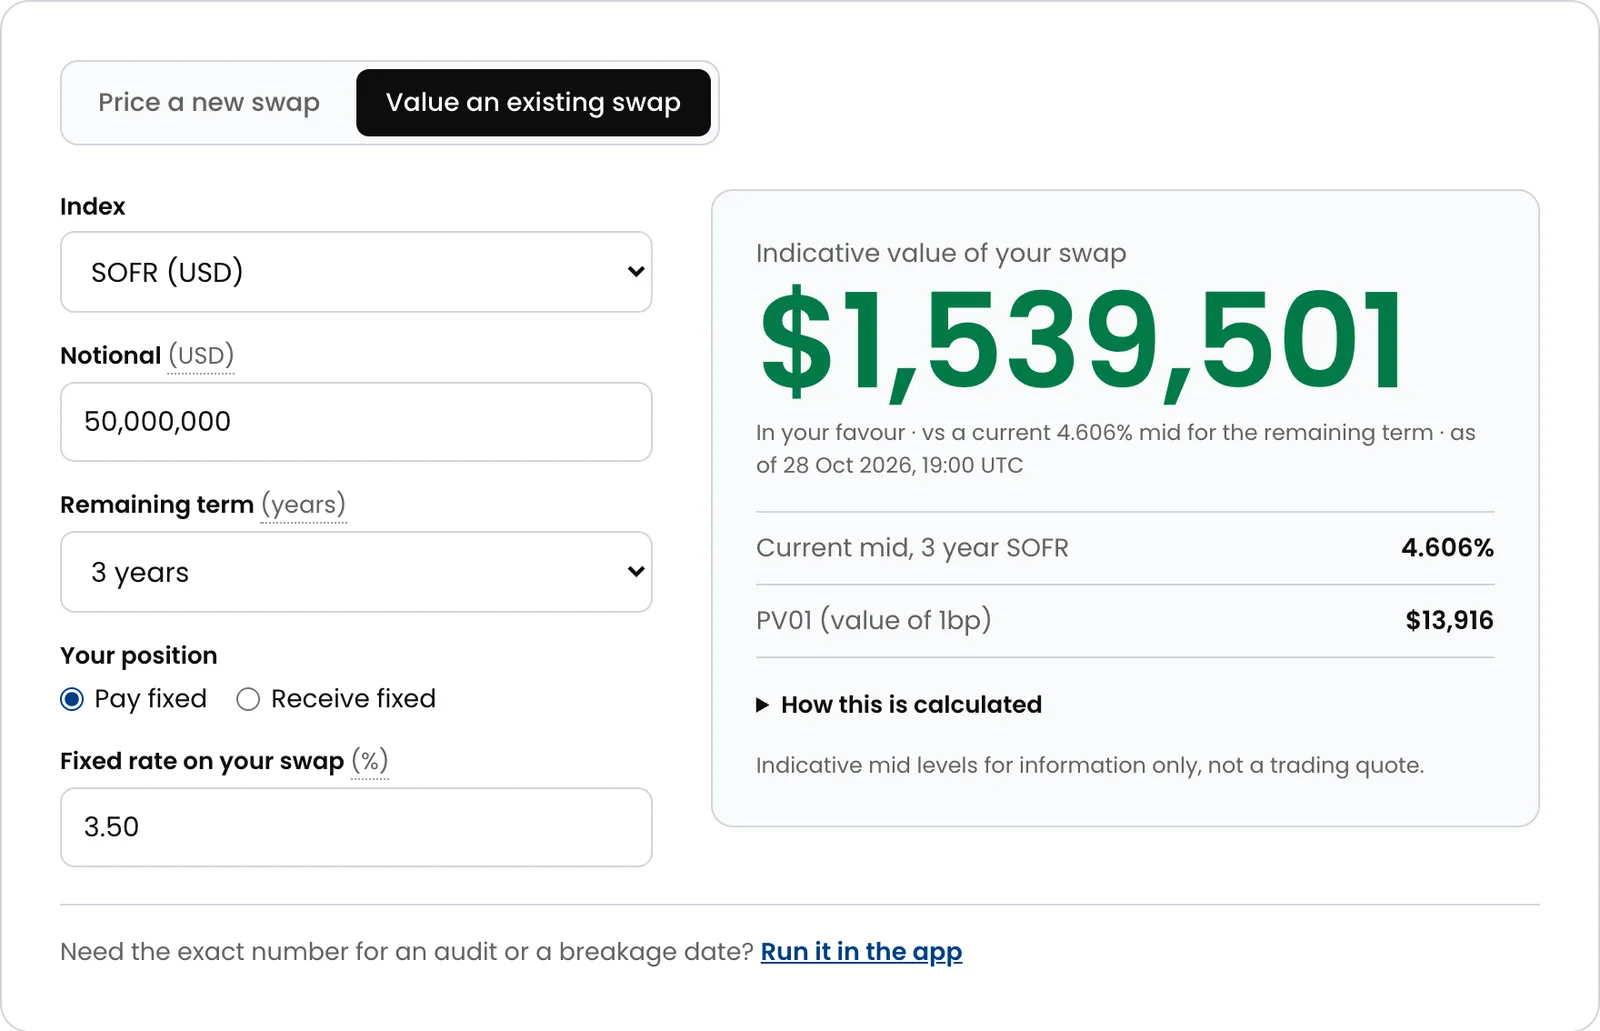
- 02
Read the mid, then see how it runs down
The live MtM is the mid breakage. Quoted breakage minus mid is the bank’s unwind charge, now a line you can negotiate.
The forecast rolls the swap forward on today’s curve, so you can see whether waiting a few payment dates pays.
- 03
Model the exit, and re-run it every week
Terminate and re-hedge, or roll the legacy rate? Adding a top-up? Weight the fixed rates by PV01. Buying the rate down? Divide the cash by the BPV.
The mark won’t sit still: on a $50m swap with three years left, every basis point is about $13,700. Reload it each week.
app.bluegamma.io/swap-mtm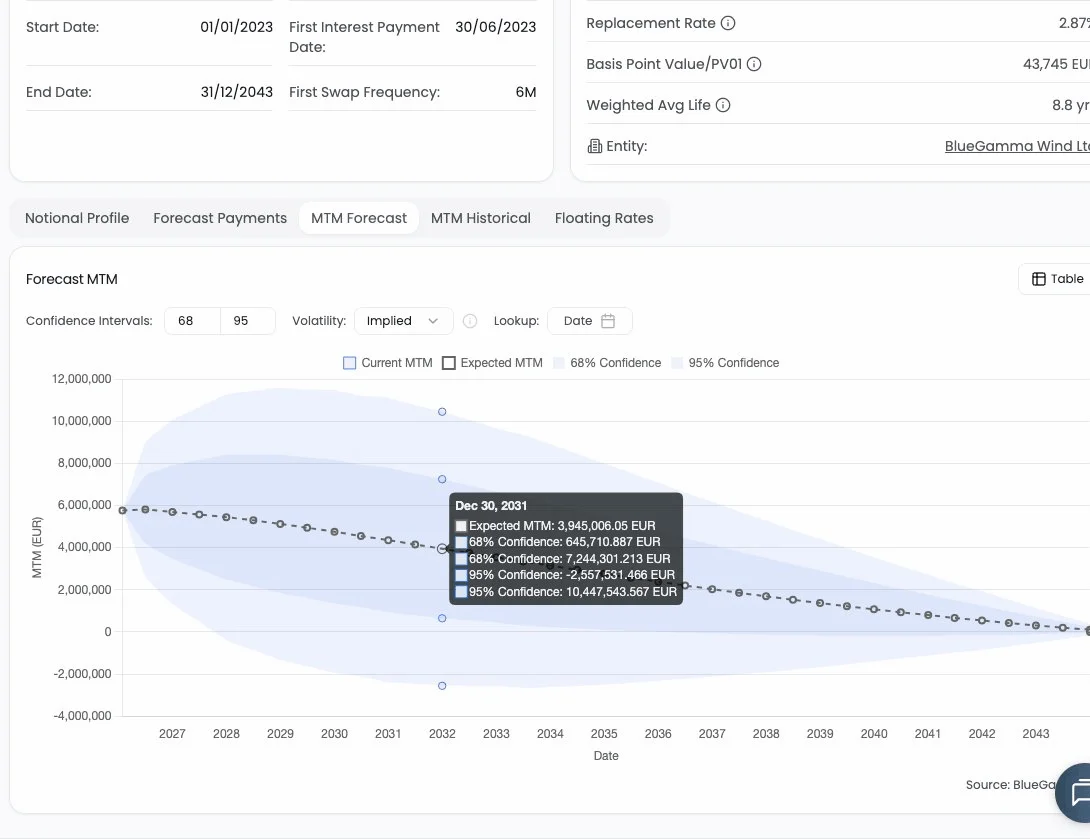
In their words
“All I did was, in your trial version, I just set up two swaps. One was a mark to market and one was looking at the new, and then it was very easy to price it on that basis. We got very similar results to the bank, so it worked.”
“They're just asking: if we were to terminate the swaps today and enter into new swaps, what would that look like in terms of NPV versus rolling it over? It's like a weekly analysis we have to do, but I didn't expect terminating existing swaps would be actually OK.”
“We need to know where we stand in terms of the swap if I have to terminate today or in three months' time.”
Your options when the breakage question lands
The bank you're leaving sets the breakage price, and a homemade sheet is only as good as its curve. BlueGamma gives you an independent mid and a breakage forecast you can rerun every week.
| Criterion | BlueGamma | Asking your current bank | Your own Excel valuation | Terminal |
|---|---|---|---|---|
| Is it independent of the bank you're leaving? | Yes | No, that bank sets the price | Partly, it still needs a curve from somewhere | Yes |
| Is it priced on your exact swap? | Yes, amortising and custom profiles | On request, when they get to it | Only as good as your curve | Only if you put it together yourself |
| Can it forecast the breakage cost? | Yes, projected down to zero at maturity | No | Only if you build it | Not out of the box |
| Can it price an off-market restructure? | Yes, each phase priced as a swap | Yes, at their margin | Days of work, and hard to audit | Hard in practice |
| Can you rerun it every week? | Yes, reload the saved swap | No, you can't call the desk every week | You copy and paste, and the market has moved | Yes, if you have a seat |
Questions teams ask
Breakage is the swap's mark-to-market: the present value of the remaining fixed payments against the floating leg, discounted off today's curve. If rates have fallen since you fixed, the swap is against you and you pay the bank to break it; if rates have risen, it is in your favour and the bank pays you.
The bank quotes the mid plus its own charge: unwind spread, credit and capital adjustments, and margin. Without an independent mid you can't see where one ends and the other begins. A mid within about 1bp of the bank's own makes the charge visible, as long as the trade details match.
Compare the value of breaking today and re-hedging at market with keeping the legacy fixed rate; the answer depends on where your rate sits against today's curve. Advisers re-run it weekly while the deal is live.
Weight each swap's fixed rate by its PV01, not just its notional. For example, an existing swap at 4.19% plus a top-up at 4.81% might blend to roughly 4.36%, depending on relative sizes and remaining tenors.
Divide the upfront amount by the swap's basis point value (BPV or PV01) to see roughly how many basis points the fixed rate moves. On a $50m swap with three years left, each basis point is worth about $13,700, so $1m buys down roughly 73bp.
Yes. Load the swap once and the mark-to-market recalculates off curves refreshed every 30 seconds, with no download limits. Teams that post collateral use it to check the bank's margin calls.
Related guides
Get your own breakage number before the bank gives you theirs
Load your swap, check the MtM against the bank's last statement, and walk into the refinancing with an independent mid.