How do I check whether my bank's swap quote is fair?
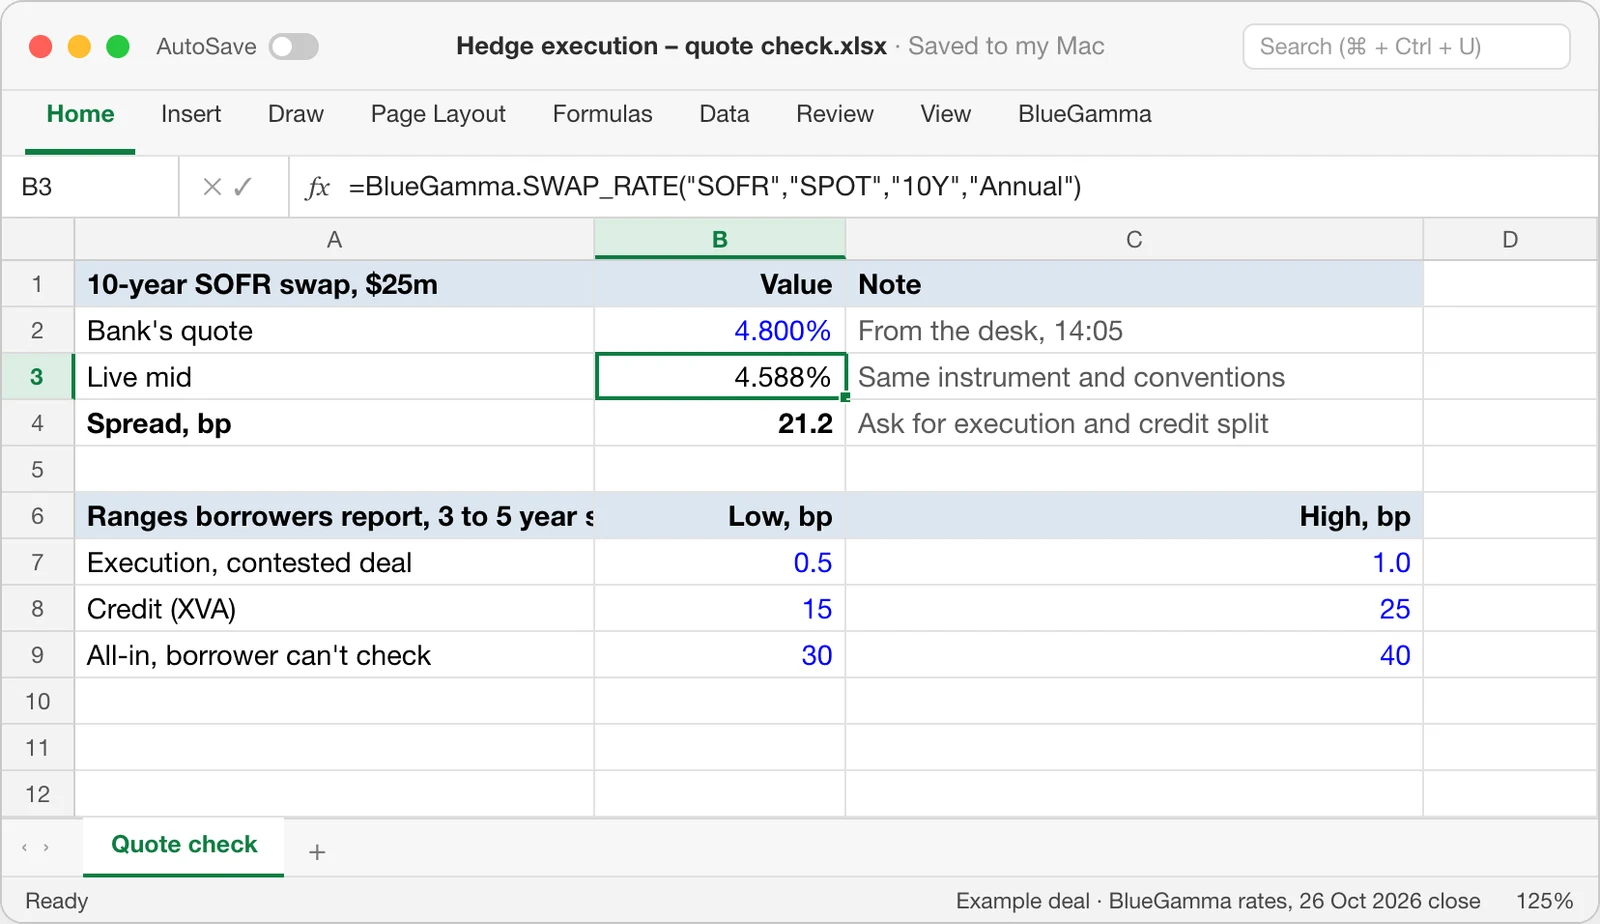
Price the swap yourself before you sign. Load your exact notional profile, read the live mid swap rate, and subtract it from the bank’s quote. The gap is the bank’s margin, and it is the number you negotiate.
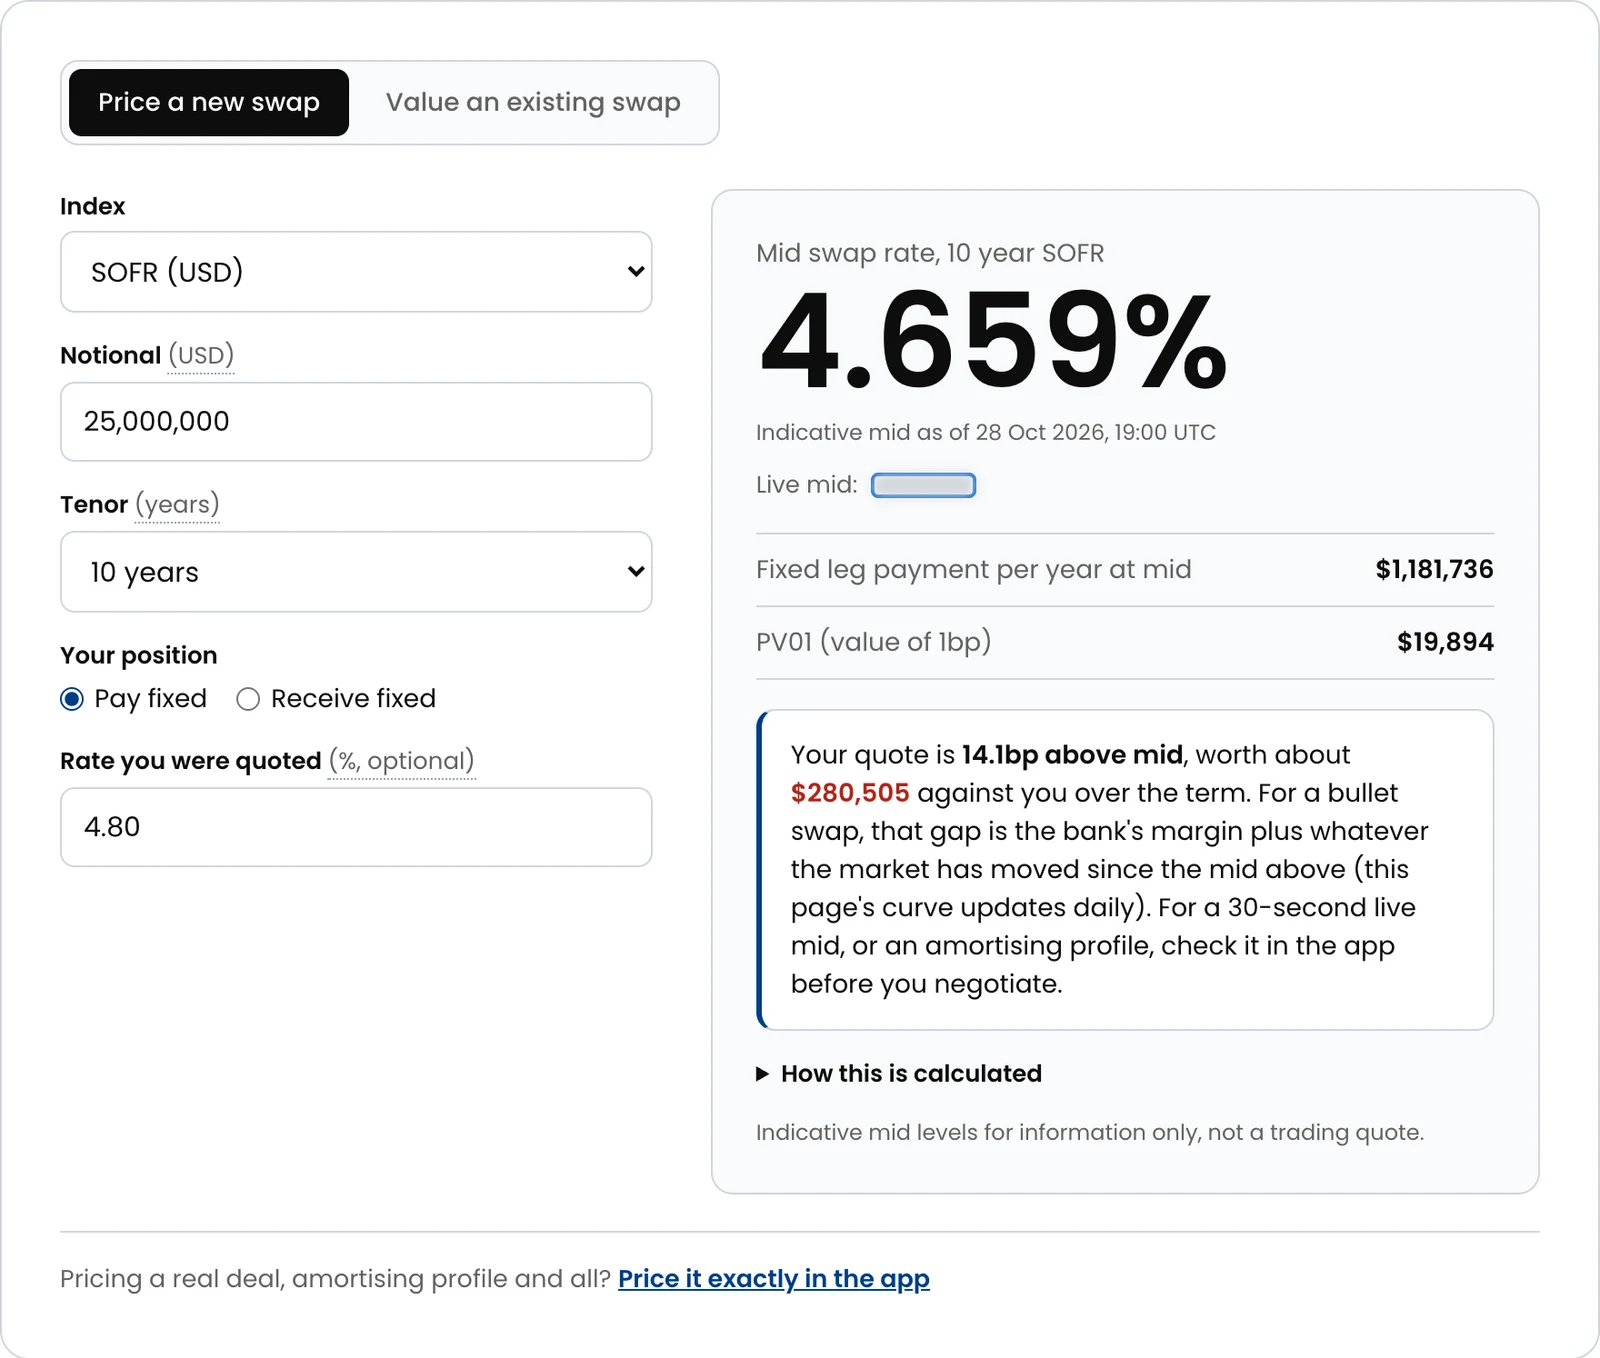
- ~1bpfrom the bank's own mid, same instrument and time
- 30 secrefresh from the interbank market
- 15 to 25bpcredit spread borrowers report on 3 to 5 year swaps
- 12bpwhat one borrower paid after pushing back on at least 20 to 25bp
Today, and with BlueGamma
How it usually gets done
- A weekly rate table from the hedge bank, interpolated by hand and days old by execution.
- Ringing other banks for quotes you'll never trade, and spending goodwill each time.
- Paying an adviser per deal to price it on their screen, on their schedule.
With BlueGamma
- The live mid on your exact amortising or sculpted profile, in minutes.
- The bank's margin in basis points, and the questions that split it into execution and credit.
- The same number in the web app, in Excel or from the API, while you negotiate.
Not the right fit if you trade swaps every day and need execution on the same screen. A dealer platform is built for that; BlueGamma is built for checking the price before you sign.
How it works
- 01
Load the trade the bank is quoting
Upload the notional schedule straight from your debt model: bullet, amortising or sculpted. Set the start, maturity and floating leg, and match the desk’s payment conventions.
On an amortising trade the headline tenors mislead; the pricer prices every period of the schedule you actually have.
app.bluegamma.io/swap-pricer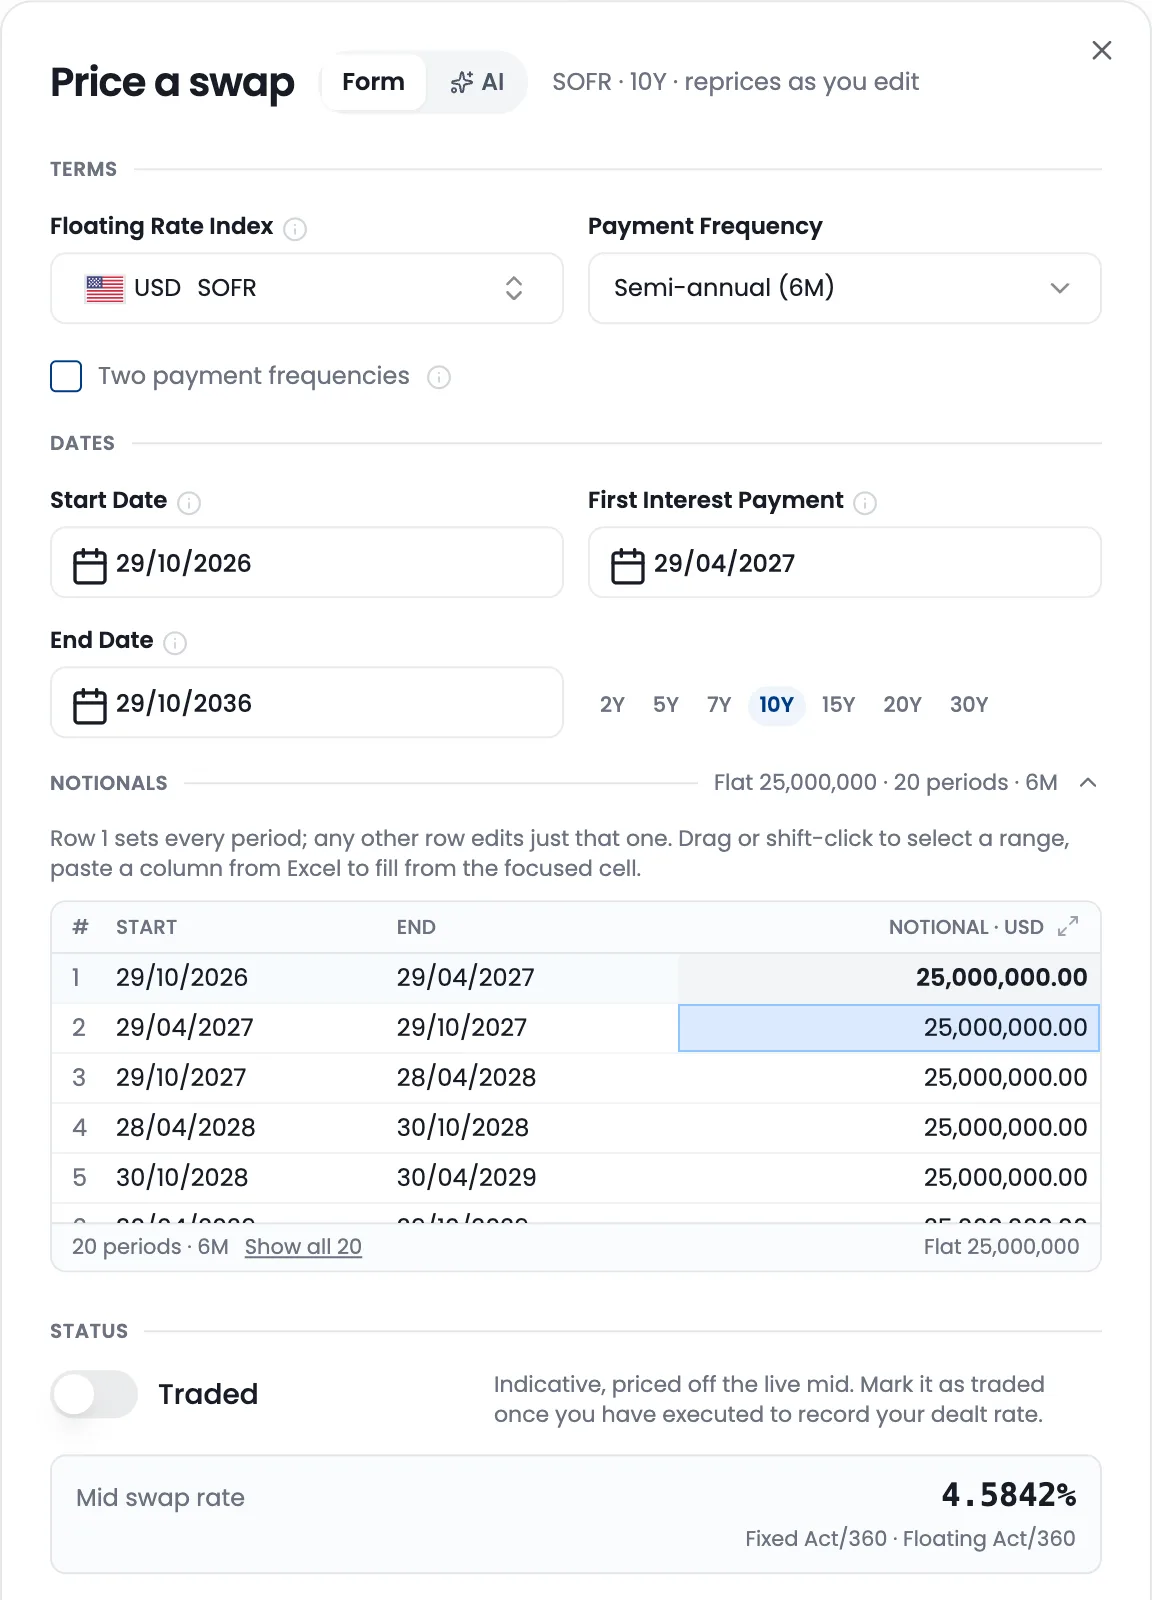
- 02
Read the live mid and subtract
The pricer returns the mid on that exact profile from live interbank data. Quoted rate minus mid is the bank’s charge. Then ask for the split: execution is often around 1bp on a contested deal; credit typically runs 15 to 25bp.
- 03
Keep watching while you negotiate
app.bluegamma.io/usd/sofr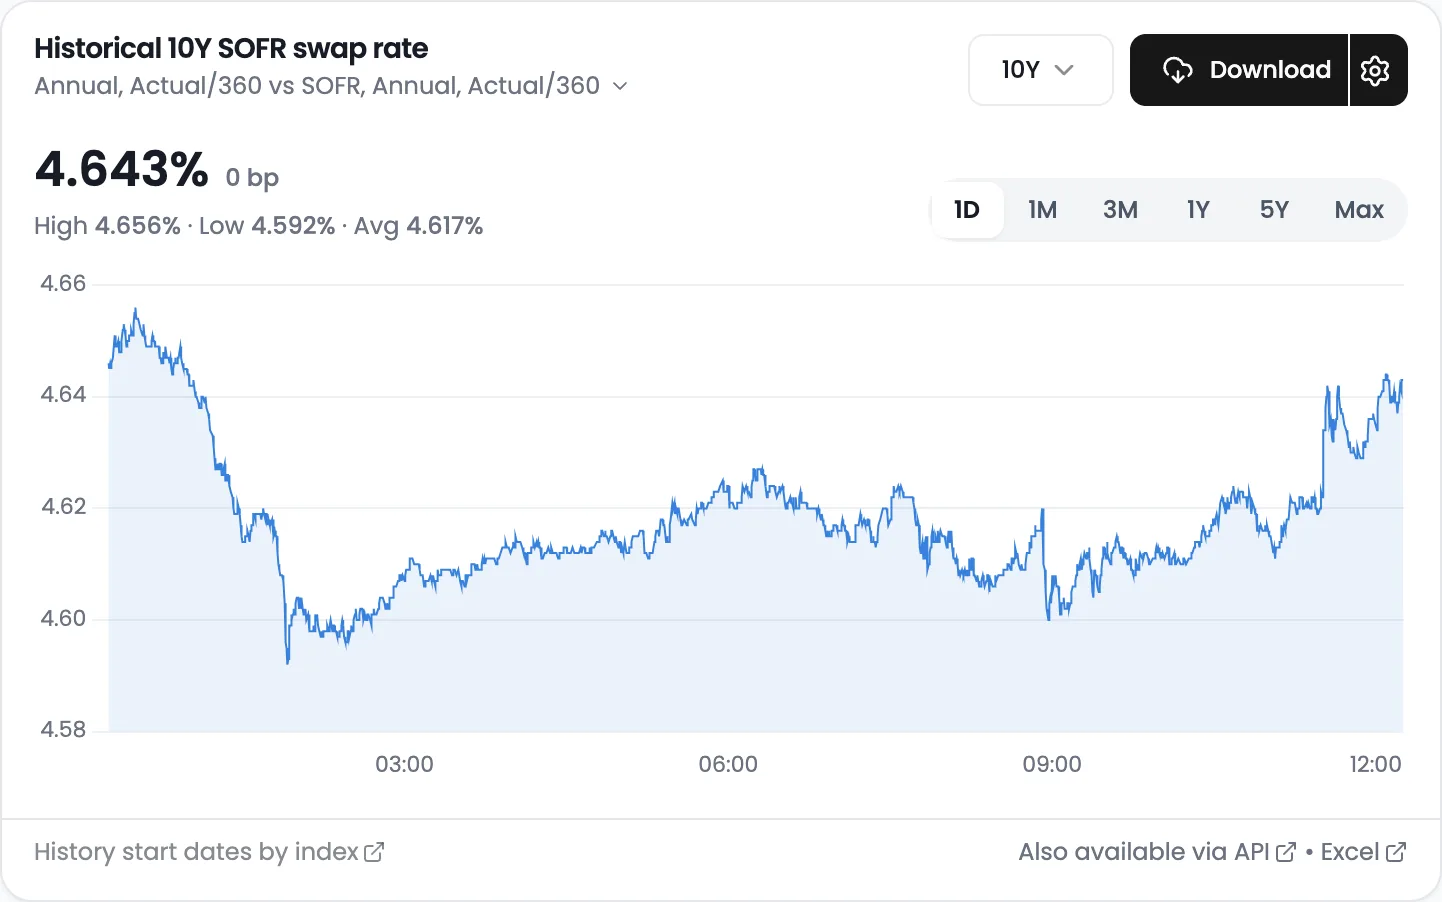
What the spread is made of
In their words
“The first quote I got, I knew it had at least 20 or 25 basis points embedded. And then I'm like, listen, I'm not paying more than 12, so they just cut it down to 12.”
“When I'm doing my hedging, I want to make sure that I can validate the rates I'm getting from the bank swap desk. I just want to make sure I keep the bank honest.”
“The idea is to have a tool to make the challenge by ourselves, not to be dependent on an adviser systematically.”
Among the 100+ financial institutions on BlueGamma


Your options, compared
Your bank's own table can't show you its margin, and asking other banks or an adviser takes time. BlueGamma gives you an independent mid on your exact swap, live.
| Criterion | BlueGamma | Your bank's rate table | Asking other banks | A hedging adviser |
|---|---|---|---|---|
| How up to date is the rate? | Live, refreshed every 30 seconds | Updated weekly | Whenever the desk replies | Whenever the adviser is free |
| Is it priced on your exact swap? | Yes, upload your notional schedule | No, standard tenors only | Yes, in their quote | Yes, in their report |
| Is it independent of the bank? | Yes | No | No | Yes |
| What does it cost? | A monthly subscription | Hidden in the bank's margin | Hidden in the margin, and it uses up goodwill | A fee per deal |
| Do you keep a record of the mid? | Yes, historical rates and past curves | Weekly snapshots | Only what you wrote down | Their report |
Questions teams ask
Price the same swap independently and compare. Upload the exact notional profile (bullet, amortising or sculpted) to a swap pricer fed by live market data, read the mid swap rate, and subtract it from the bank's quoted fixed rate. The difference is the bank's margin, and that number, not the headline rate, is what you negotiate.
The mid is the midpoint between where dealers bid and offer the swap in the live interbank market: the fair-value rate before any bank adds its charge. It is not a survey or an average of bank quotes. Banks quote clients mid plus a spread for credit, capital and profit, so once you can see the mid for your exact structure, the spread is visible.
Yes. In BlueGamma's swap pricer you upload the notional schedule from your model, set the dates and floating leg, and it returns the live mid swap rate on that exact profile, the number a bank's desk computes before adding its spread.
BlueGamma takes swap data from the same interbank market the banks and premium terminals use, refreshed every 30 seconds. On the same instrument, conventions and timestamp, the mid you compute should sit within about a basis point of the mid the bank sees.
The charge is an execution spread plus a credit (XVA) spread. On a contested project finance deal, execution is typically around 1bp and negotiable towards 0.5bp, while the credit spread commonly runs 15 to 25bp depending on tenor, notional and security. Borrowers who couldn't check have told us they paid 30 to 40bp all-in on 3 to 5 year swaps. Ask for the split, not just the all-in rate.
You can, but relationship banks know when a quote request won't turn into business, and asking often spends goodwill you may need for the next facility. It is also slow: on execution day you often have hours, not days. An independent mid removes both problems.
Usually. Banks price off the same interbank market, and advisers who have compared BlueGamma's numbers with the bank's on a closing call tell us the difference was about a basis point. Signalling that you verify quotes changes how you get priced.
Swap rates, forward curves and cap pricing across 30+ currencies, including SONIA, SOFR, EURIBOR, ESTR, BBSW, CORRA, SARON, JIBAR and EIBOR.
Related guides
Check your next quote before you sign it
Load your notional profile, see the live mid, and know the bank's margin before the desk calls back.