What does our debt cost in the investor's currency?
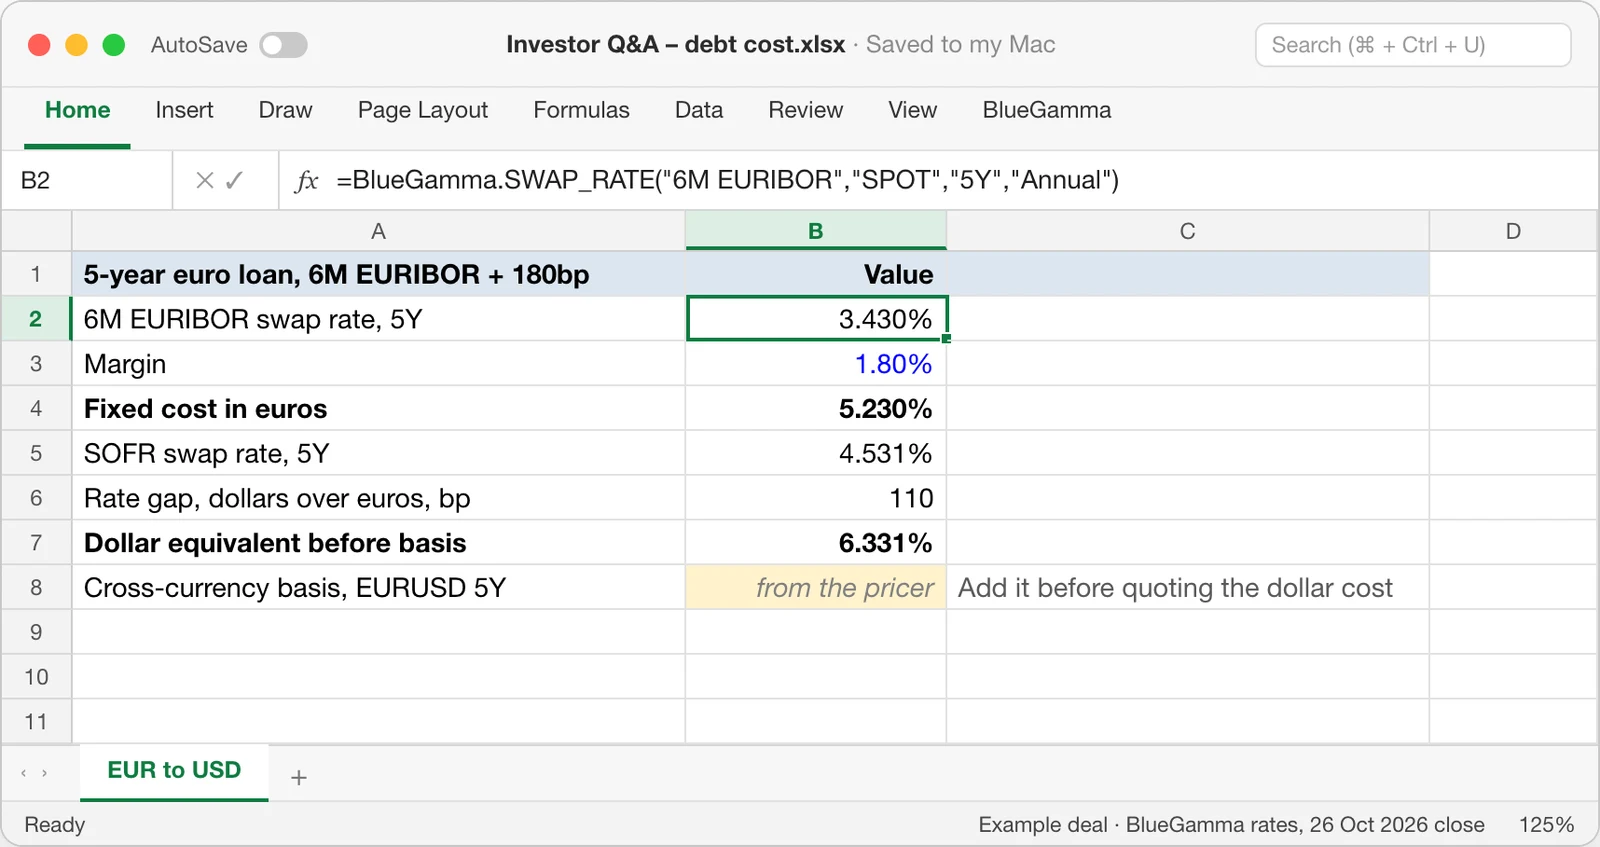
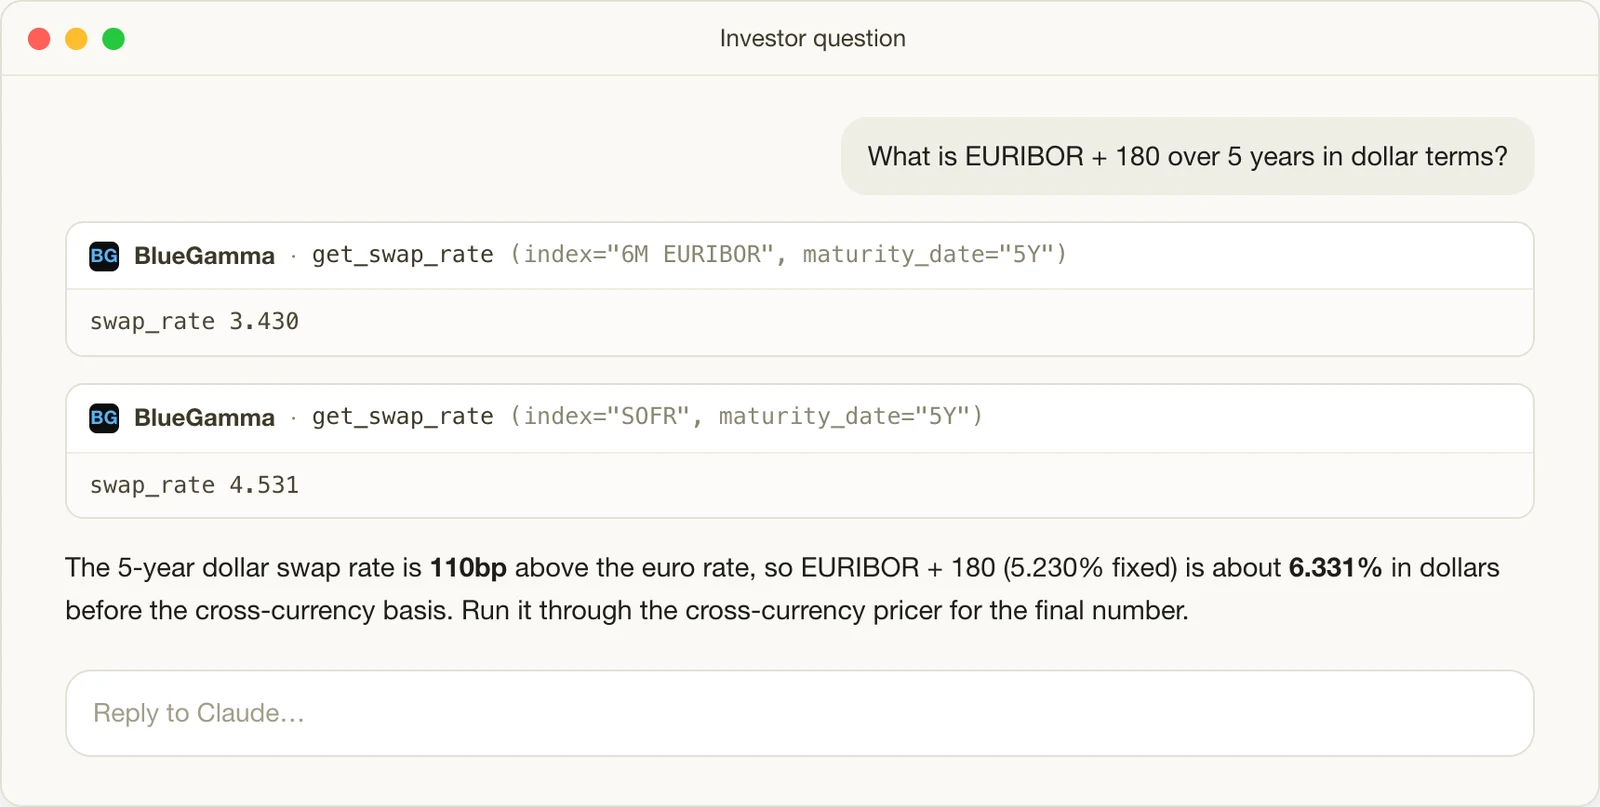
Restate the debt through both swap curves and the cross-currency basis, not just the gap between the two swap rates. Today the 5-year dollar swap rate sits 110bp above the euro rate, so EURIBOR + 180 is not “180 over” in dollars. Price both legs off the market the banks use, so the numbers should reconcile.
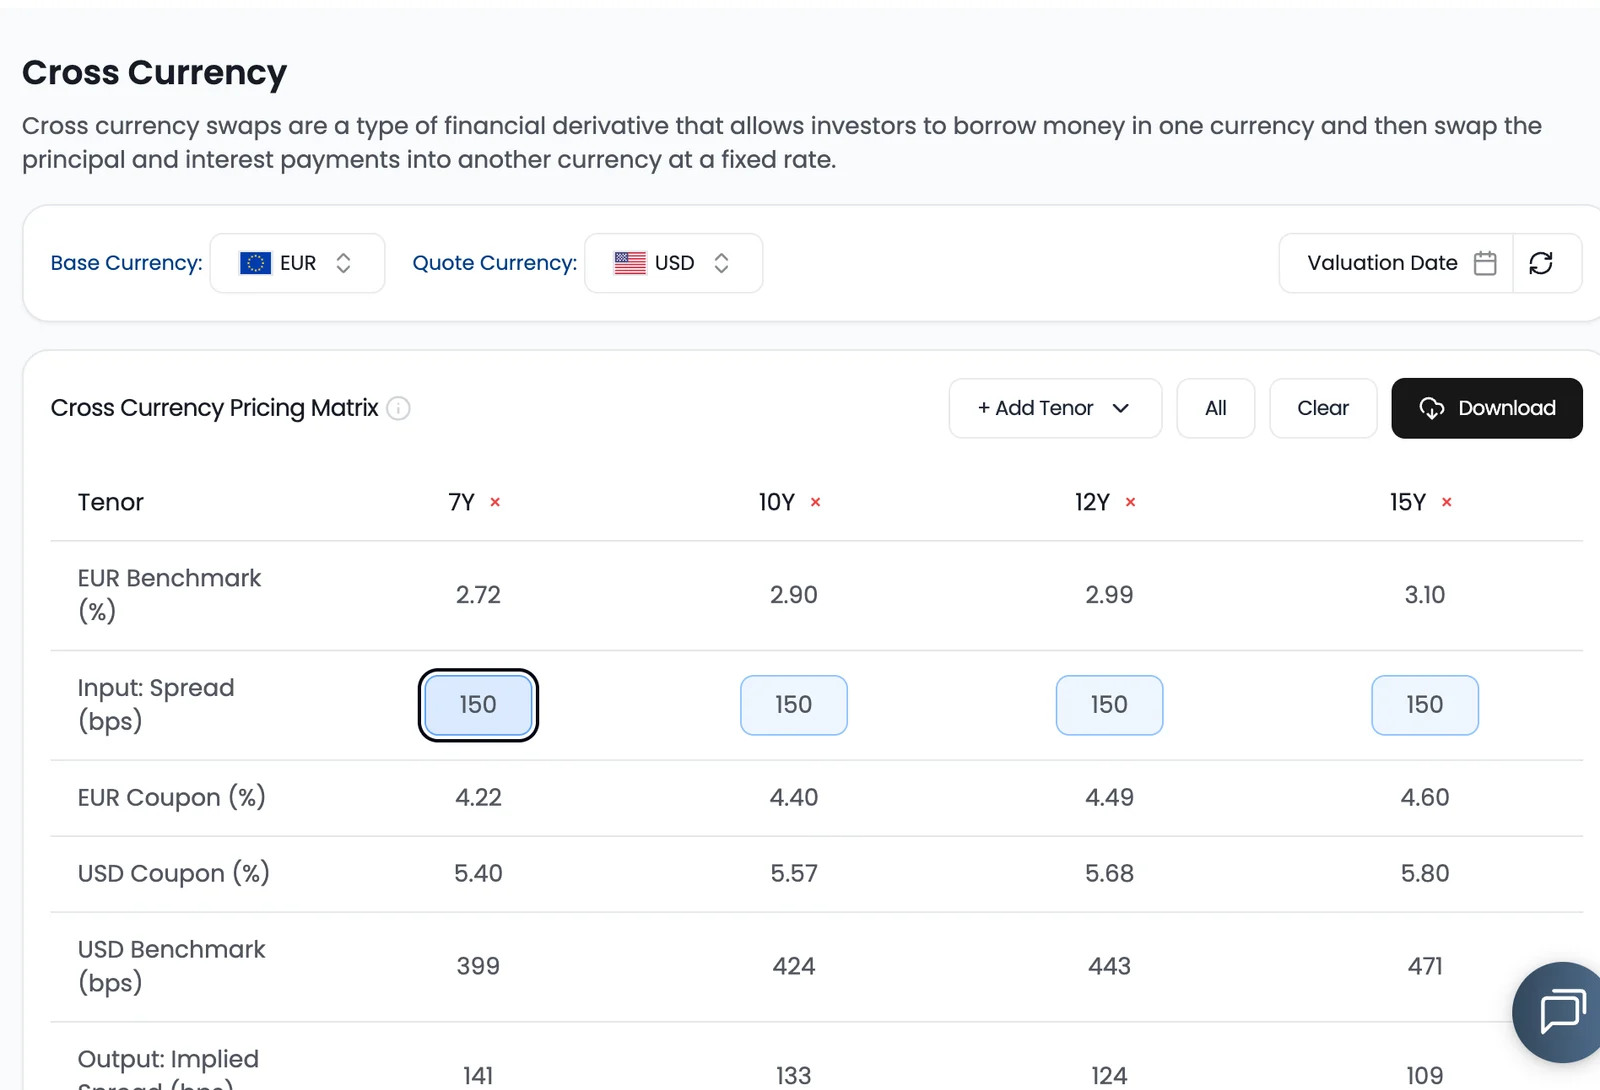
- 110bpEUR to USD gap in 5-year swap rates today, before basis
- ~1bpfrom the bank's own mid, same instrument and time
- 5bpthe margin one treasury team found inside a bank's cross-currency quote
Today, and with BlueGamma
How it usually gets done
- A rate-gap translation that drops the basis and won't tie out.
- FX forwards, which embed the basis but thin out beyond about two years.
- Asking the hedge bank, which bakes its spread into the conversion.
- Handing the client a benchmark and letting their team convert it on their screen.
With BlueGamma
- Both curves, FX and the cross-currency basis applied in one step.
- The spread in the investor's terms, within about 1bp of the bank's mid.
- The same numbers in the web app, Excel, the API or through Claude.
Not the right fit if you need the cross-currency swap executed. BlueGamma prices it independently; the bank still executes it.
How it works
- 01
Set up the debt in its home currency
Pick the benchmark (EURIBOR, SONIA, SOFR, ESTR and more), then the margin, tenor and notional. Amortising or sculpted profile? Upload it rather than forcing a bullet.
app.bluegamma.io/eur/6m_euribor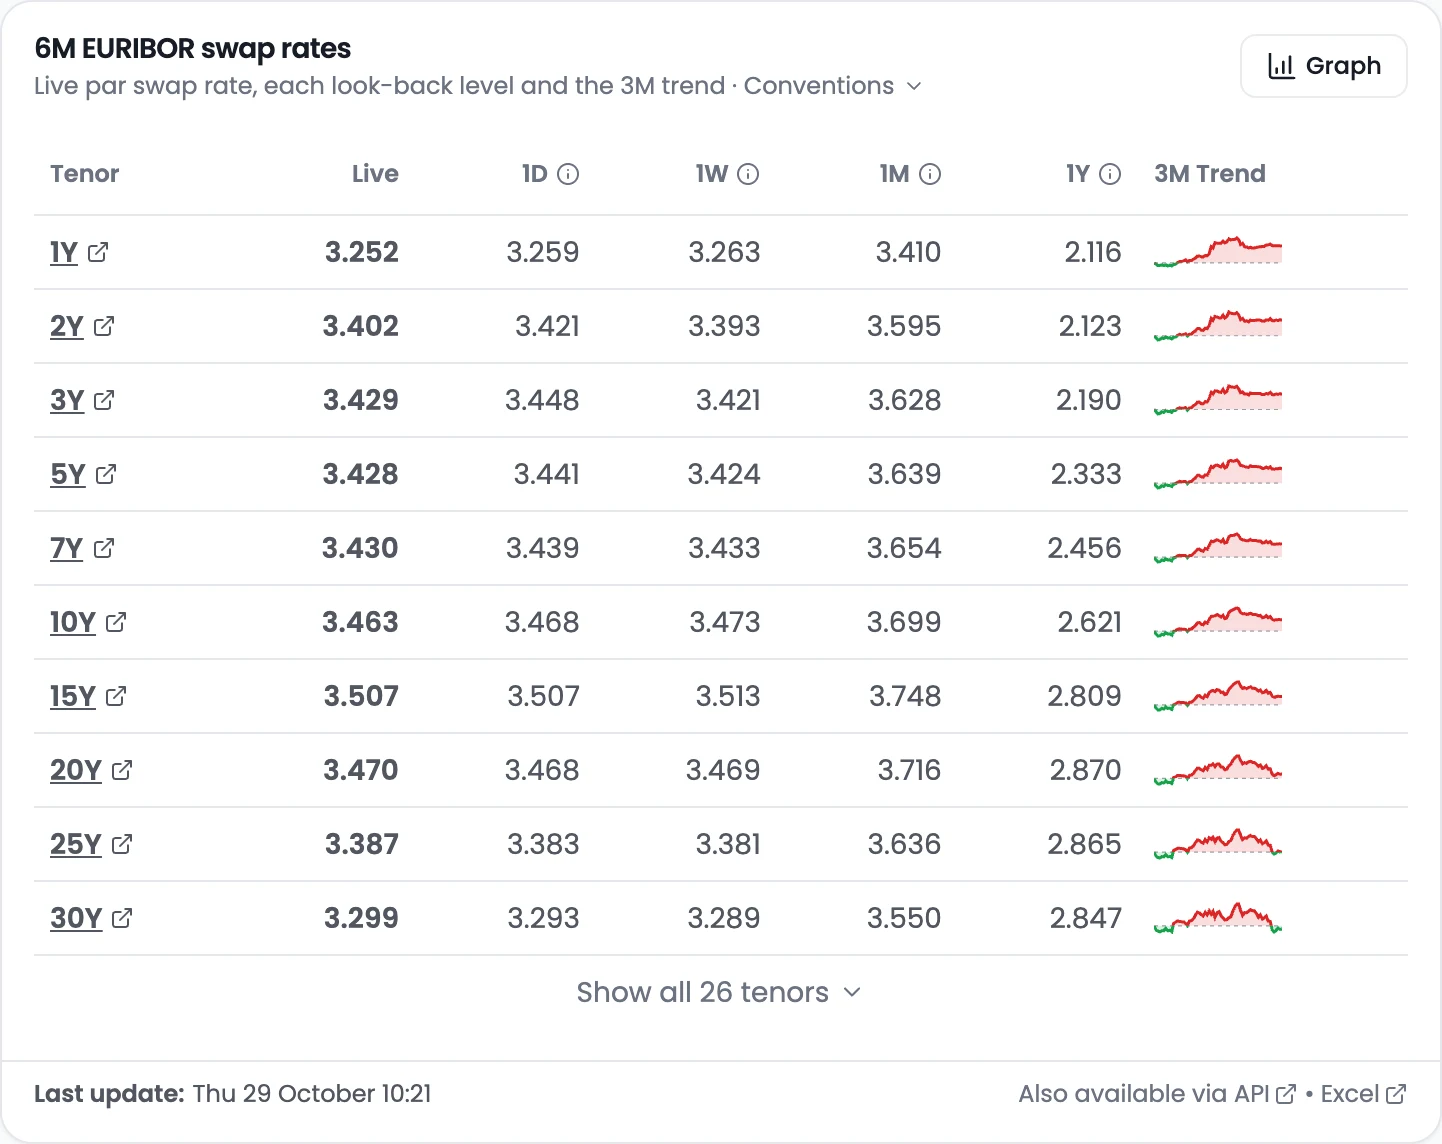
- 02
Restate it in the investor's currency
Choose the target currency. BlueGamma applies both curves, the FX rate and the cross-currency basis for the pair. The basis is the piece a rate-gap translation silently drops. Here the euro leg is 6M EURIBOR, an IBOR, against SOFR, an overnight rate, so a full conversion also accounts for the basis between those two kinds of benchmark.
- 03
Check it reconciles, then put it in the model
In their words
“Now we know that, based on market forward curves, the actual cost, no arbitrage price is 1%, and now banks are quoting us .95. That means banks are putting .05 in their pocket.”
“They're like, OK, what's that in euros? And then we have to try to work that out, and they will say a number, I will say a number. I then need to have reliable numbers. If my data is off, then I just look not reliable.”
“What's the same return converted to euros and USD, because that's what gets pushed back up to our kind of financial backer in the US.”
Your options, compared
The bank's quote includes its margin, and a spreadsheet goes stale once it's pasted. BlueGamma gives you an independent mid, basis included, in minutes.
| Criterion | BlueGamma | Asking the hedging bank | FX forwards in a spreadsheet | A hedging adviser |
|---|---|---|---|---|
| Does it include the cross-currency basis? | Yes | Yes, inside their quote | Yes, but the data is thin beyond about 2 years | Usually |
| Is it an independent mid? | Yes | No, it includes their margin | Partly | Yes, on their assumptions |
| Can you price off-market or amortising swaps? | Yes, yourself | Only by going back to the bank each time | Yes, but it takes days | Only on request |
| Who can run it? | Anyone on the team: web, Excel or API | Only the bank | Whoever built the sheet | Only the adviser |
| How fast is it? | Minutes | On the bank's timetable | Out of date once it's pasted | Whenever they reply |
Questions teams ask
You need more than the gap between the two swap rates. A proper conversion takes the loan's projected cash flows through both swap curves and the cross-currency basis for the pair. FX forwards embed the basis, but they trade thinly beyond about two years, so for longer debt the conversion is built from swaps with the basis added. In BlueGamma you pick the benchmark and the investor's currency, and get the spread in their terms.
The cross-currency basis is the extra spread the market charges to swap funding in one currency for another. FX forwards do embed it, but they are thin beyond about two years, which is why longer debt is converted through the swap curves with the basis added. The shortcut that misses it is the rate gap: dollar swap rate minus euro swap rate. Leaving the basis out can move the spread by several basis points, enough that your number won't reconcile.
The two markets price off different swap curves and are linked by the cross-currency basis, so 150bp over in euros is not the same all-in cost as 150bp over in dollars.
It should, because both legs come from the same market the banks use. On the same instrument, conventions and timestamp, BlueGamma's swap rates sit within about 1bp of the bank's own mid, so most of any remaining gap to a bank's conversion is margin.
Swap rates, forward curves and FX across 30+ currencies, with cross-currency conversion for major pairs such as EUR/USD and GBP/EUR. FX forward curves also let you restate a euro loan book at forward rates for sterling reporting.
Yes. Many treasury teams wait for the counterparty to tell them the valuation because their treasury system doesn't handle cross-currency swaps. BlueGamma provides the curves the valuation needs, for GBP/EUR the SONIA and ESTR curves, and the API can feed the same curves into your systems.
Related guides
Next time an investor asks, answer in their currency on the spot
Run your own deal through the conversion on the free trial. If it doesn't reconcile with the bank's number, you'll know in ten minutes.