How do I build the interest rate assumptions for a project finance bid?
Pull the live forward curve for the exact benchmark your debt prices off, price the swap on your sculpted, forward-starting profile, and put the mid in the model. Then refresh it at every committee gate, so the number the debt sculpts off is the market’s, not last quarter’s.
- +9bphow far one IPP’s modelled swap strike moved, April to July
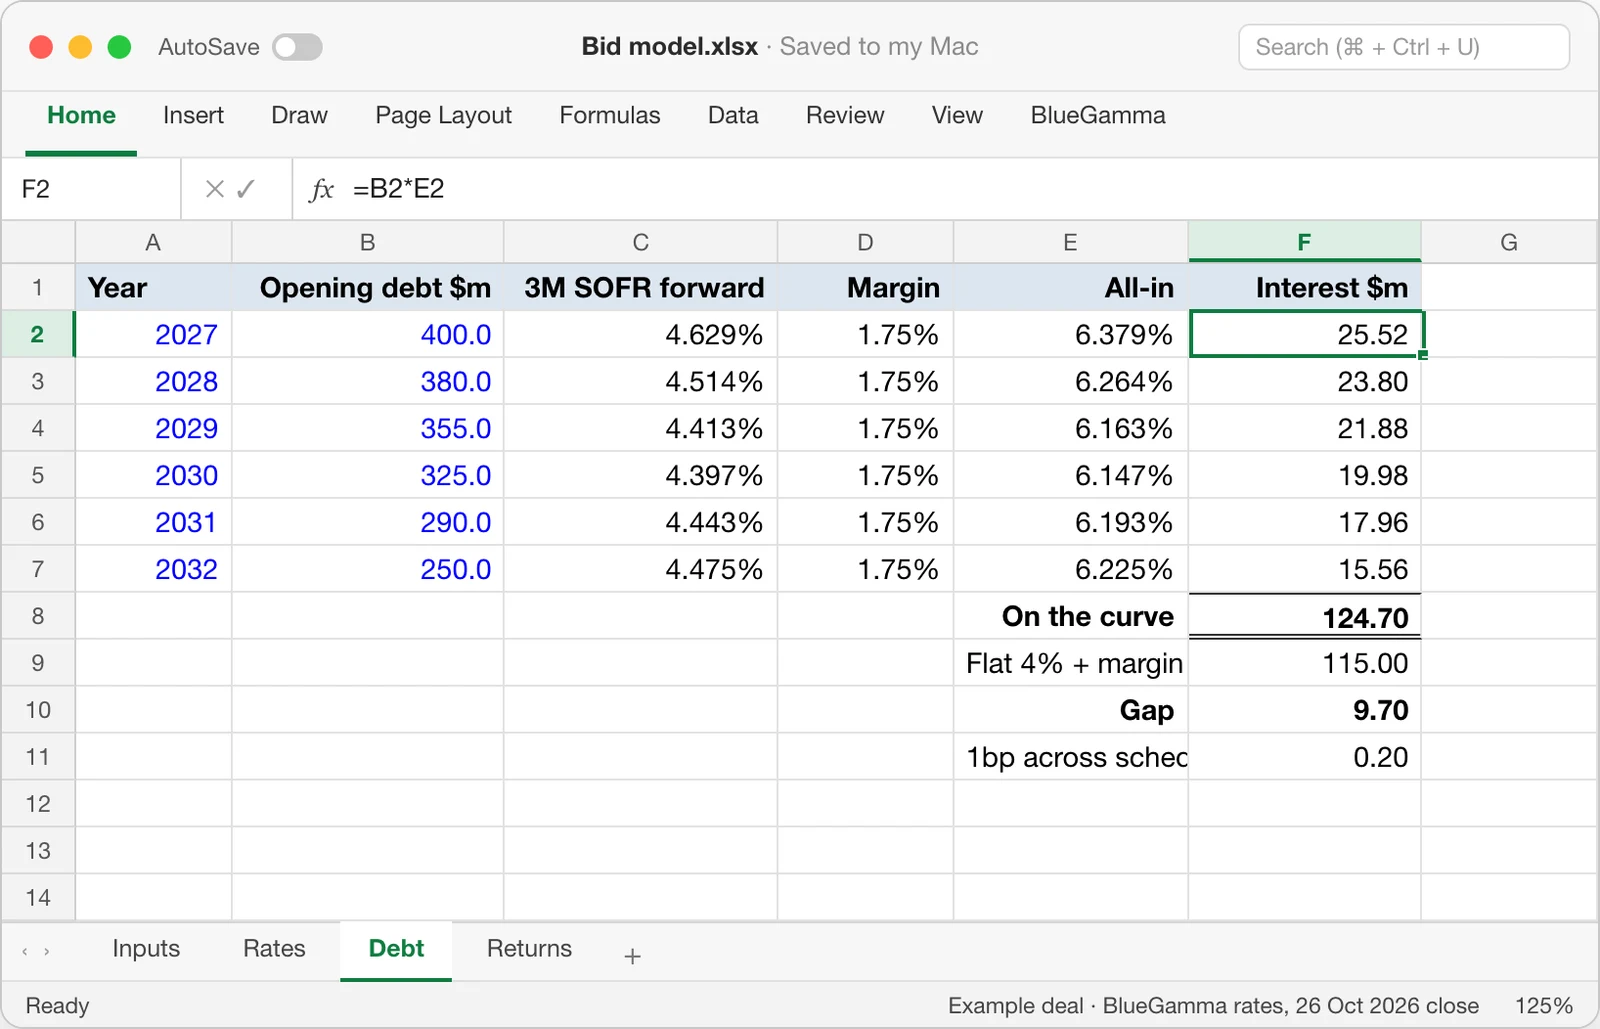
- $200kwhat 1bp costs over the life of the example schedule, undiscounted
- 77bprange of the 5-year SOFR swap rate in the last three months
- ~1bpfrom the hedge bank's own mid on the same profile
Today, and with BlueGamma
How it usually gets done
- A placeholder: 4% plus spread, or a swap quote from months ago that feels about right.
- Screenshots from lenders, and a call to the bank every time the model updates.
- For less-tracked benchmarks, a consultant doing you a favour.
With BlueGamma
- The live forward curve for the benchmark your debt prices off, in 30+ currencies.
- The mid swap rate on your sculpted, forward-starting profile.
- Excel formulas that refresh the model in minutes before each committee gate.
Not the right fit if you need the bank's executable hedge at financial close. Use this to set the assumption, then to check that quote.
How it works
- 01
Pull the forward curve for the exact benchmark
SOFR, EURIBOR, SONIA, EIBOR, JIBAR, BBSW or CORRA: open the benchmark your debt prices off and read the forward curve out to the long tenors a project needs. No proxying off a USD curve.
app.bluegamma.io/interest-rate-curves/usd/sofr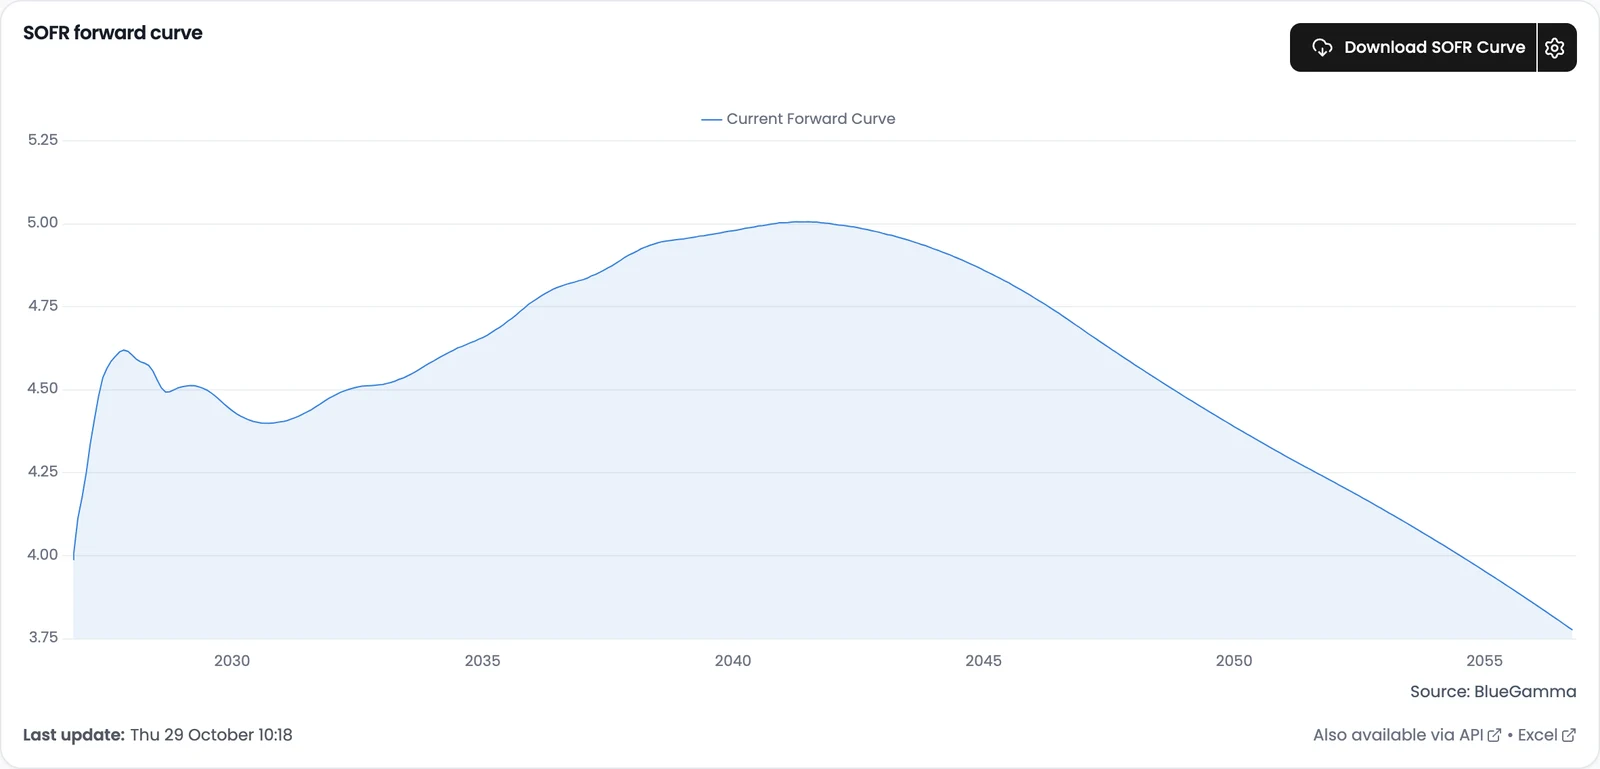
- 02
Price the swap on your sculpted profile, from the close date
Upload the notional schedule from your model and start the swap at the expected financial close or COD. The pricer returns the mid on that exact profile. Pricing a pipeline? Save one swap per close year.
app.bluegamma.io/swap-pricer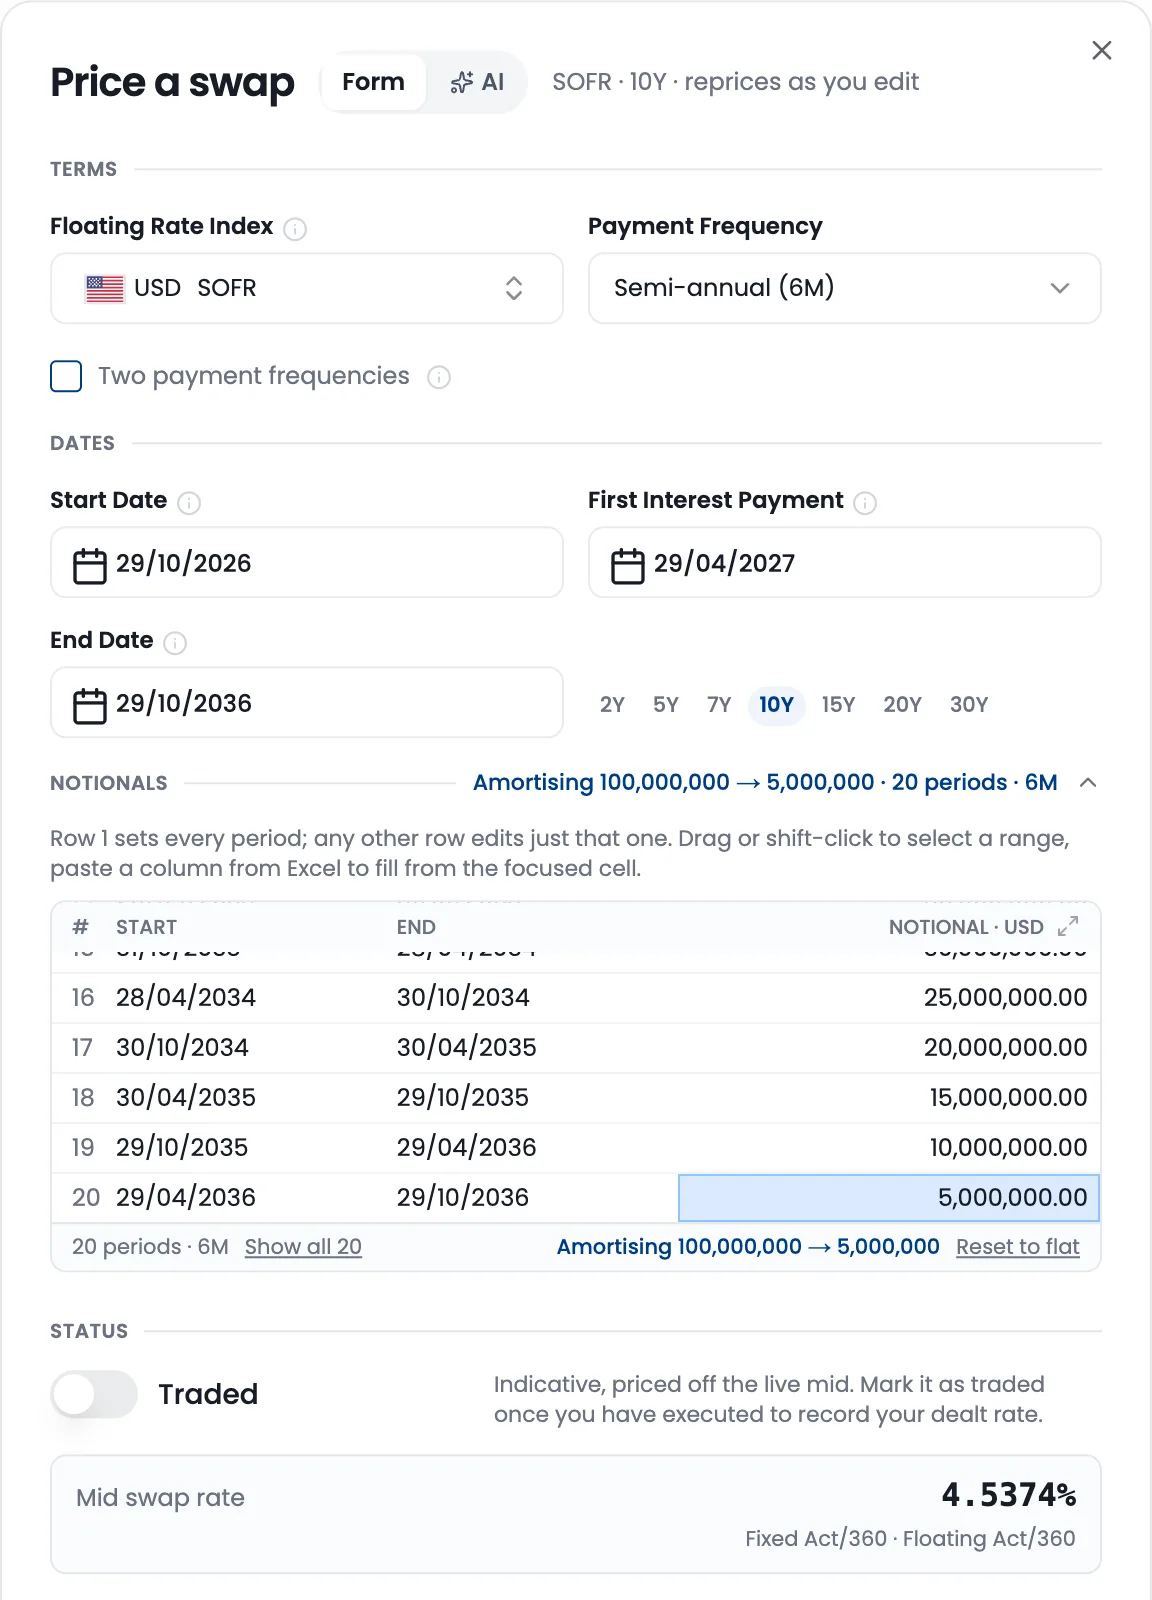
- 03
Put it in the model and refresh at every gate
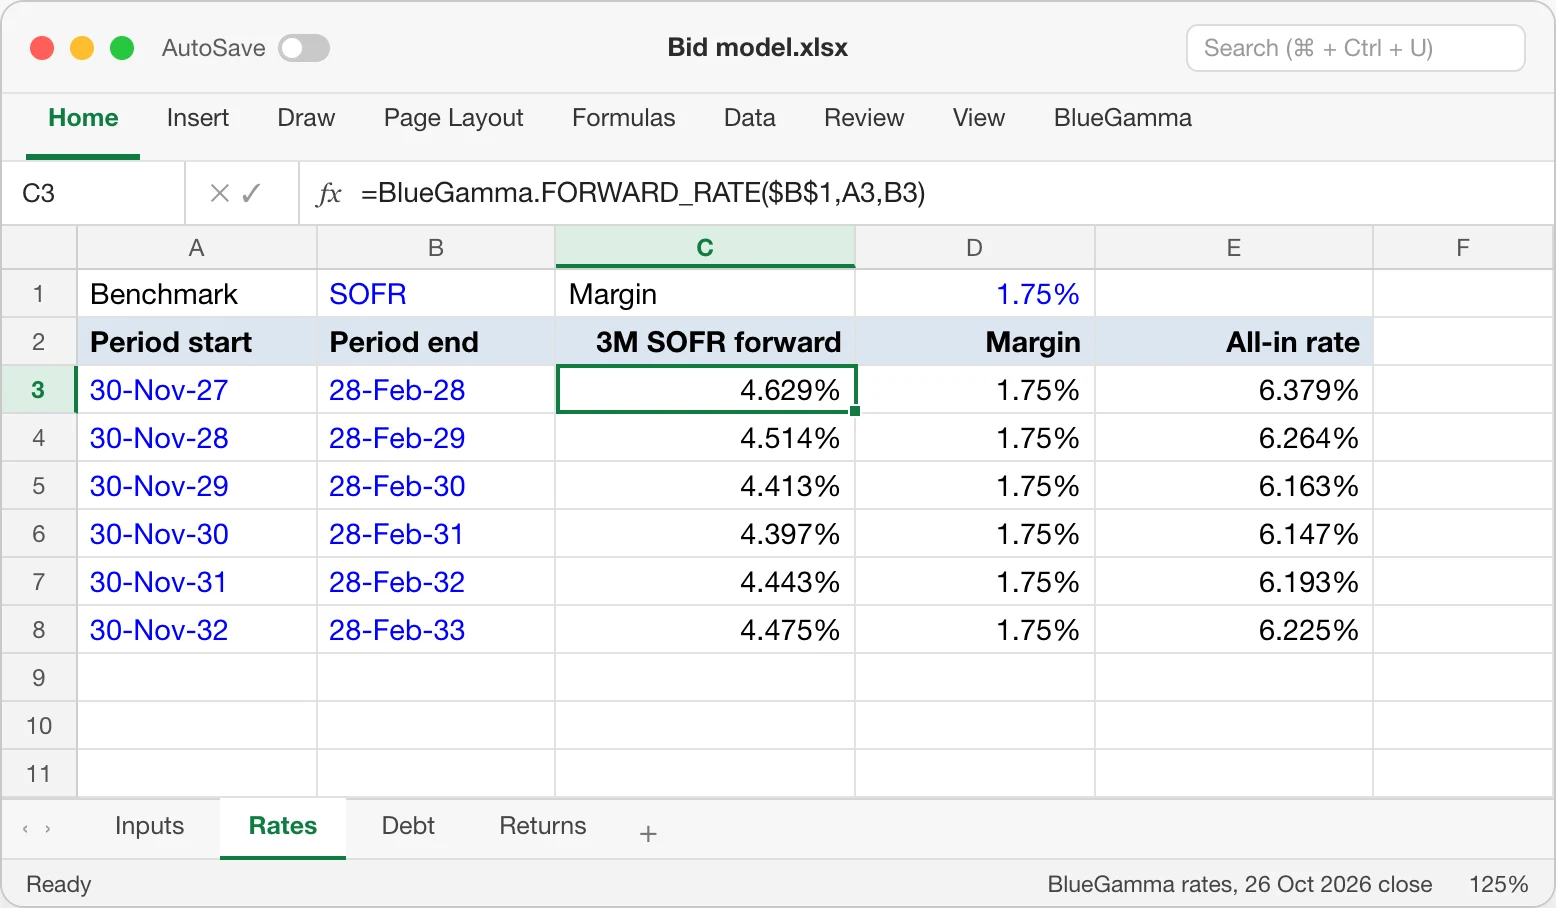
The Excel add-in returns the forward for any start and end date, so the debt schedule fills itself. Hard-code what goes in the bid, then refresh before each investment committee.
Excel · BlueGamma add-in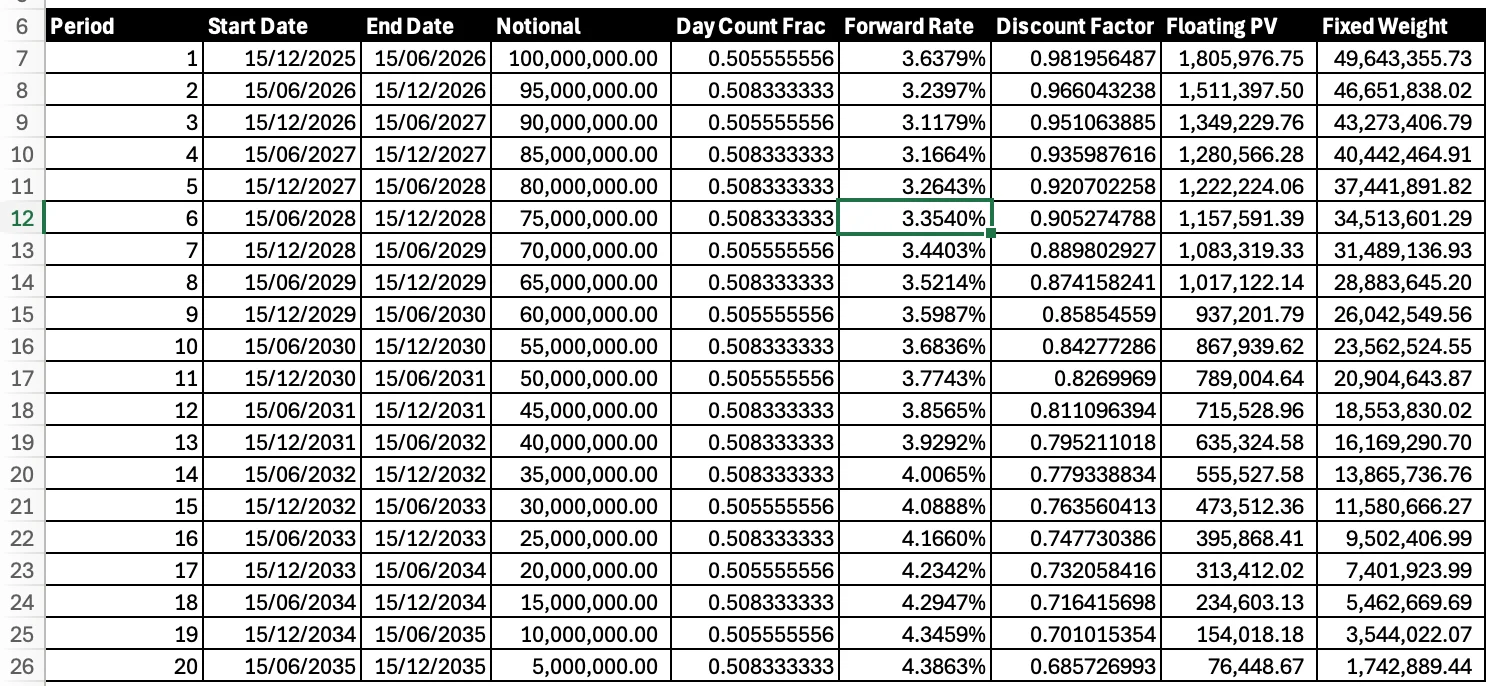
What a flat placeholder leaves out
In their words
“They use stale forward curves a lot. And I think there's a perception that it's good enough. But I've seen customers get burned when they are assuming certain rates and they just weren't keeping up to date.”
“Here in this part of the world we tend to hire a third party to validate the hedging assumptions that we're getting from the lenders, just to make sure that we're not getting robbed.”
Among the 100+ financial institutions on BlueGamma

Your options, compared
Free data rarely covers smaller markets, and an adviser charges for every refresh. BlueGamma prices your sculpted swap in each currency and reprices it in minutes.
| Criterion | BlueGamma | Free data and screenshots | A hedging adviser | Premium terminal |
|---|---|---|---|---|
| Does it cover the currency you are bidding in? | Yes, 30+ currencies in one place | Major currencies only | On request, per engagement | Yes, if you know where to look |
| Can you price a swap on a sculpted debt profile? | Yes, upload the schedule and read the mid | No, standard tenors you fill in by hand | Yes, but you ask and wait | Only if you build it |
| Can you refresh it at each stage of the deal? | Yes, reprice the saved swap in minutes | Take new screenshots each time | A new request each time | Yes, while you have the licence |
| What does it cost? | One flat subscription, for 1 project or 100 | Free, but you can't check the bank's margin | A fee per close | A terminal licence |
Questions teams ask
Use the current forward curve for the exact benchmark your debt prices off, or the mid swap rate on your actual sculpted profile, plus a buffer sized from what the market implies. A flat placeholder or a stale public number leaves basis points either on the table or unpriced.
You carry the whole rate move to close. Placeholders drift: one European renewables IPP saw a refresh between April and July move its modelled swap strike from 2.77% to 2.86%.
Yes. BlueGamma's swap pricer takes the notional schedule from your model, monthly in construction and quarterly in operations, and returns the mid on that exact profile with discount factors.
Yes. Start the swap at the expected financial close or COD date, two or more years forward. Developer teams save one forward-starting swap per close year in the pipeline and refresh them monthly.
Outside the US, free forward-curve data barely exists, so teams scrape, proxy off a USD curve or ask a bank for a screenshot. BlueGamma provides current, historical and forward curves for these benchmarks alongside SOFR, EURIBOR and SONIA, in Excel or through the API.
Look at what the market implies about the range of rates between now and financial close. Compare the forward curve with how far the same rates have moved over recent months, so you can judge whether the buffer needs to be 100bp or whether 50 is enough.
Related guides
Put a real curve behind the next bid
Pull the forward curve, price the sculpted swap, and check it against whatever your bank or adviser sends. If it doesn't tie out, don't buy it.