What's the expected IRR on a new debt deal, before committee?
Project the floating coupons off the live forward curve for the deal’s benchmark, price the hedge on the actual amortising profile, and combine the two into the IRR. On the example loan, holding SOFR at today’s fixing understates the IRR by 59bp, so re-pull the curve at each committee gate.
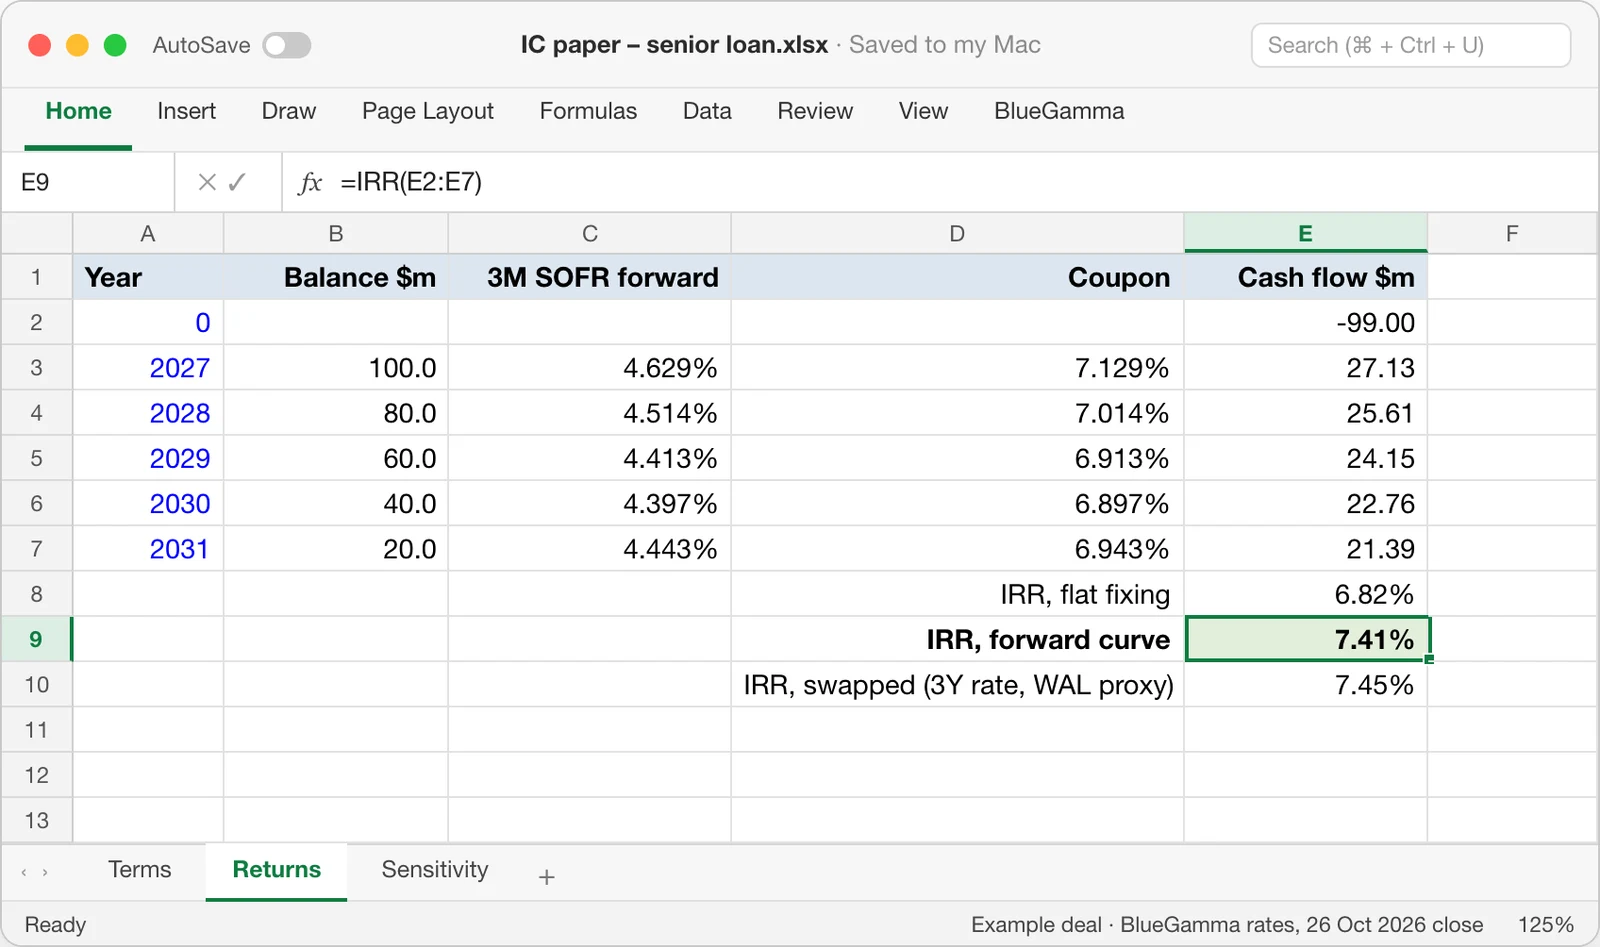
- 59bpIRR a flat fixing assumption misses on the example loan
- Any dateas-of curve archived behind the paper
- ~1bpfrom the bank's own mid, same instrument and time
Today, and with BlueGamma
How it usually gets done
- A base rate keyed in months ago, or the 7-year swap rate plus ten basis points.
- A weekly rate table from the hedge bank, blended into a curve by hand.
- A rates spreadsheet copied between models, with no date and no source.
With BlueGamma
- Coupons projected off the live forward curve for the deal's exact index.
- The hedge cost on the real amortising profile, priced the way the desk will.
- An as-of-date curve archived with the paper, re-pulled in seconds at each gate.
Not the right fit if the deal is fixed-rate end to end. With no floating leg there is nothing to project.
How it works
- 01
Project the coupons off the forward curve
Pick the index the facility floats on, at its fixing frequency, and set the valuation date. Read the forward for each interest period and add the margin; in Excel, one formula per period does it.
app.bluegamma.io/interest-rate-curves/usd/sofr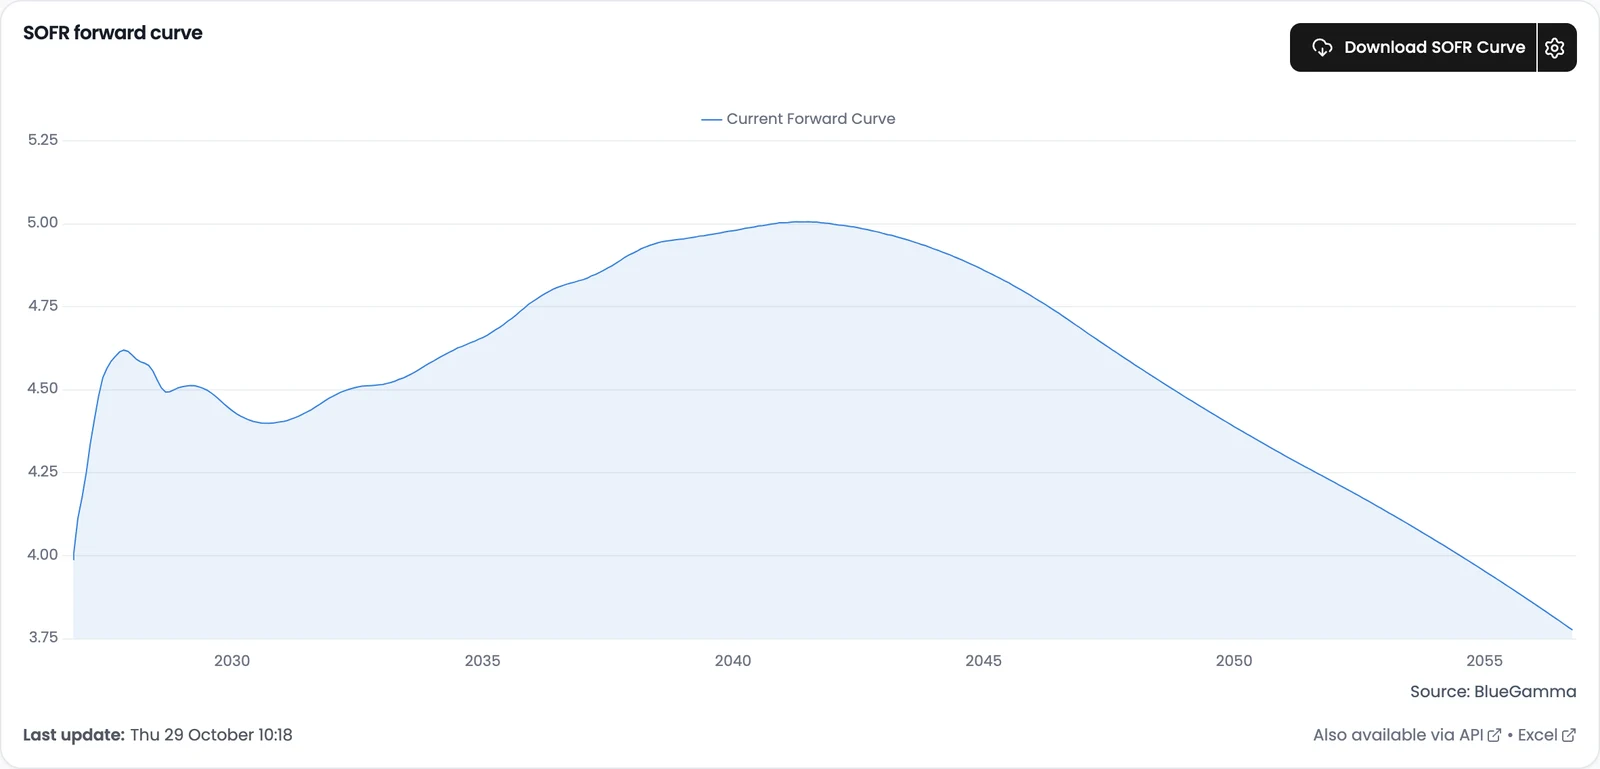
- 02
Price the hedge on the amortising profile
A bullet swap rate is the wrong number for an amortising asset. Upload the amortisation schedule to the swap pricer and read the mid on that exact profile: your expected hedge or funding cost, priced the way the bank’s desk will price it.
app.bluegamma.io/swap-pricer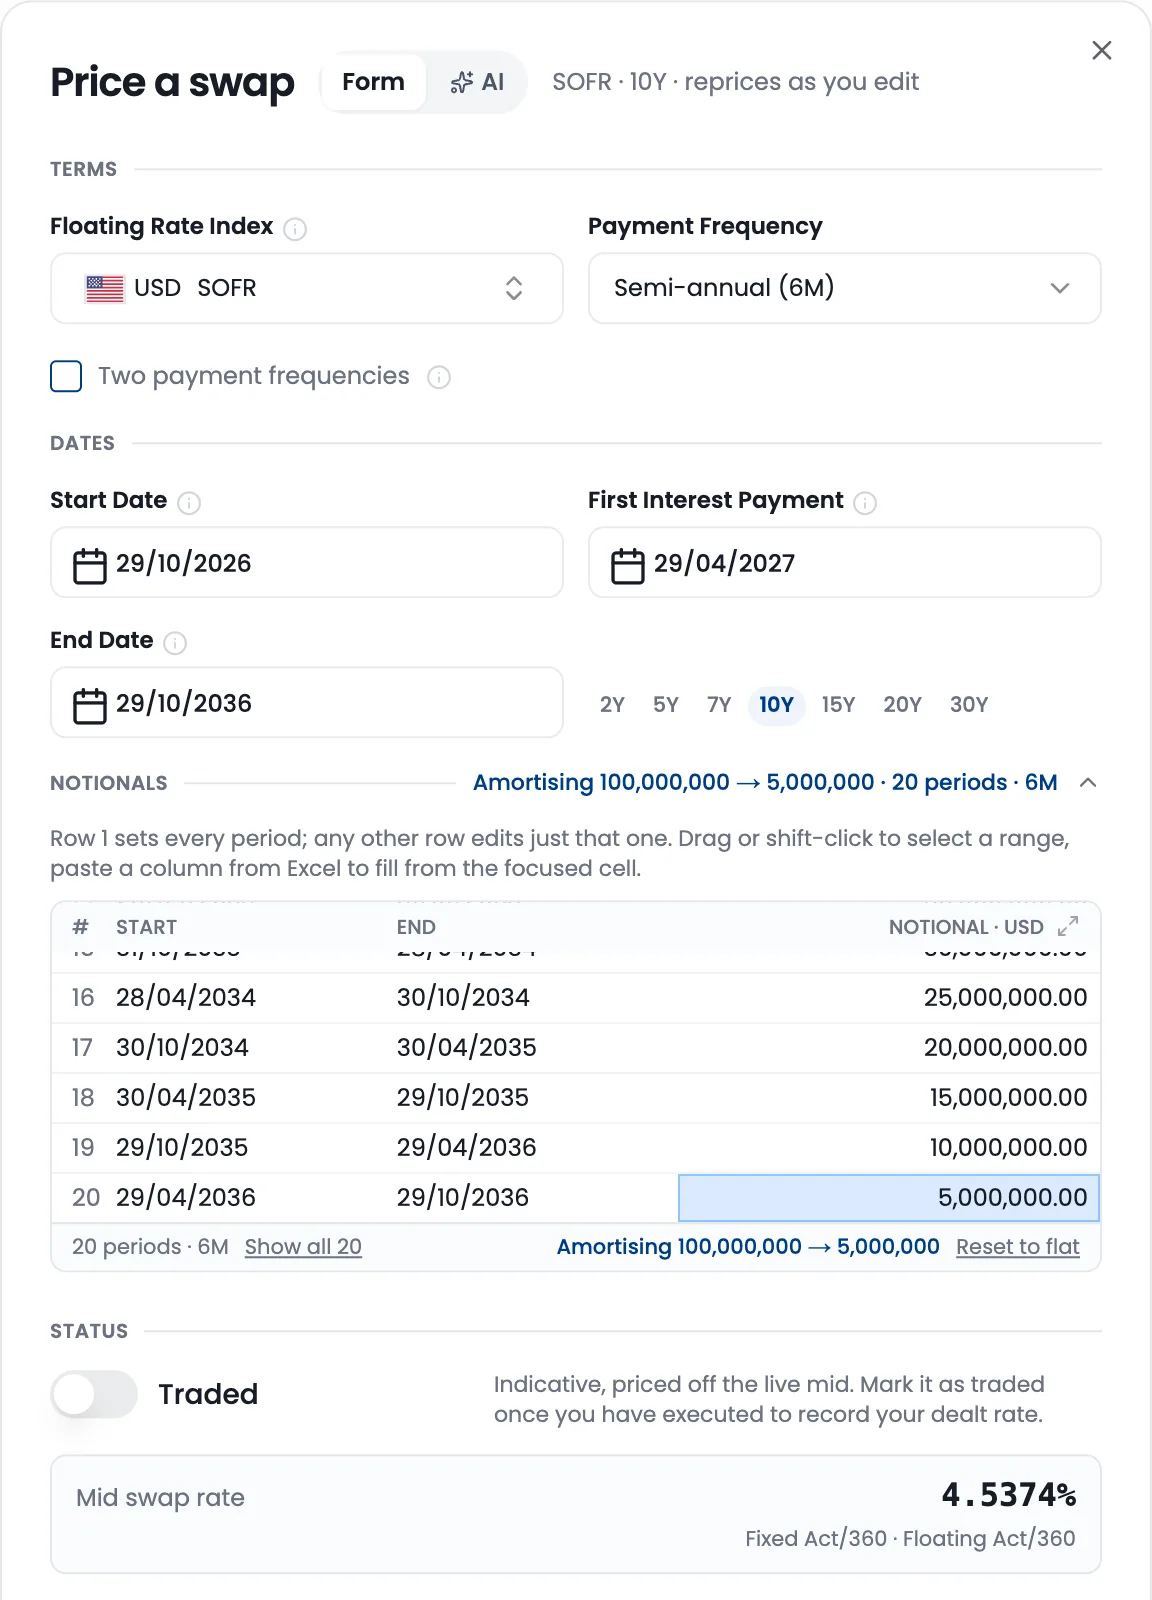
- 03
Re-pull at each gate, and archive the curve
Screening, first committee, final approval: refresh at each so the IRR moves with the market, and keep the as-of-date download with the paper. Several papers a week? Pull the curve daily through the API.
In their words
“I had benchmarked… the existing time series I have on that weekly email data set against what your platform was giving me in the historical… it was, you know, right on the money.”
“Sometimes I take some margin compression, sometimes I get some margin windfall… I've definitely taken some significant margin compression in the last couple of months.”
“We project out our running IRRs and other performance metrics to see how our deals are doing, especially on things that are PIK… and one of the things we need to improve the accuracy is forward curves.”
Your options, compared
A fixed base rate ignores the curve, and a weekly bank email covers only what that bank quotes. BlueGamma gives the committee the full curve and a dated record.
| Criterion | BlueGamma | A fixed base-rate assumption | Weekly email from the bank | Premium terminal |
|---|---|---|---|---|
| Does it cover the currency of the deal? | Yes, 30+ currencies | Only the rate someone typed in | Only what your bank quotes | Yes |
| Does it show the curve's shape beyond 10 years? | Yes, the full curve | No, it's flat by design | No, you fill the gaps by hand | Yes |
| Can you price a hedge on an amortising loan? | Yes, upload the schedule and read the mid | No | Call the bank and wait | Yes, with the swap pricing module |
| Is there a dated record for the committee? | Yes, set the valuation date and save it | No | Only if you kept the email | Yes, within the terminal's licence terms |
| What does it cost? | A monthly plan | Free, but wrong once rates move | Paid for through the bank's margin | A terminal licence |
Questions teams ask
Read the forward rate for each interest period, add the deal margin, and apply it to the outstanding notional. In BlueGamma that is a curve download or an Excel add-in formula taking the period start, end and valuation date. For PIK positions, the same forwards project the capitalising coupon.
A bullet swap rate misprices an amortising deal because the notional-weighted life is shorter than the final maturity. In BlueGamma's swap pricer you upload the amortisation schedule from your model and get the mid swap rate on that exact profile. That is your expected hedge cost for the IRR.
Yes. Set the valuation date and BlueGamma returns the forward curve as of that day. Re-pull at each committee gate and archive the download, so when the deal is questioned later you can show what the market said on the day the paper was written.
On the same instrument, conventions and timestamp, BlueGamma's mid sits within about 1bp of the bank's own. Customers routinely check it against their bank's rate sheets first: one asset-finance treasurer compared its history with his hedge bank's weekly table and found it right on the money.
SOFR forwards are easy to find for free; CORRA, SARON and JIBAR mostly are not. BlueGamma covers them the same way as EURIBOR or SOFR: pick the index, set the valuation date, and download the curve or pull it through Excel or the API.
Yes. 1M EURIBOR and 3M EURIBOR are different indices with different forward curves, and the gap between them moves with the market. On a levered IRR even a few basis points is real money. Pull the forward curve for the exact index and frequency in the facility agreement, not a generic benchmark.
Related guides
Thursday's paper, priced off today's curve
Pull the forward curve, price the hedge on your real notional profile, and put a defensible IRR in front of committee.