The auditor wants an independent valuation of our swap
Set the swap up once and revalue it at each month-end off an independent curve, at the same close the bank uses. You get the MtM, PV01 and hypothetical derivative, plus a dated report that traces the mark back to market data, which is what the auditor asks for.
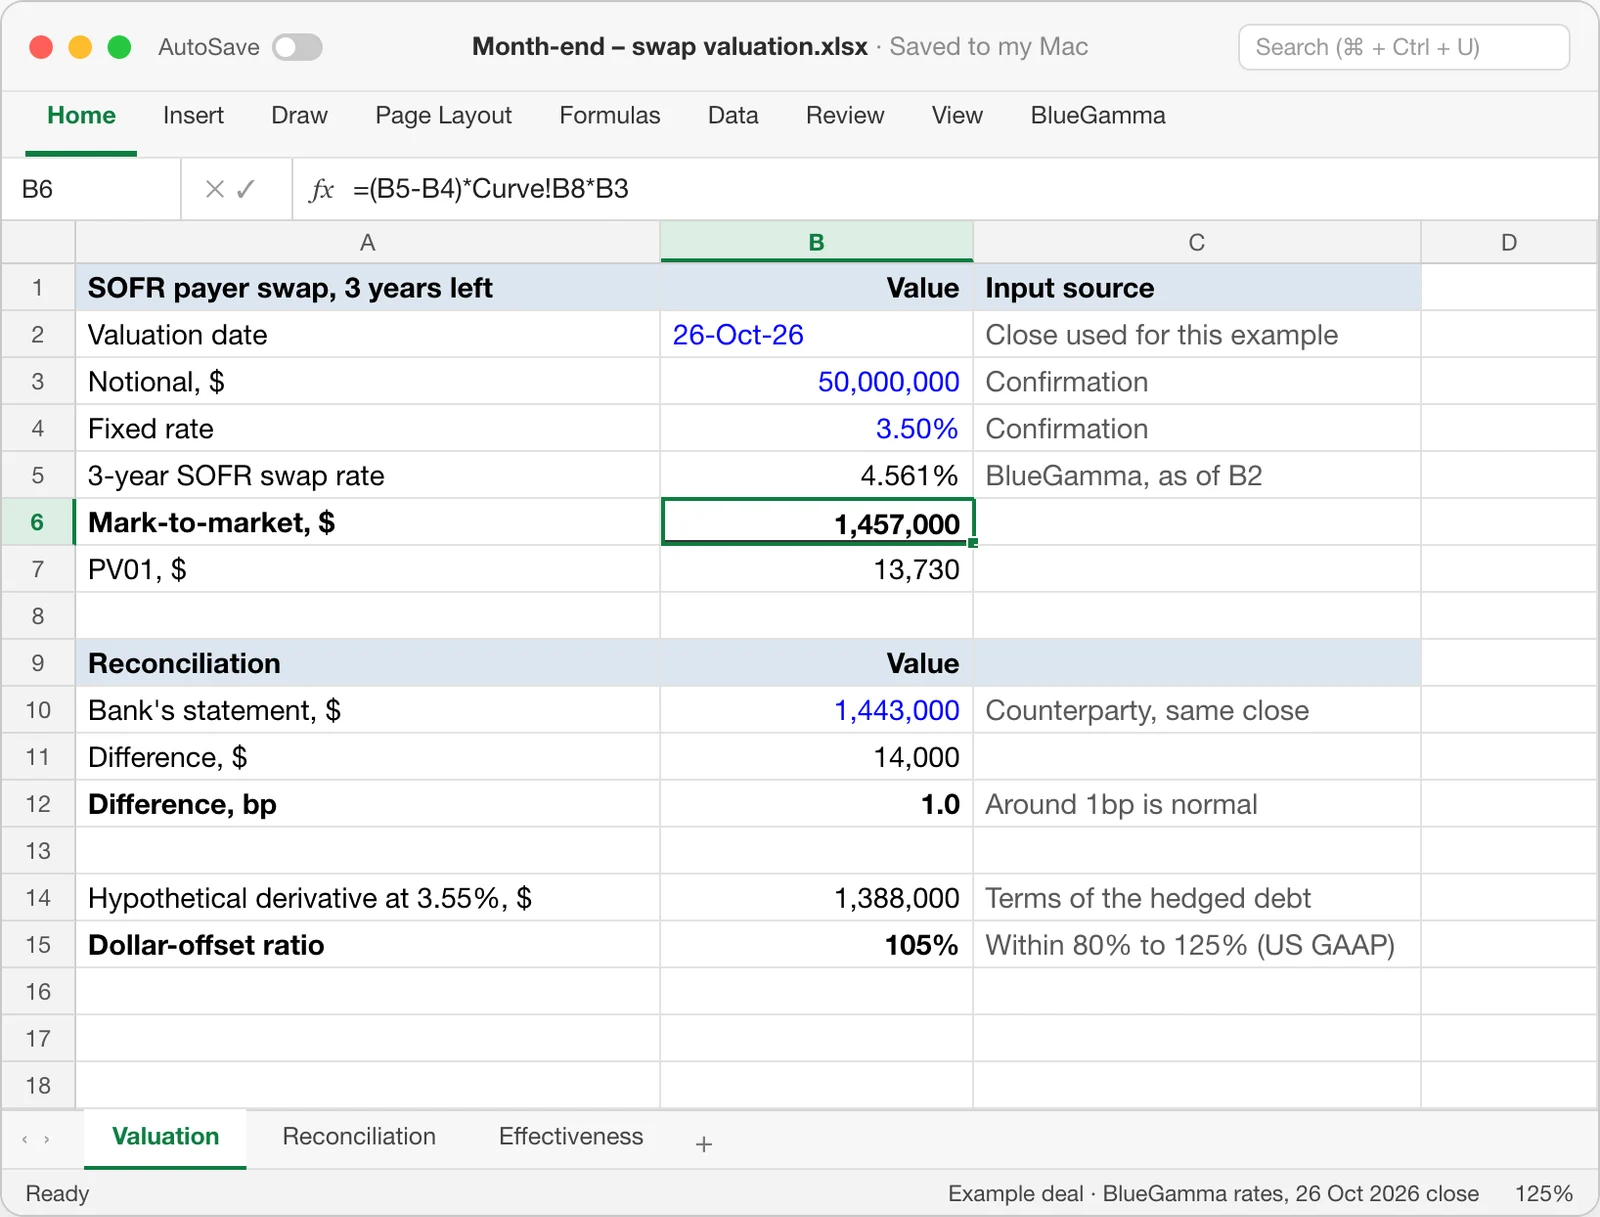
- ~1bptypical gap to the bank's mark, same close and conventions
- > 3bpa persistent gap worth querying with the bank
- $14kthe example’s gap to the bank’s statement, about 1bp of PV01
- Every inputcurve, date and conventions behind each mark, for the file
Today, and with BlueGamma
How it usually gets done
- A spreadsheet that discounts the cash flows, built by someone who has since left.
- The bank's statement: the counterparty marking its own trade, inputs rarely shared.
- A treasury system or an adviser, at a price built for a much bigger book.
With BlueGamma
- An independent MtM and PV01 on your exact schedule, amortising included.
- The valuation timed to the bank's close, so the numbers reconcile.
- The hypothetical derivative and a dated PDF report, every month-end.
Not the right fit if you want the hedge accounting entries posted for you. BlueGamma produces the valuations and their inputs; your team or adviser posts them.
How it works
- 01
Enter the trade once
Currency, start date, payment dates, frequency and fixed rate, matched to the confirmation. Paste an amortising notional profile straight from Excel. For hedge accounting, add the hypothetical as a second swap with the critical terms of the hedged debt.
app.bluegamma.io/swap-mtm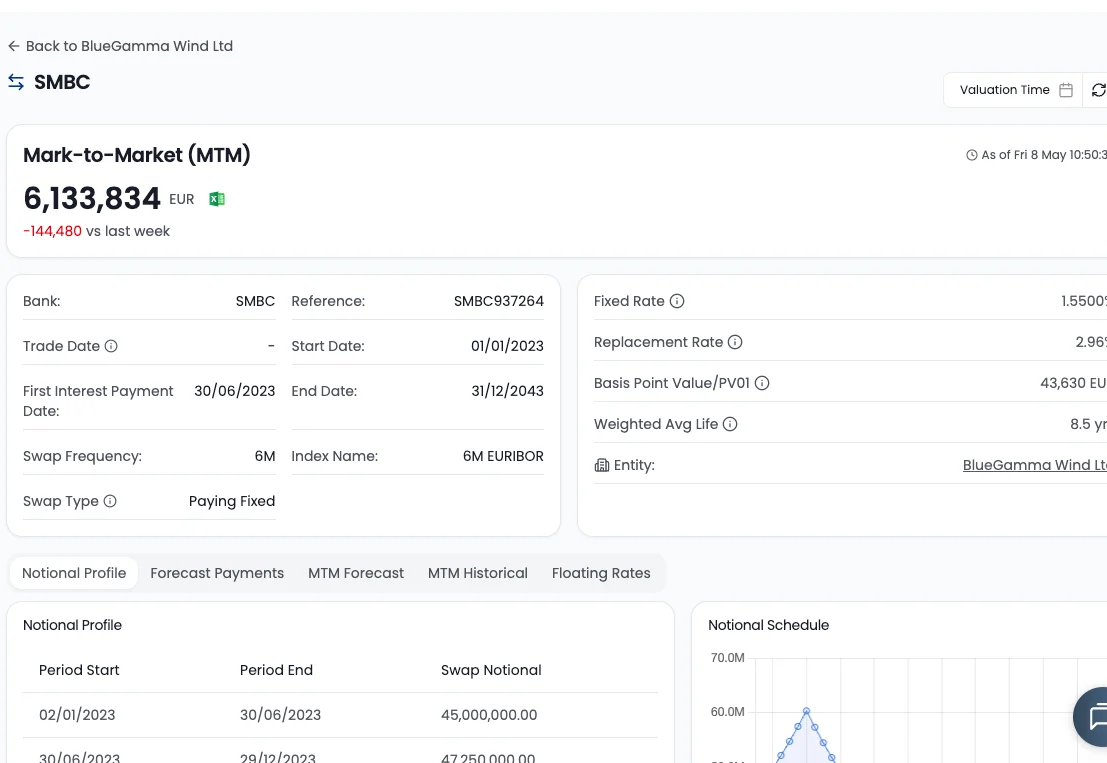
- 02
Value it at the bank's close
Pick the valuation date and time: if the bank marks at London 5pm, so do you. PV01 turns any gap into basis points, a number your CFO can set a threshold against.
- 03
File the report
Download the dated valuation report and the curve inputs behind it, and file both with the hedge documentation. Need the same trade as of several past dates for testing or a late designation? The Excel add-in prices it by as-of date in your own workpapers.
In their words
“What we need is not just an MtM at that point. What we need is all the inputs that have gone in determining that MtM.”
“If [our auditors] would come in and audit us in September and I go, yeah, I bootstrap my own curves and this is why we've made all these postings, it gives you less of a confidence interval than 'we've used a tool'.”
Your options, compared
Your own spreadsheet and the bank's statement aren't independent, and an adviser charges per engagement. BlueGamma gives the auditor an independent value with every input behind it.
| Criterion | BlueGamma | Your own Excel valuation | The bank's statement | A valuation adviser |
|---|---|---|---|---|
| Is it independent of you and the bank? | Yes | No, you built it | No, it comes from the counterparty | Yes |
| Can it value a hypothetical derivative? | Yes, as a second swap on the same curve | Yes, but you rebuild and maintain it | No | Yes, for a fee |
| Does it match the bank's closing time? | Yes, pick the date and time | Only if you pasted rates at that time | Yes, by definition | It uses their own close and method |
| Can you see the inputs behind the number? | Yes, they are downloadable | Only what was pasted in | Rarely | Yes, in their report |
| What does it cost? | A monthly licence | Hours of work every month-end | Built into the trade price | A fee per engagement |
Questions teams ask
Auditors don't approve data vendors; they test where your number came from, whether it is independent of you and your counterparty, and what method and inputs sit behind it. An independent mark with downloadable inputs and a dated monthly report is a far stronger trail than a self-built spreadsheet or the bank's own statement.
Yes. The inputs as at that valuation date, and the curve built from them, can be pulled again, timestamped to the minute for swaps and OIS. Historical records are not rewritten, so the same date a year later returns the same inputs, bootstrapped with each currency’s market conventions.
Usually timing and conventions, not data: the bank marks at its own close, say London 5pm, or a day count or compounding setting differs. Set the valuation time to the bank's close and align the schedule. Around 1bp of PV01 is normal; a persistent gap of more than 3bp is worth querying with the bank.
Set it up as a second swap with the critical terms of the hedged debt and label it in the reference field. Both revalue off the same curve each month-end, and the Excel add-in prices either as of several past dates in one sheet. BlueGamma gives you the marks; the dollar-offset or regression workings stay in your workpapers.
No, deliberately. BlueGamma produces the valuations that feed your hedge accounting; the journal entries, OCI allocation and designation memo stay with your own team.
A single-currency licence is a flat monthly subscription covering the swap pricer, mark-to-market tool, curves and unlimited downloads. There are no per-valuation fees, so daily revaluation costs the same as monthly. The 14-day free trial lets you load your actual swap and check it against your bank's statement before paying.
More than 30 currencies, including SONIA, SOFR (with compounded-in-arrears and lookbacks), EURIBOR, TONA, TIBOR, CORRA, BBSW and JIBAR. A domestic benchmark with no traded forward market cannot be built as a market curve by anyone, so check a niche index during the trial.
Related guides
Have the answer ready before the auditor asks
Load your swap, value it at the bank's close, and file a dated report that traces back to the market.