How do I forecast our interest cost for next year's budget?
Forecast next year’s interest off the forward curve for your debt’s benchmark, at the facility’s own reset tenor, not last year’s average. The Excel add-in puts a projected fixing against every payment date in the model and refreshes it daily. Today the 2027 SONIA forwards sit 66bp above the rest-of-2026 forward, which a flat budget misses.
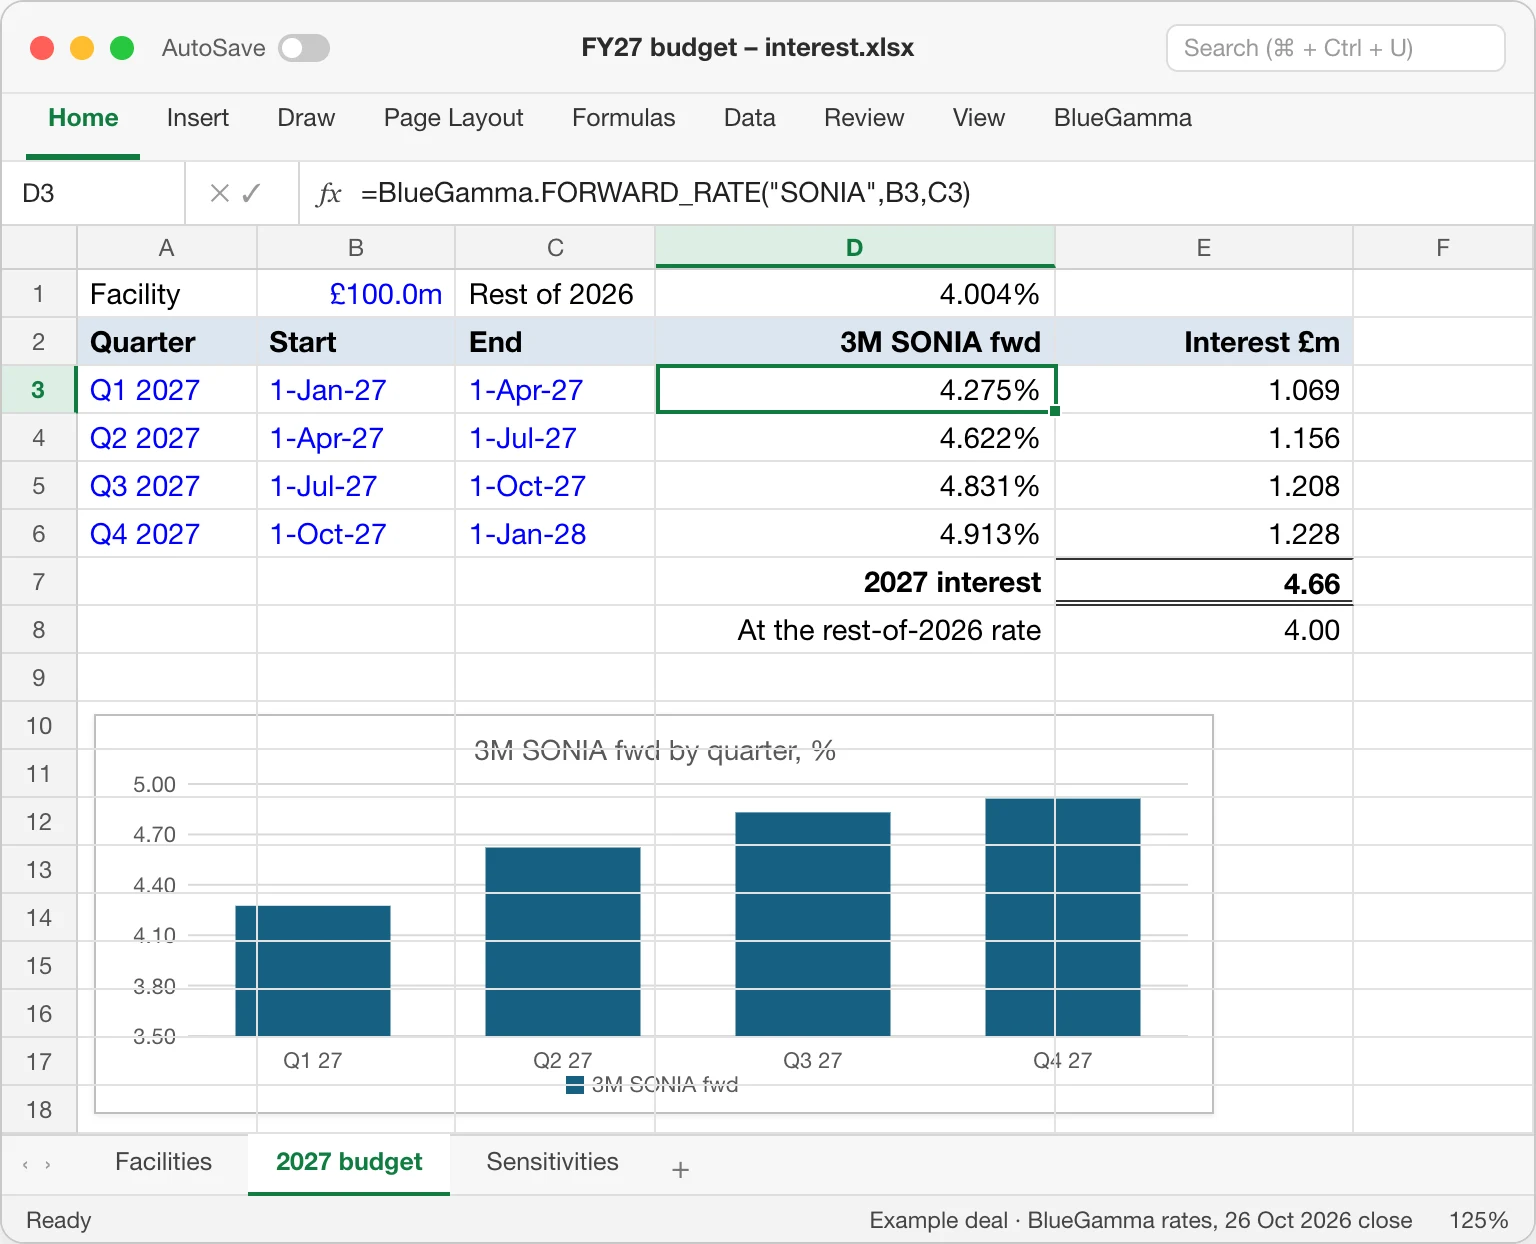
- +66bpwhere 2027 SONIA forwards average above the rest-of-2026 forward
- Dailyrefresh, so the forecast tracks the market
- 1M to 12Mreset tenors, each with its own forward curve
Today, and with BlueGamma
How it usually gets done
- Last year's average rate, rolled forward into every year of the plan.
- Hovering over a free chart to pick off data points, because the download is locked.
- The bank's emailed projections, which stop at about two years.
With BlueGamma
- The forward curve for your debt's benchmark, at the facility's own reset tenor.
- Monthly or quarterly points that line up with each payment date.
- Excel formulas that refresh daily, and an API for the ERP when you are ready.
Not the right fit if your debt is fully fixed for the budget year. The forecast only matters for the floating part.
How it works
- 01
Pick the benchmark and the reset tenor
EURIBOR, SONIA or SOFR, then the tenor from the facility agreement: 1M, 3M, 6M or 12M. Each has its own curve, and they diverge before you have assumed anything. It works the same way for BBSW, CORRA and the other currencies in the group.
- 02
Put a fixing against every payment date
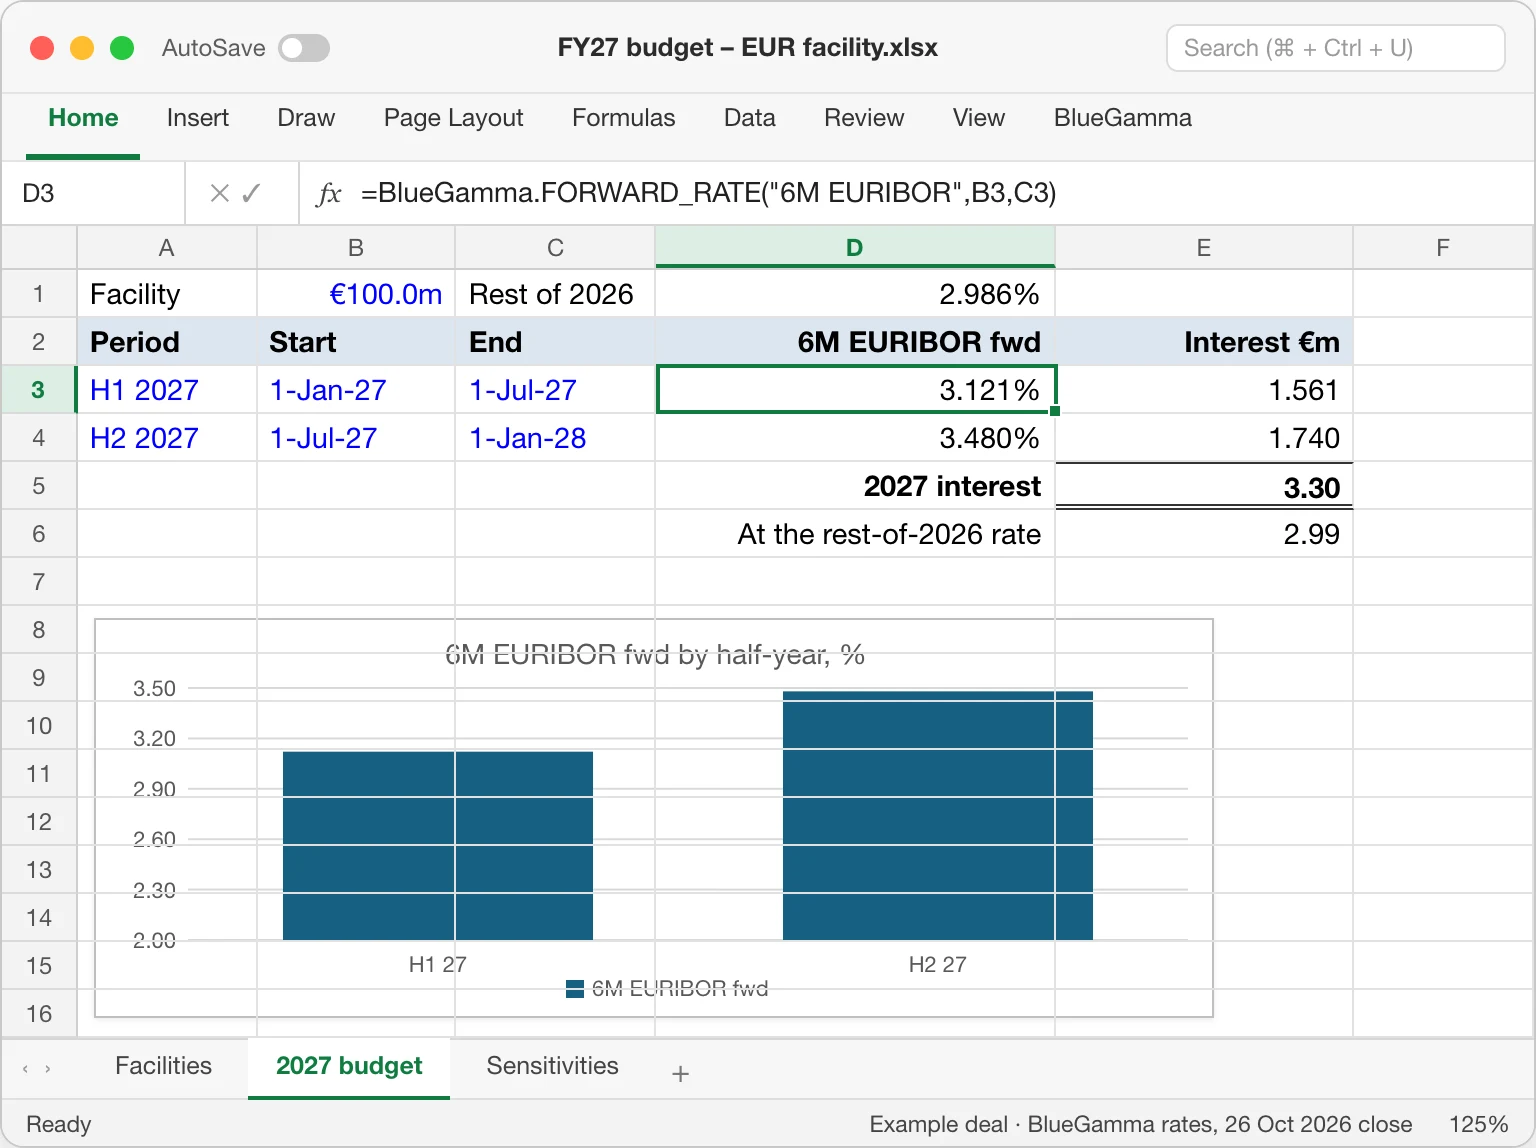
A quarterly-paying facility needs a projected fixing for every reset, not an annual tenor. In the Excel add-in, one formula per period returns the forward; add the margin and apply it to the notional outstanding, and that is the interest line.
- 03
Let it refresh, and re-run after big moves
The formulas re-pull daily, so every reforecast reads the live curve, and a locked valuation date reproduces the curve the budget was approved on. Ready to automate? Feed the ERP from the API.
In their words
“Every year we have to make plans and we have to make assumptions on… what the [EURIBOR] is going to be the following years. The problem is we use a static forecast which limits our ability to provide good forecasts.”
“My issue with [the terminal] is it's only annually. I like this option to just pull the forward curve monthly or quarterly going out. So don't get rid of that feature.”
Your options, compared
Last year's average looks backwards and free sources stop at past fixings. BlueGamma gives you the forward curve, on your payment dates, straight into the model.
| Criterion | BlueGamma | Last year's average rate | Free websites and central banks | Your bank's projections |
|---|---|---|---|---|
| Does it look forward? | Yes, the full forward curve | No, it only looks back | Mostly past fixings, not forecasts | Yes |
| How far ahead does it go? | Decades, beyond 2050 | One year, repeated | About 10 years, then flat | About 2 years |
| Does it cover 1, 3, 6 and 12-month rates? | Yes, all four for each benchmark | No, one blended number | Past fixings only | Only what the bank sends |
| Can you get monthly or quarterly points? | Yes, on your payment dates | No | No | No |
| How does it get into your model? | Excel formulas or the API | Typed in by hand | Read off a chart | Re-typed from an email |
Questions teams ask
Use the forward curve for your debt's benchmark, such as EURIBOR, SONIA or SOFR, rather than last year's average. The forward curve is the market's traded expectation of where the benchmark fixes period by period, so the budget picks up the rises and cuts the market has already priced. A prior-year average, or a system that takes today's spot rate and uses it forever, ignores them.
For each interest period, take the projected fixing from the forward curve at the loan's reset tenor, add your margin, and apply it to the notional outstanding for that period. Pull the curve at monthly or quarterly steps so every reset date gets its own fixing. BlueGamma delivers it into Excel through an add-in formula that refreshes daily, or through the API.
BlueGamma provides 1M, 3M, 6M and 12M EURIBOR forward curves built from live interbank swap rates, in the web app, the Excel add-in or the API; use in your own models and client deliverables is covered by your plan, and we ask that you check with us before publishing rates publicly. SONIA and SOFR work the same way. Central bank sites publish historical fixings, not forward curves.
No, and it doesn't claim to be. It is the market's current traded consensus, and realised fixings will differ. It is still the standard budgeting input because it is objective, updates daily and reflects central bank moves already priced; pair it with sensitivity scenarios such as plus or minus 50bp and 100bp for a buffer.
Yes, and it matters for debt service. Standard forward-curve screens output annual tenors, which don't line up with a loan that pays monthly or quarterly. BlueGamma lets you pull the curve at monthly or quarterly steps, matched to the payment frequency of the facility.
Potentially meaningful money. Each reset tenor has its own forward curve, and they do not move together. Check the facility agreement for the reset tenor and forecast off that curve.
Related guides
Put next year's budget on the curve
Pull the EURIBOR, SONIA or SOFR forward curve into your model this afternoon, and stop rolling last year's average forward.