How do I get a forward curve as of the valuation date for quarter end?
Set the valuation date in the curve configuration and download the forward curve as of that close, into Excel, through the API or as a file. Past closes are stored, so a re-pull of the same date reproduces the curve, and when a mark is questioned in three weeks you can show exactly what it was struck on.
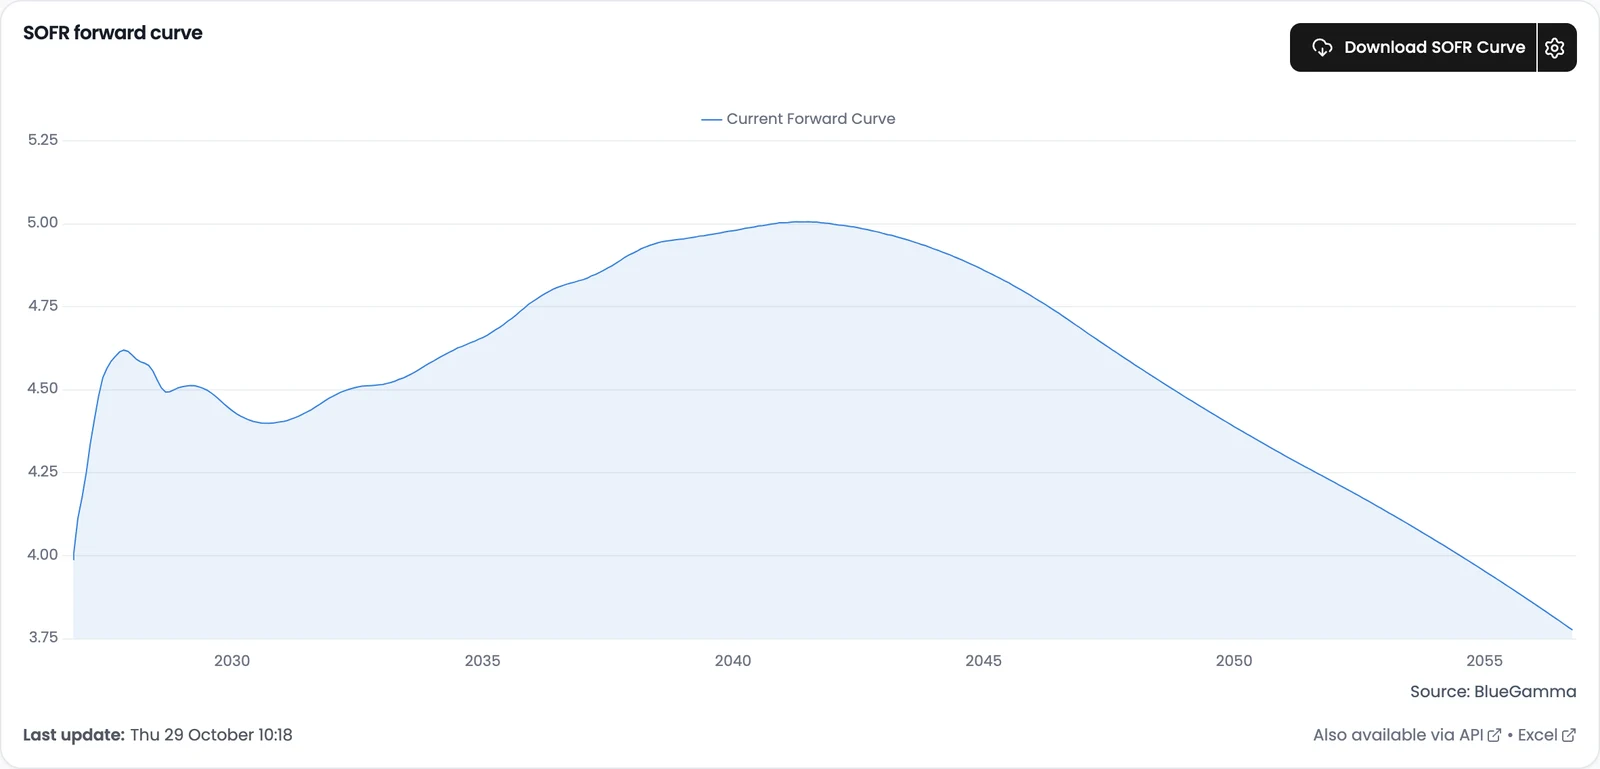
- Any closequarter end, month end or a loan’s origination date
- 30+currencies, plus zero rates and discount factors
- Storedpast closes are stored, so a re-pull of the same date reproduces the curve
Today, and with BlueGamma
How it usually gets done
- A terminal licence paid for all year to pull a handful of curves each quarter.
- A bootstrapping sheet built by a colleague who has since left.
- Free pages that show today's curve, not the one as of your valuation date.
With BlueGamma
- Any historical close, set once in the curve configuration.
- One model behind the web app, Excel and the API, so the numbers agree.
- A dated file for the deal folder that reproduces the mark later.
Not the right fit if you need intraday marks on a trading book. This is built for period-end valuation and the audit trail behind it.
How it works
- 01
Lock the curve to the valuation date
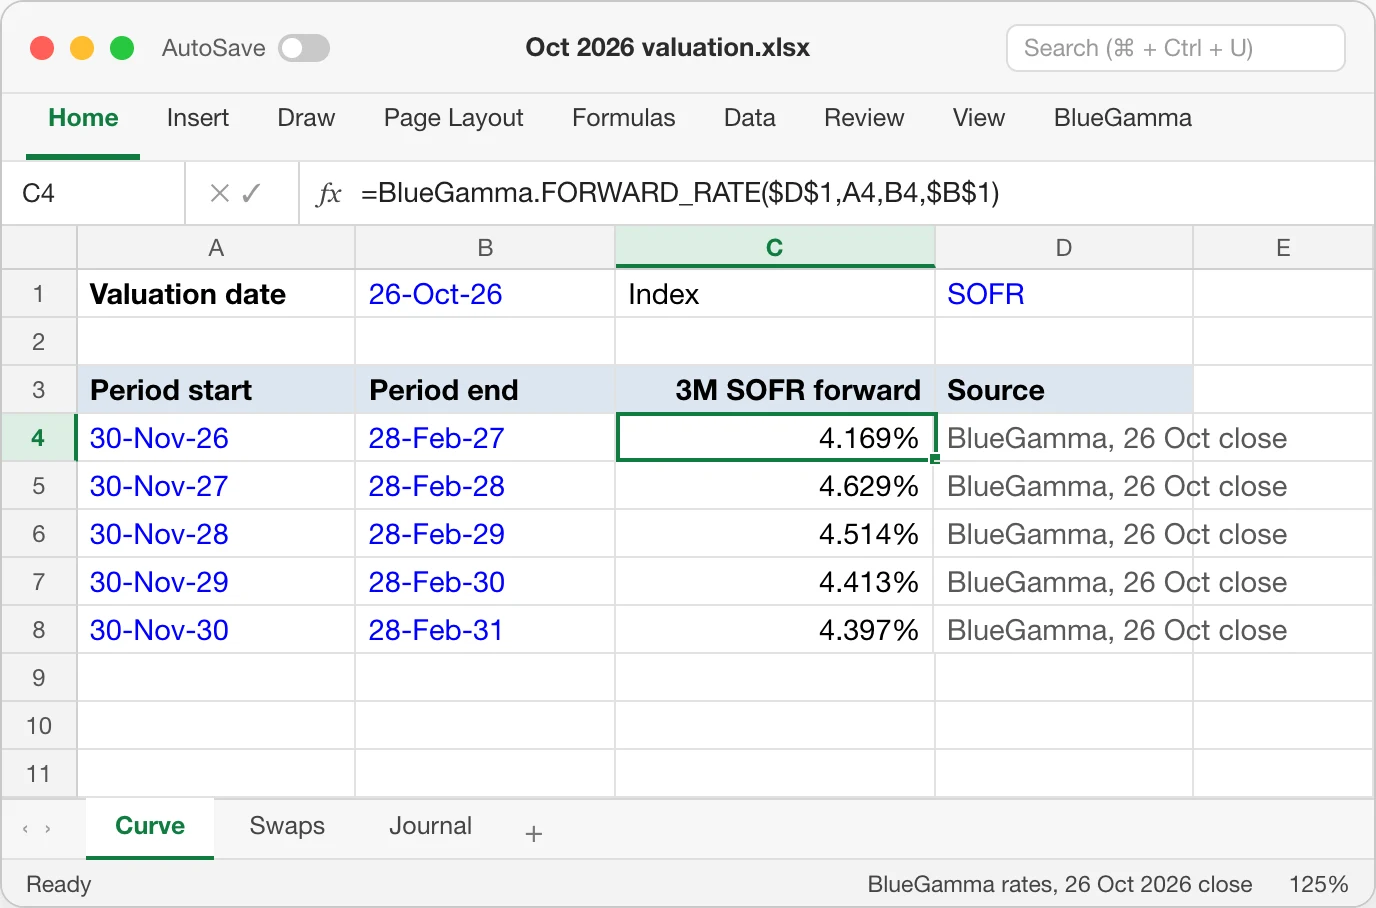
Set the model valuation date to your close, then the start date and payment frequency to match the deal documents. Monthly-pay books can tick “use end of month date” so every future period lands on the same day. Teams on a fixed reporting calendar lock those dates once and press F9 each quarter.
- 02
Pull every index the book needs
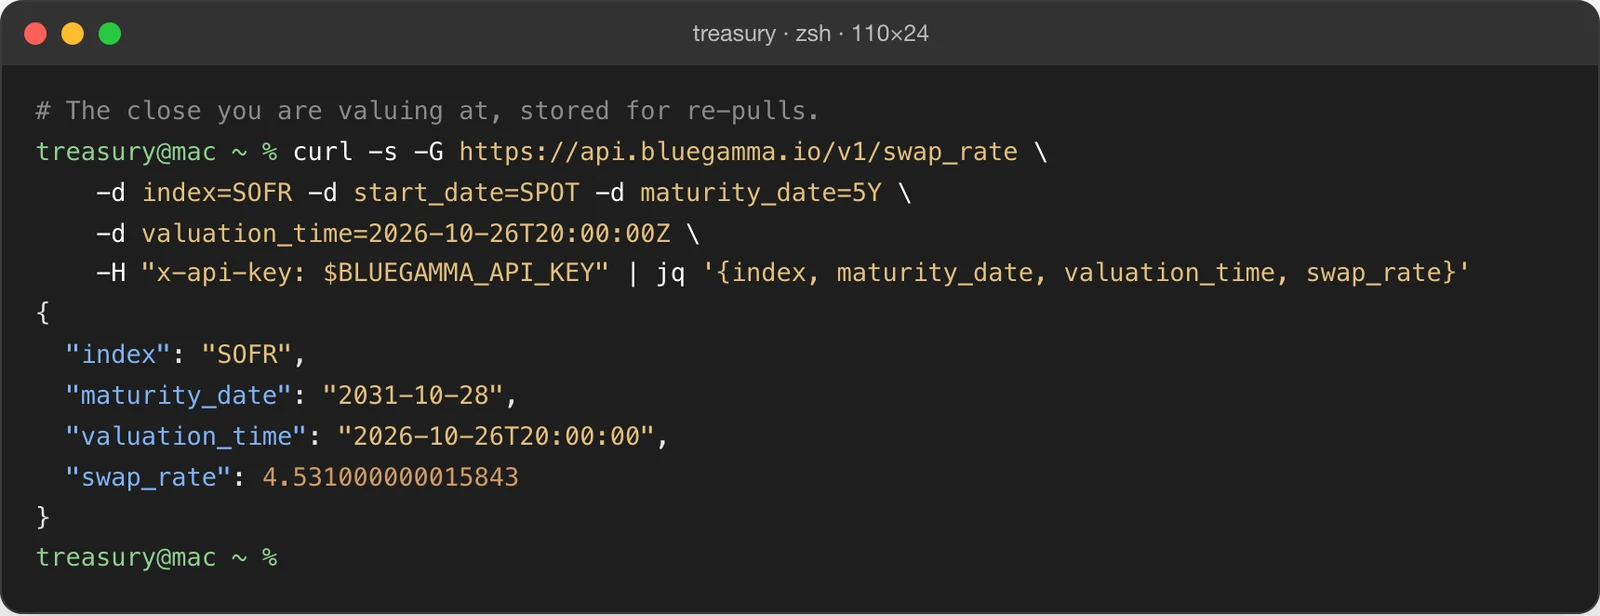
SOFR for the US loans, EURIBOR for the euro bonds, SONIA for sterling, several tenors of one index at once if loans reset differently. Feeding a valuation system? The API takes the same valuation time and returns the same numbers as the app.
- 03
Archive the dated curve
Save the export to the deal file. End-of-day rates for a past date don’t change, so when the mark is questioned in April, or in next year’s audit, you reproduce the exact curve the valuation was struck on, from an independent source.
In their words
“We received your data, everything was fine. I also spoke to the auditor… everything's fine from their side.”
“We'll need it every quarter… often they ask us to value things at a quarter end, but then also our methodology depends on going back in time and getting the risk-free curve as of the origination date of the loans.”
“I can download it… I can archive it and then that's fine for me. So then I have it.”
Your options, compared
Free sources only show today's curve, and building your own costs analyst hours. BlueGamma gives you the curve as of any business day, ready to value with.
| Criterion | BlueGamma | Premium terminal | Building curves yourself | Free sources |
|---|---|---|---|---|
| Can you get the curve as of a past date? | Yes, any business day | Yes, within the terminal's licence terms | Only if you saved the inputs | No, today's curve only |
| Are you licensed to use it in client valuations? | Yes, your plan covers it; ask us before publishing rates | Depends on the vendor | You still need licensed inputs | Depends on each source's terms |
| How do you get the data out? | Web, Excel and API | Often needs a separate licence | It's already yours | Copy and paste |
| What do you get? | A curve ready for valuation | Raw quotes you assemble | Whatever your spreadsheet produces | Numbers to re-type |
| What does it cost? | A flat monthly subscription | An annual terminal licence | Analyst hours every quarter | Free, but licence terms vary |
Questions teams ask
Open the SOFR forward curve in BlueGamma, set the model valuation date in the curve configuration to your close, for example 31 March, and download. The curve is rebuilt from the swap rates as of that date. Past closes are stored, so a re-pull of the same date reproduces the curve, which is what you need when a mark is questioned weeks later.
Yes. BlueGamma covers EURIBOR (1M, 3M, 6M and 12M), SONIA, SOFR, ESTR and 30+ currencies, including BBSW, BKBM, CORRA, JIBAR and TONA. You set the payment frequency and valuation date so the curve's periods match the instrument, then pull it by web download, the Excel add-in or the API.
Yes, as of any historical business day, including a loan's origination date years back. Historical curves are end-of-day snapshots, and past closes are stored, so a re-pull of the same date reproduces the curve. There is no single industry convention for the official close, so auditors look for a consistent, documented source applied the same way every period.
Overnight SOFR. The curves are built from compounded-overnight SOFR swaps, which carry the great majority of market volume. Term SOFR is separately licensed by its administrator and BlueGamma does not provide it, so if your credit documents require term SOFR fixings you'll need a licensed source for those.
It should tie out when you compare like for like: the same input convention, the same valuation date and the same end-of-day snap. Swap rates come from the same interbank market the banks use, refreshed every 30 seconds, and differences almost always trace back to conventions or to term versus overnight SOFR.
Yes. The JSON API returns forward curves, single-period forward rates, swap curves, zero rates and discount factors, each with an optional valuation time. Where payment dates must match the deal documents exactly, use the forward rate endpoint with explicit start and end dates. The web app, Excel and the API share one model, so they return the same numbers.
That is how most teams use it: one or two days a month. There are no per-pull charges, so the subscription is the whole cost, with no per-deal adviser fee and no analyst hours rebuilding curves each close.
Related guides
Pull this quarter’s curves before the close
Set the valuation date, download the curve, and keep a record that reproduces every mark.