> For the complete documentation index, see [llms.txt](https://www.bluegamma.io/documentation/llms.txt). Markdown versions of documentation pages are available by appending `.md` to page URLs; this page is available as [Markdown](https://www.bluegamma.io/documentation/market-data-guides/swaption-volatilities.md).
# Swaption Volatilities
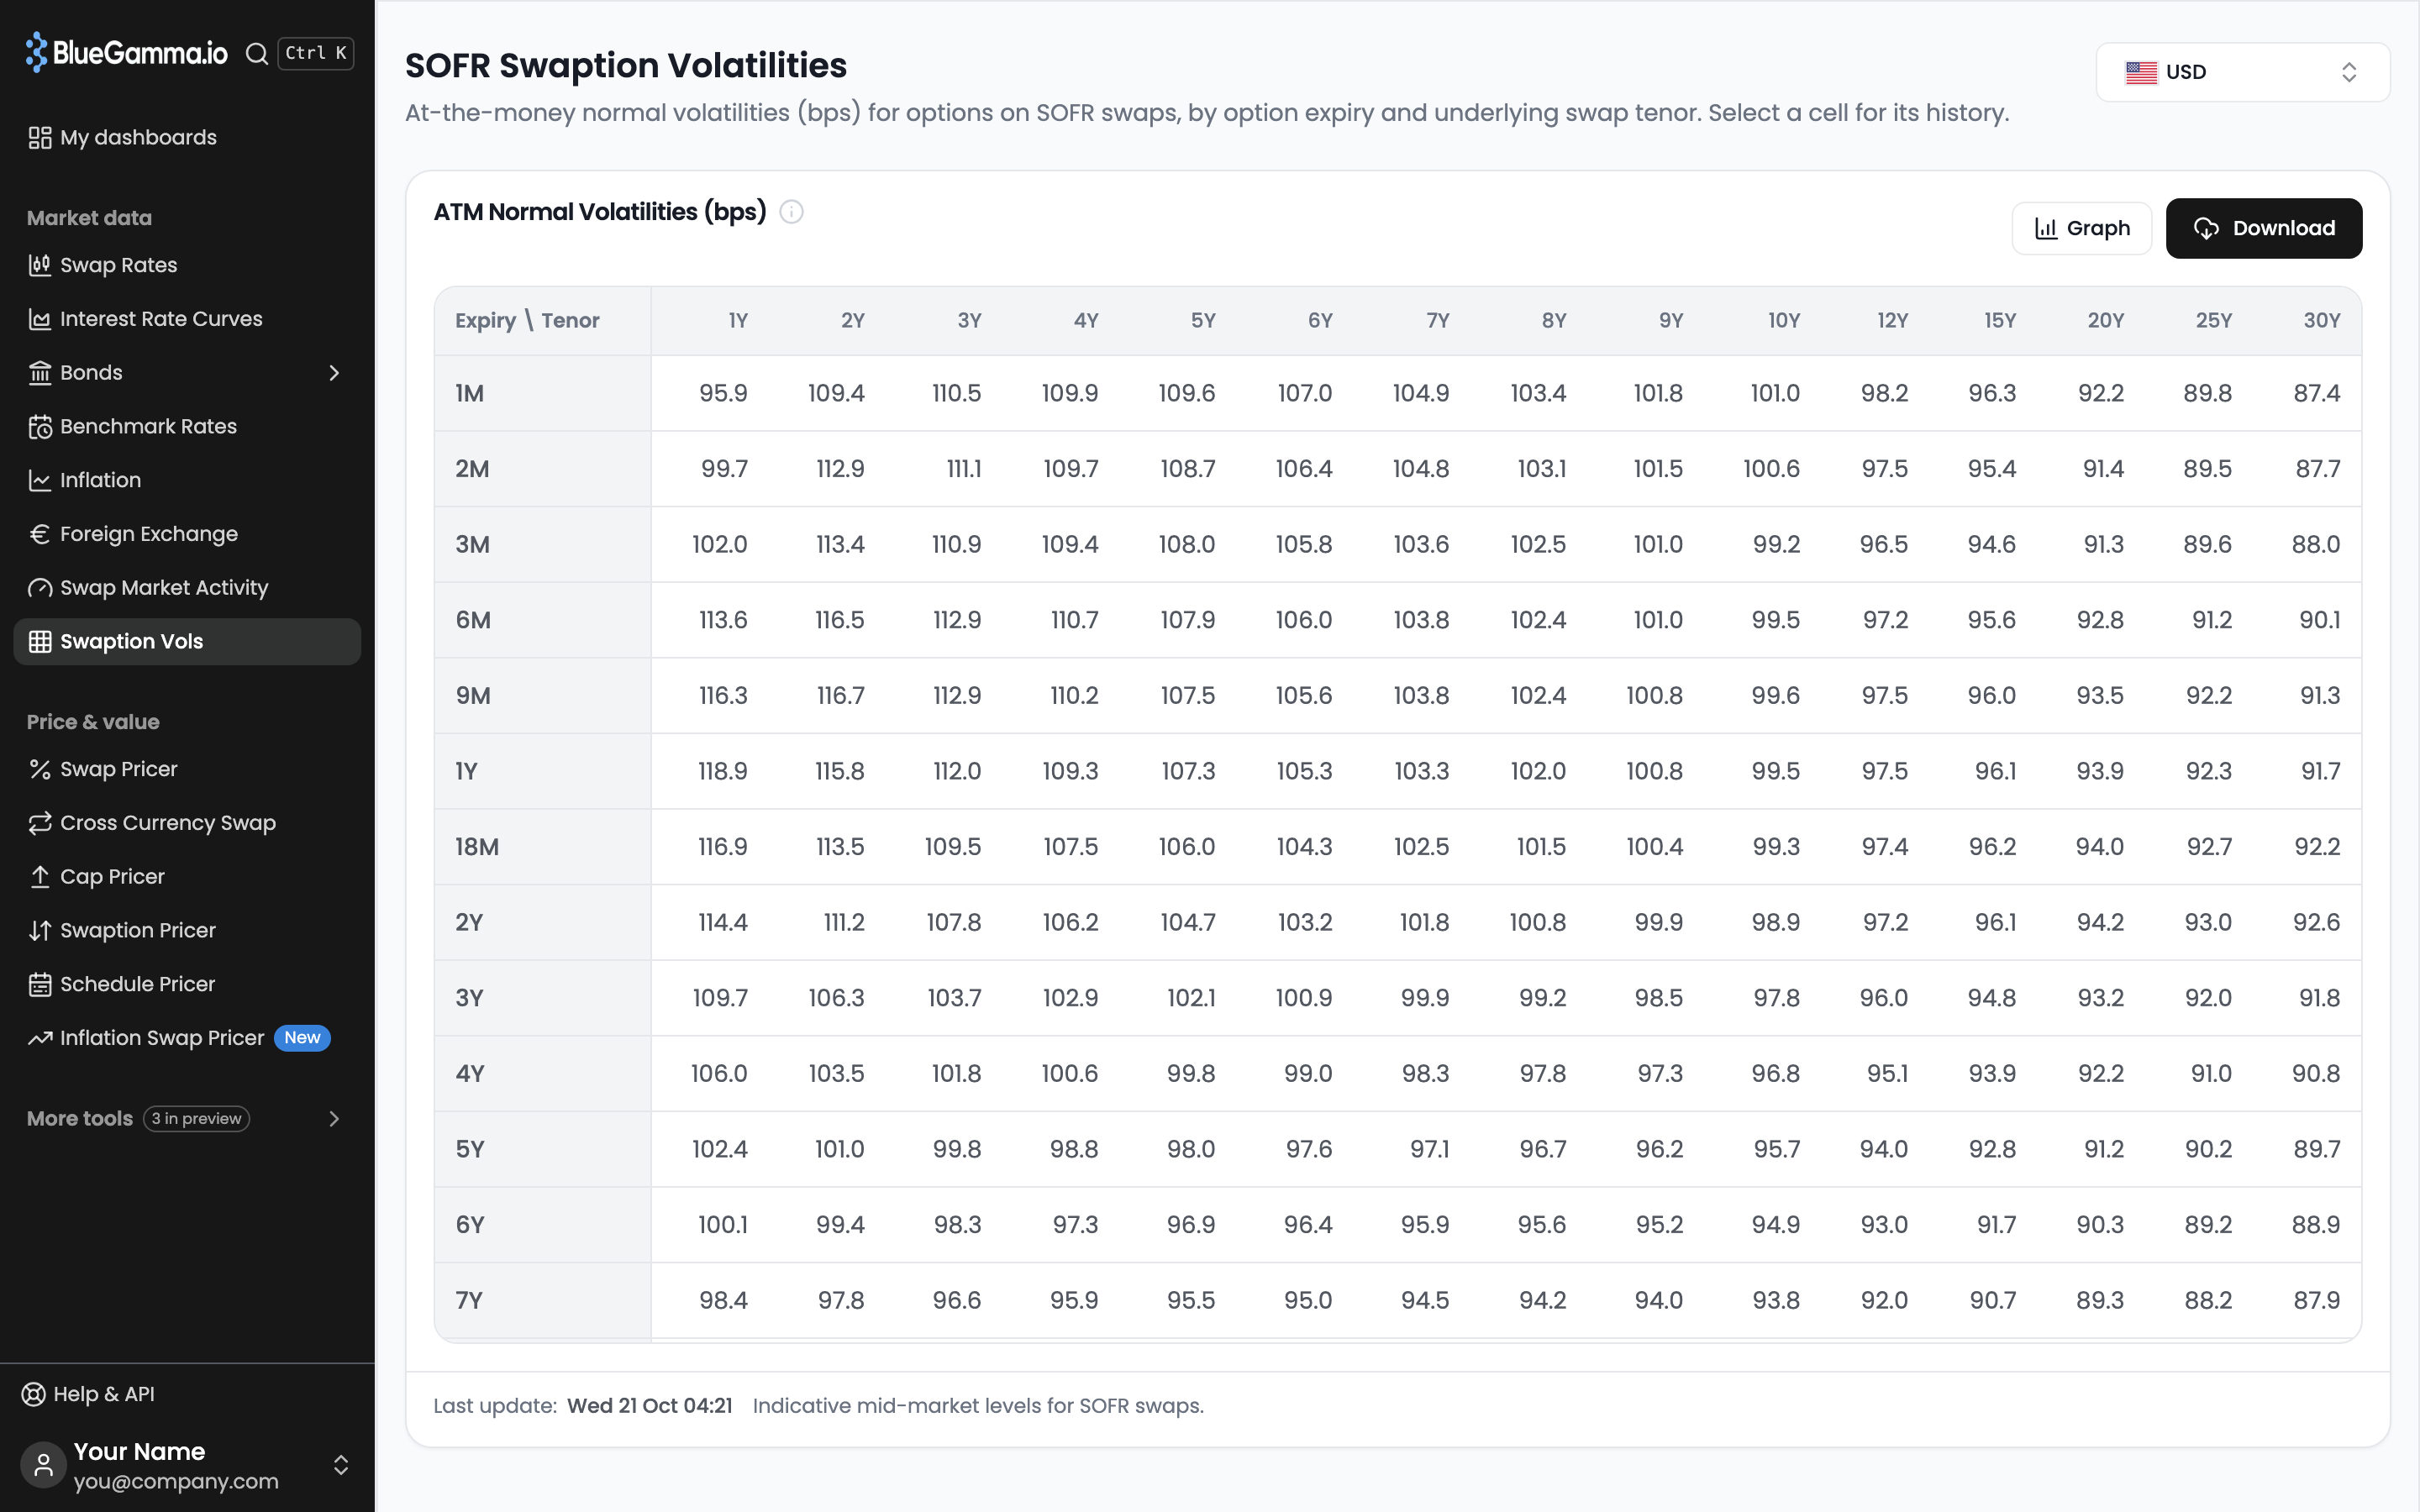
At-the-money normal swaption volatility matrices by currency, with the daily history of each expiry and tenor and a link to price the swaption.
**Swaption Vols** shows the at-the-money (ATM) normal volatility matrix for a currency's swaptions, and the daily history of any cell in it. Open it from the sidebar under **Market Data → Swaption Vols**.
***
### 1. Choose a Currency
The page opens on your default currency, or USD if your default currency has no swaption data. The currency picker in the top right lists the 21 currencies with swaption volatilities.
The page title names the swap index the options are on, for example **SOFR Swaption Volatilities** for USD.
***
### 2. Read the Matrix
The **ATM Normal Volatilities (bps)** card shows one volatility per cell:
* Each **row** is the option expiry.
* Each **column** is the tenor of the swap the option delivers into.
* Each **cell** is the implied volatility of the forward swap rate under the normal (Bachelier) model, in basis points per year, for a European swaption struck at-the-money.
Higher values mean the market is pricing larger rate moves. A dash means there is no level for that cell.
The footer reads **Indicative mid-market levels** and shows when the matrix was last updated.
**Graph** switches to a 3D surface with **Swap tenor**, **Option expiry** and **ATM vol (bps)** on its axes. **Table** switches back. **Download** exports the matrix to Excel.
***
### 3. Open a Cell's History
Click any cell with a value to open its history, for example **USD 1Y×5Y ATM Normal Volatility**. The page shows the latest volatility with its **Last print:** date.
Pick a period of **1M**, **3M**, **1Y** (the default), **5Y** or **Max**. Three statistics cover the selected period:
| Statistic | What it shows |
| ----------------- | ---------------------------------------------------------- |
| **Period high** | The highest daily volatility in the period |
| **Period low** | The lowest daily volatility in the period |
| **Period change** | The change from the start to the end of the period, in bps |
* **Chart** plots the daily series.
* **Table** lists each **Date**, **Vol (bps)** and **Change (bps)** from the previous value.
* **Download (Excel)** exports the selected period.
Daily values are the last print of each day. **All \[currency] swaption volatilities** at the top returns to the matrix.
***
### 4. Price the Swaption
**Price this swaption** opens the Swaption Pricer with the currency's swap index, the expiry and the tenor already filled in. The button appears when the pricer supports that currency, expiry and tenor.
***
## Related
* [Swaption Pricer](/documentation/pricers/swaption-pricer.md): price a swaption
* [How to Price a Swaption Using the API](/documentation/integrations/api/how-to-guides/how-to-price-a-swaption-using-the-api.md): the same pricing through the API
---
# Agent Instructions
This documentation is published with GitBook. GitBook is the documentation platform designed so that both humans and AI agents can read, navigate, and reason over technical content effectively. Learn more at gitbook.com.
## Querying This Documentation
If you need additional information that is not directly available in this page, you can query the documentation by asking a question.
Perform an HTTP GET request on the following URL with the `ask` and `goal` query parameters:
```
GET https://www.bluegamma.io/documentation/market-data-guides/swaption-volatilities.md?ask=&goal=
```
`ask` is the immediate question: it should be specific, self-contained, and written in natural language.
`goal` is what the user is ultimately trying to achieve, the reason they need the answer. Sharing it helps GitBook give you a better, more relevant answer. A goal is most helpful when it describes the outcome the user wants rather than restating the question. For example, with `ask=how do I create an API token`, a goal like `automate deployments from our CI pipeline` lets GitBook tailor the answer to that use case.
The response will contain a direct answer to the question and relevant excerpts and sources from the documentation.
Use this mechanism when the answer is not explicitly present in the current page, you need clarification or additional context, or you want to retrieve related documentation sections.