Mark to Market Calculation Explained with an Example

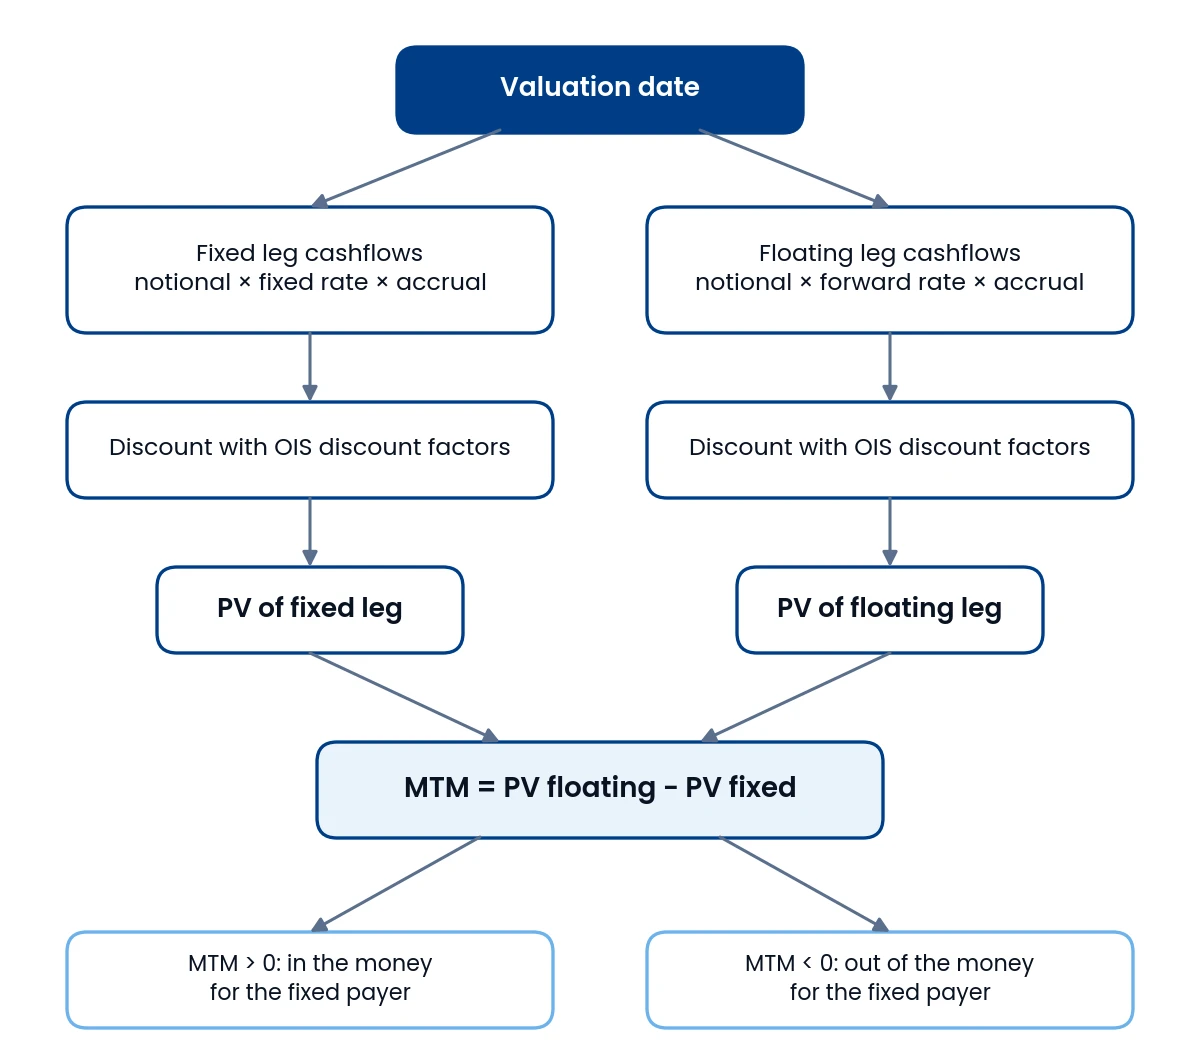
When it comes to valuing interest rate swaps, mark-to-market (MTM) helps you understand the market value based on current market rates. In this post, we’ll strip away the jargon and show you exactly how the mark to market calculation works, using BlueGamma Solar’s interest-rate swap as our case study.
Mark to Market Calculation - What is it
At its simplest, a mark to market calculation discounts every future cashflow back to today’s date, giving you a single net value:
- Future payments (fixed and floating)
- Discount each one using the current yield curve
- Sum the present values
- Subtract fixed-leg from floating-leg
- Result = today’s swap value (positive or negative)
How the calculation works for an Interest Rate Swap
1. List Future Cash Flows
- Fixed-leg: semi-annual coupons at 2.50% p.a. on each notional tranche
- Floating-leg: benchmark rate (e.g. 1-month EURIBOR and 6-month Euribor) on the notionals, resetting each period
2. Fetch the Yield Curve
Take the forward curves and the OIS discount curve as at your valuation date. In the example below we use the EURIBOR forward curves and the €STR discount curve as at 30 April 2025.
3. Calculate Present Values
Use your 1-month and 6-month EURIBOR forward curve to get each forward rate
Compute each cashflow
CFifloat = N × f(ti−1, ti) × τi
where N is the notional for the period, f(ti−1, ti) is the forward rate for the period from the forward curve, and τi is the accrual fraction under the day count convention. Fixed leg cashflows work the same way, with the fixed rate in place of the forward rate.
Discount both sets of cashflows using OIS‐derived discount factors
PV = Σi CFi × D(0, ti)
where D(0, ti) is the discount factor from the valuation date to the payment date ti.
4. Sum Up Each Leg
- PV(fixed) = total of discounted fixed payments
- PV(floating) = total of discounted floating payments
5. Compute MTM
MTM = PV(floating) − PV(fixed)
From the fixed-rate payer’s side, a positive MTM means the swap is in the money: if it were closed out, the floating-rate payer would pay you. A negative MTM means it is out of the money: you would pay to close it.
Prefer video? Watch the calculation explained in under three minutes on our YouTube channel.
The BlueGamma Solar Example
BlueGamma Solar is a hypothetical solar project that draws down debt between January 2026 and June 2030 and hedges each tranche with a 2.50% fixed swap. We value the swap as at 30 April 2025. Here’s the notional schedule:
| Period start | Period end | Notional (EUR) |
|---|---|---|
| 01 Jan 2026 | 31 Jan 2026 | 55,893,495 |
| 31 Jan 2026 | 28 Feb 2026 | 56,887,342 |
| … | … | … |
| 30 Jun 2030 | 31 Dec 2030 | 7,866,800 |
The schedule runs in monthly periods during the drawdown and semi-annual periods after it; the middle rows are omitted here. Fixed payments fall due semi-annually until December 2030, with floating payments on the same dates.
MTM Result & Interpretation
Plugging in the cash flows and discounting at 30 Apr 2025 provides us with a value:
MTM = -EUR 1,027,627
In plain English, the fixed-rate side (BlueGamma Solar) is out of the money by just over one million euros at the 30 April 2025 valuation date. Rates have moved since then, so the same swap valued today gives a different number; the method does not change.
Why we calculate Mark to Markets
A mark-to-market calculation is far more than an accounting line on your balance sheet. It’s a decision-making tool:
- Counterparty Exposure
MTM tells you exactly how much you’d gain or lose with each swap counterparty. Banks and funds use it to set credit limits, anticipate margin calls and avoid nasty surprises if markets swing.
- Break-Cost Estimation
Planning to refinance or restructure debt? MTM shows the penalty - or windfall - of unwinding your swap early. That way you can budget for any break fees and negotiate smarter terms.
- Strategic Decision-Making
With real-time swap values in hand, you can choose whether to hold your hedge, renegotiate the rate or close out entirely - rather than flying blind on outdated book numbers.
- Regulatory & Reporting Compliance
Auditors and regulators demand fair-value numbers. MTM keeps your P&L honest, your balance sheet transparent and your stakeholders reassured.
How to run a mark to market in BlueGamma
You can run the same calculation on your own swap in the BlueGamma app, using live curves or a past valuation date:
- Open My Swaps. Sign in to BlueGamma and go to My Swaps.
- Price a Swap. Enter the index, dates and notional. For an amortising or drawdown profile like the one above, paste the schedule in as notionals, and tick Two payment frequencies if the swap pays monthly during construction and semi-annually afterwards.
- Mark as traded. Enter the fixed rate from your trade confirmation. The swap moves to the Traded section.
- Open the swap. The valuation page shows the MTM with and without accrued interest (dirty and clean MTM), the replacement rate, the PV01, and the forecast payments behind the number.
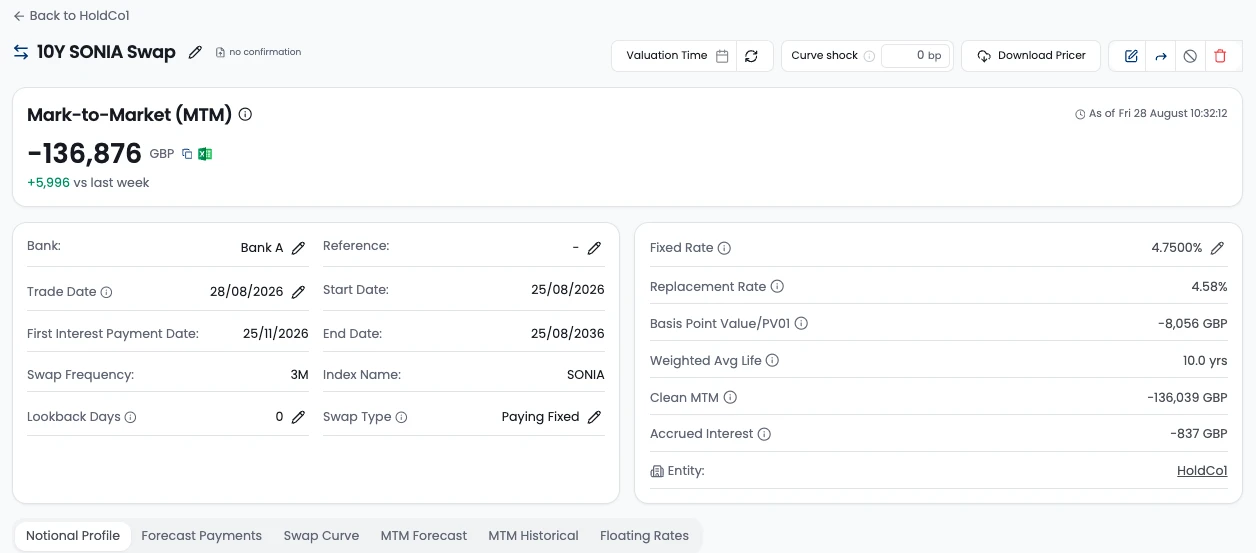
The clean MTM excludes interest accrued since the last payment date, which makes it the figure usually used for hedge accounting and for comparing valuations across dates. The Swap Mark-to-Market guide in our documentation covers every field on the page, and the MTM calculator page shows what the tool does.