SONIA Rates Year in Review: Where Next for the BoE?
BlueGamma, October 2026. Covers 30 September 2025 to 30 September 2026. Rate levels are from BlueGamma SONIA curves at the London close; policy and macro data are from the Bank of England, ONS and OBR, linked in the text.
A year ago the question in sterling rates was how fast the Bank of England would cut. Twelve months on, the MPC has cut Bank Rate once, to 3.75%, and the swap market now prices rate rises. Swap rates rose across the curve even as the overnight rate fell, and most of that rise came after February.
What happened to SONIA swap rates in the year to September 2026?
SONIA swap rates with maturities of one year and longer rose by 60 to 97 basis points, while the SONIA fixing itself fell by 24 basis points. The table compares our curve at the close on 30 September 2025 and 30 September 2026.
| Tenor | 30 Sep 2025 | 30 Sep 2026 | Change |
|---|---|---|---|
| SONIA fixing | 3.97% | 3.73% | -24bp |
| 6M | 3.94% | 4.11% | +17bp |
| 1Y | 3.86% | 4.46% | +60bp |
| 2Y | 3.77% | 4.68% | +92bp |
| 3Y | 3.77% | 4.74% | +97bp |
| 5Y | 3.84% | 4.79% | +95bp |
| 10Y | 4.15% | 4.99% | +84bp |
| 20Y | 4.57% | 5.26% | +69bp |
| 30Y | 4.64% | 5.27% | +64bp |
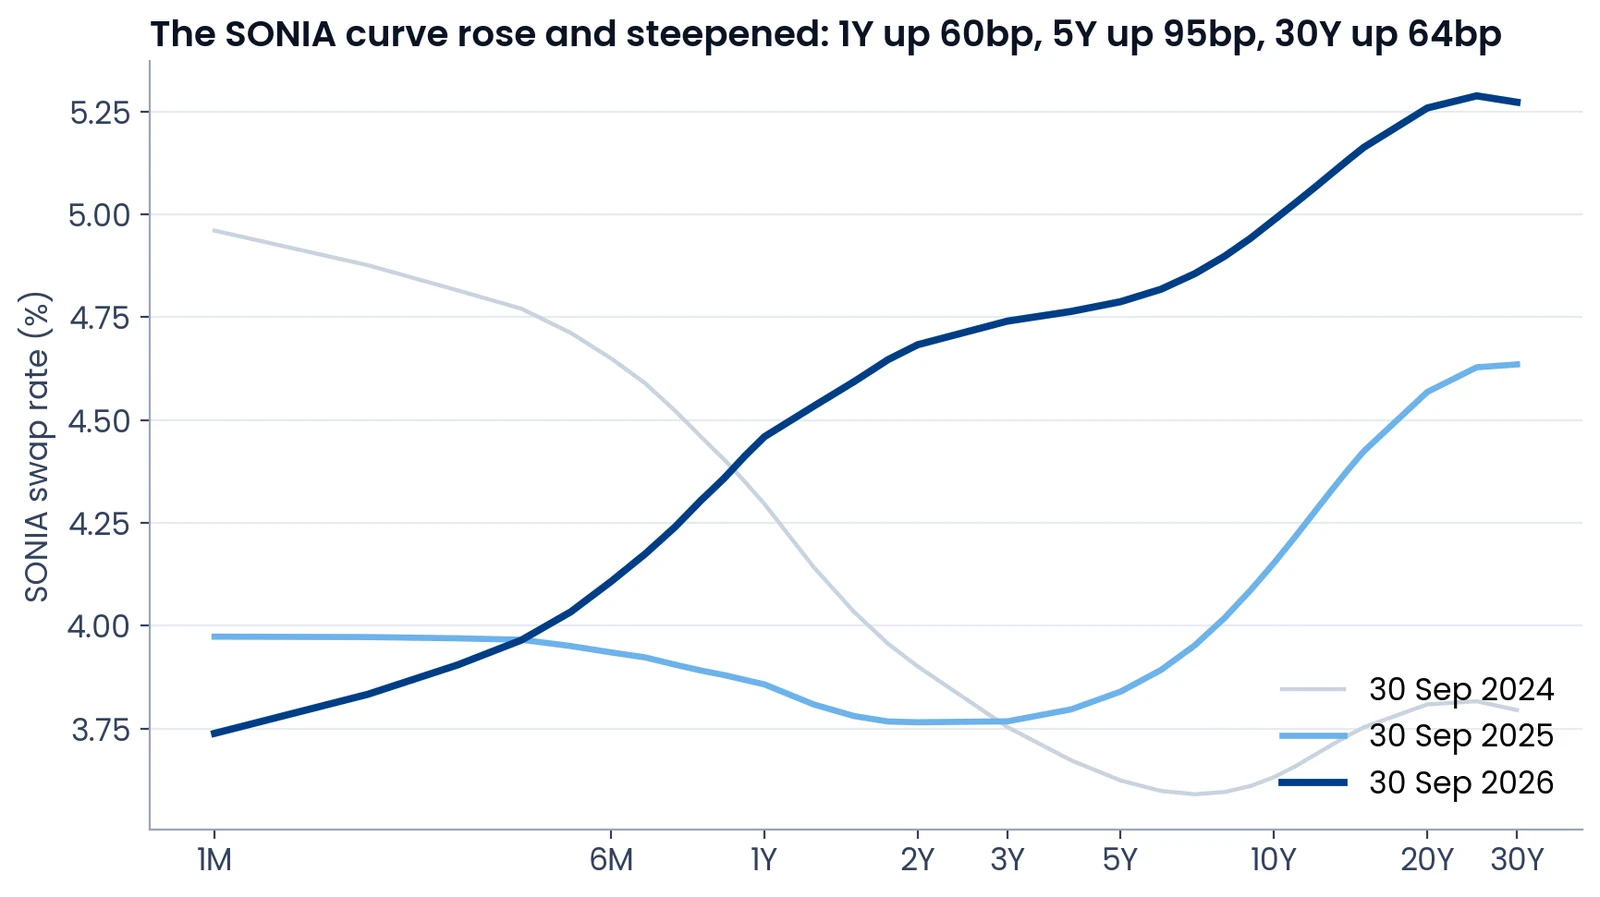
Three features stand out:
- The front end turned. In September 2025 the curve sloped down out to two years, which is what a market expecting cuts looks like. By September 2026 it slopes up from the first month, with the 1Y swap 73bp above the fixing.
- The 2Y to 5Y sector moved most. Rates in the three to five year area rose by close to a full percentage point, more than the long end. The curve flattened as a result: the 2s10s spread narrowed from 39bp to 30bp and 5s30s from 80bp to 49bp.
- The very long end is still inverted. The 50Y swap closed at 5.06%, about 21bp below the 30Y, the pattern we looked at in why 50-year SONIA swaps can be cheaper than 25-year ones.
For today's levels at each tenor, see our live SONIA swap rates.
One cut, then a sell-off
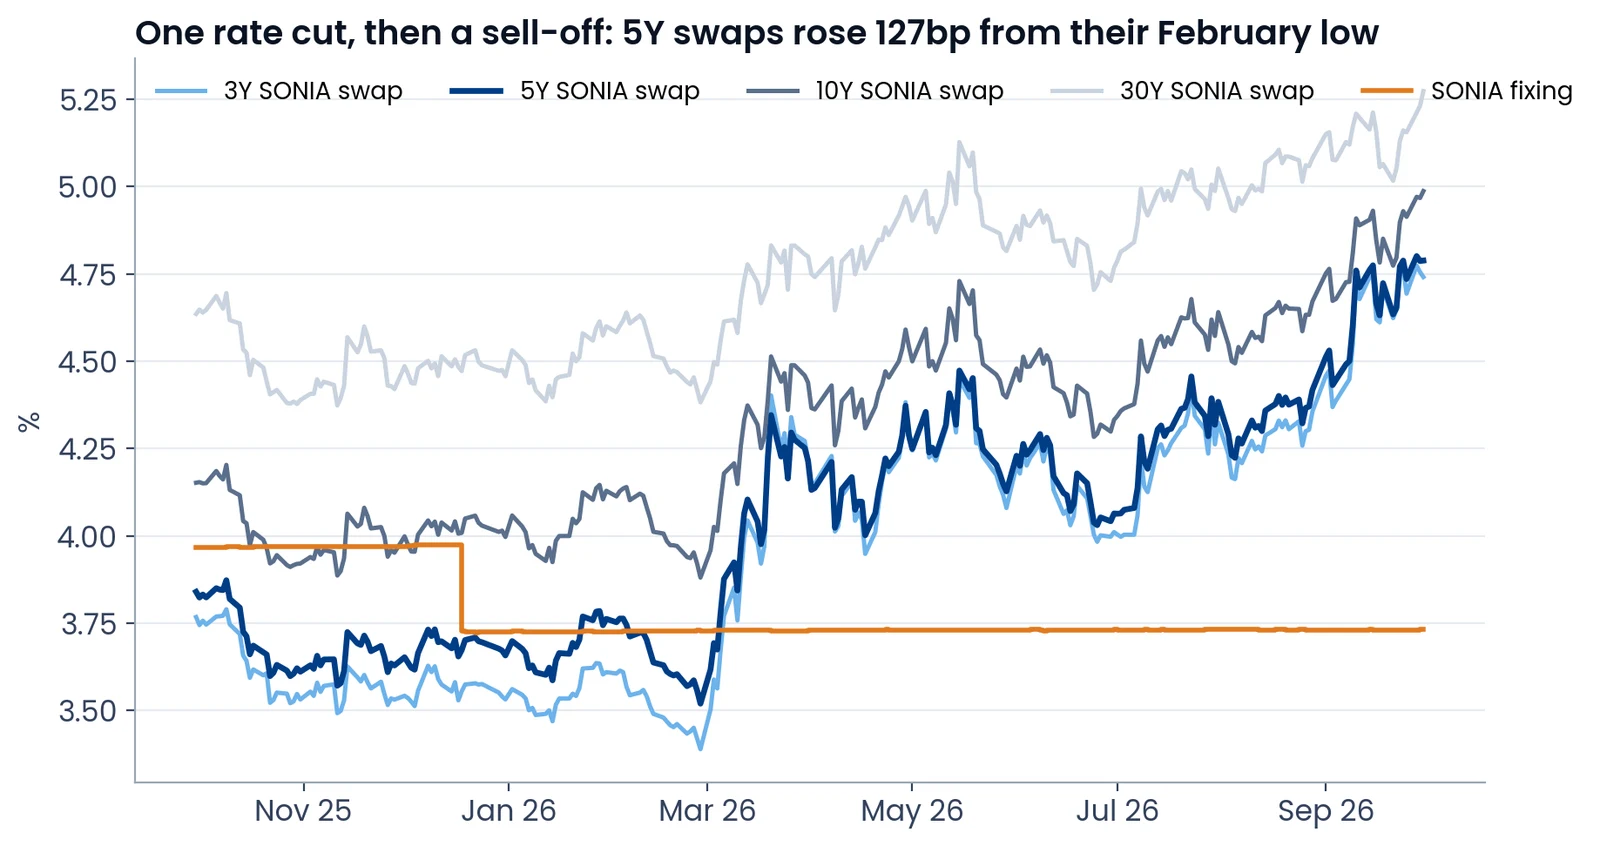
The year splits in two at the end of February.
October 2025 to February 2026: the cutting cycle looked on track. The MPC held Bank Rate at 4.00% in November on a 5 to 4 vote, with four members wanting a cut, and then cut to 3.75% on 18 December, again 5 to 4. Inflation was easing: CPI fell from 3.8% in September 2025 to 3.0% in January 2026, and the November Budget raised taxes and left £22bn of headroom against the fiscal rule. Swap rates drifted lower, and on 27 February the 3Y swap reached 3.39% and the 5Y 3.52%, the lows of the year. The 6M swap sat at 3.49%, about 24bp below the fixing, so the market was still pricing further cuts.
March 2026: the energy shock. The March MPC minutes describe conflict involving Iran, Brent crude above $100 a barrel, and shipping through the Strait of Hormuz almost halted, with the market-implied path for Bank Rate rising significantly. The 3Y SONIA swap rose 101bp in three weeks, from 3.39% on 27 February to 4.40% on 20 March. The largest single day was 19 March, when the MPC held at 3.75% on a 9 to 0 vote and the 3Y swap rose 29bp.
April to September: rises priced in, step by step. Rates eased in May and June, then moved higher again in two further bursts. Between 6 and 23 July the 3Y swap rose 42bp, a period that included the change of Prime Minister and Chancellor on 20 July. On 9 and 10 September it rose a further 29bp, with oil back above $100. Meanwhile the vote on the MPC shifted: one member voted to raise Bank Rate in April, two in June, and three in both July and September. Bank Rate itself has stayed at 3.75% since December.
Why did swap rates rise when Bank Rate fell?
Swap rates rose because they price the expected path of SONIA over the life of the swap, not today's fixing, and that expected path moved up sharply after March. A 5Y SONIA swap is roughly the average overnight rate the market expects over the next five years, plus a term premium. When the energy shock pushed the inflation outlook up, the expected path for Bank Rate rose, and with it every swap that spans that path.
The macro data explain why the market moved from cuts to rises even though domestic inflation pressure eased over the year:
| A year earlier | Latest | Source | |
|---|---|---|---|
| CPI inflation | 3.8% (Aug 2025) | 3.1% (Aug 2026) | ONS |
| Services CPI | 4.7% (Aug 2025) | 3.4% (Aug 2026) | ONS |
| Unemployment | 4.7% (May to Jul 2025) | 4.9% (May to Jul 2026) | ONS |
| Regular pay growth | 4.8% (May to Jul 2025) | 3.5% (May to Jul 2026) | ONS |
On the backward-looking data, the case for further cuts got stronger: services inflation and pay growth both slowed and unemployment rose. The market's concern is forward-looking. In its September minutes the MPC expects CPI to rise to about 3¾% in the fourth quarter of 2026 and slightly above 4% in the first quarter of 2027, with risks tilted to the upside, as higher energy prices feed through.
What the curve priced a year ago, and what happened
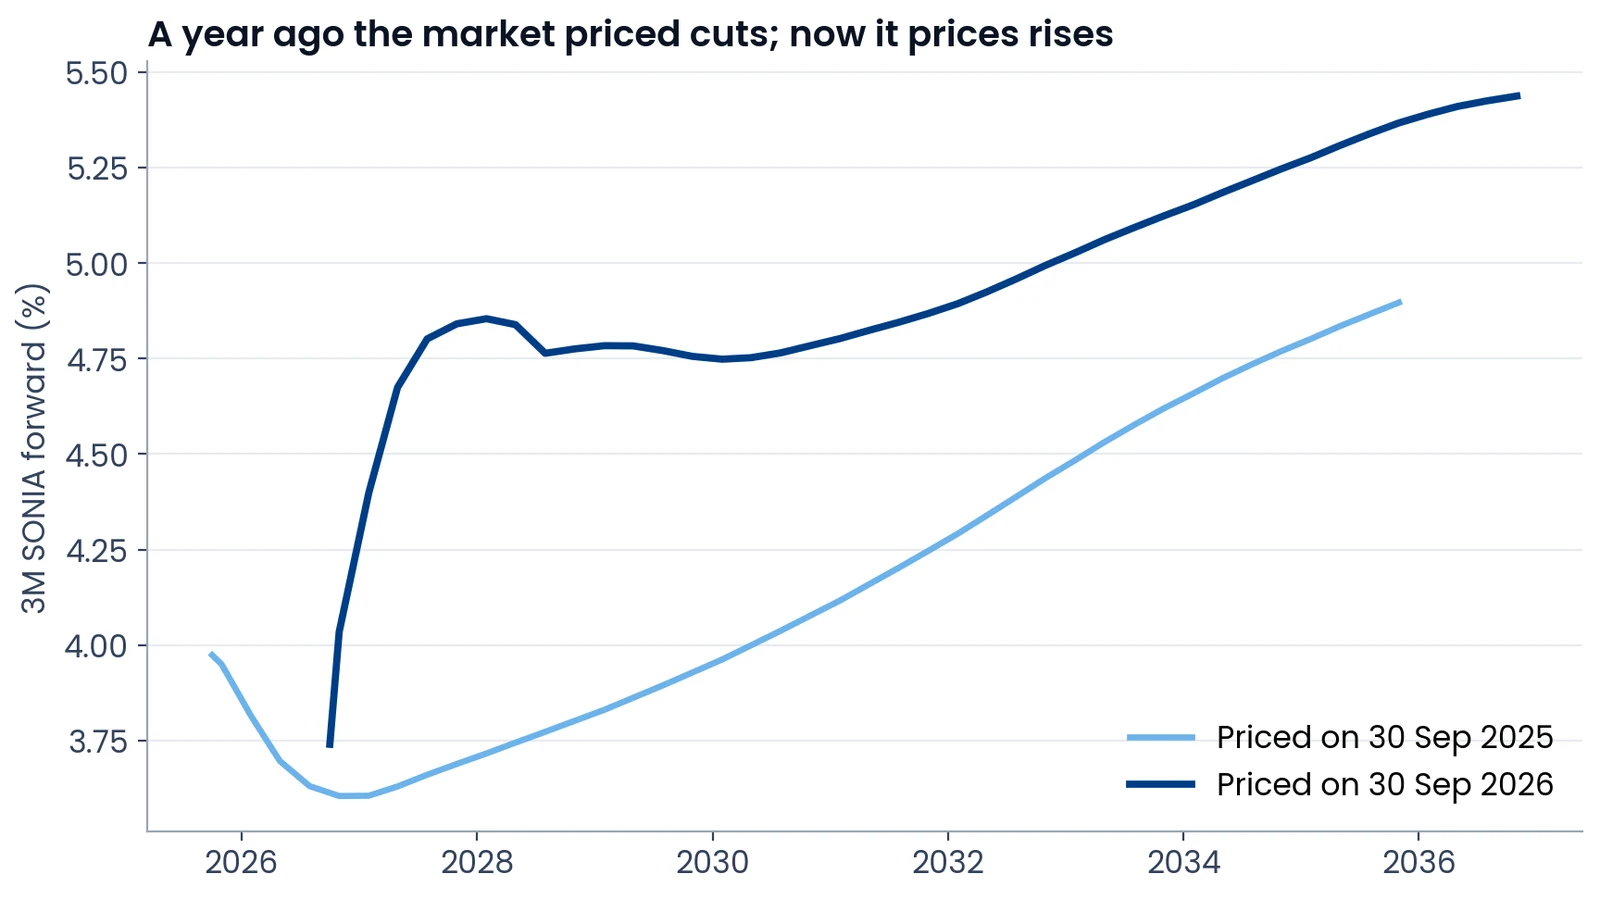
On 30 September 2025, our SONIA curve priced 3M forward rates falling to about 3.60% by late 2026, roughly one and a half quarter-point cuts. The MPC delivered one, and SONIA now fixes at 3.73%, so a year ago the curve priced slightly more easing than arrived. That is a useful reminder of what a forward curve is: the market's expected path on the day, not a forecast that holds still.
On 30 September 2026, the same curve prices 3M SONIA at 4.03% by the end of October, 4.40% by early 2027, and around 4.80% to 4.85% from mid-2027 into 2028. That is roughly 110bp of rises above today's fixing. The Bank's own September minutes describe the market curve the same way, peaking at around 4.9% by the end of 2027.
Where next for the BoE?
The swap market prices Bank Rate rises over the next year, and the MPC has three members already voting for one. What the market prices is not what the MPC will do: twelve months ago the curve priced cuts that only partly arrived, and in March it took three weeks to move a full percentage point.
The dates that will test the current pricing:
- 21 October 2026: September CPI from the ONS, the first print to show how far the energy shock is feeding into consumer prices.
- 5 November 2026: the next MPC decision, with a new Monetary Policy Report.
- Energy prices: the MPC minutes tie the inflation outlook to oil and gas prices, and each of the March, July and September moves in swap rates came alongside a rise in oil.
For the meeting-by-meeting probabilities the market implies, see our Bank of England interest rate forecast, which updates from the live SONIA curve. The full forward path is on our SONIA forward curve page, and realised overnight rates are on compounded SONIA.
Getting the data
Every curve in this review is available in BlueGamma at any historical close: SONIA swap rates at every tenor, the full forward curve, and fixings, through the web app, the Excel Add-in, or the API. If you value or hedge sterling debt, you can try it here, or book a call with our team.
This review describes market pricing and published data. It is not investment or hedging advice.