Interest rate data for renewable energy project finance and investment teams
For the project finance, investment and portfolio teams at renewable energy developers, IPPs and investors. Put a real forward curve behind every bid model, price the hedge on your sculpted debt, and value the swaps at each quarter end without waiting for the bank. In Excel, the web app or the API.
- ~1bpfrom the hedge bank's own mid on your sculpted profile
- 30 secrefresh on live swap rates through financial close
- Any closeas-of curve for every quarter end and audit
- 30+currencies: SOFR, EURIBOR, SONIA, BBSW, JIBAR and more
What renewable energy teams use BlueGamma for
Each one is a short guide with real numbers. Start with the one on your desk this week.
In their words
From our customer calls, lightly edited.
“Thank you very much for the tool because I use it for closing and then we just signed on the 24 December. So it was perfect timing.”
“It's really annoying. We got to call a bank every time we want to update a swap, or bang our heads against a free rates site to get the right data points.”
“We received your data, everything was fine. I also spoke to the auditor, everything's fine from their side.”
Where your team uses it
In the bid model
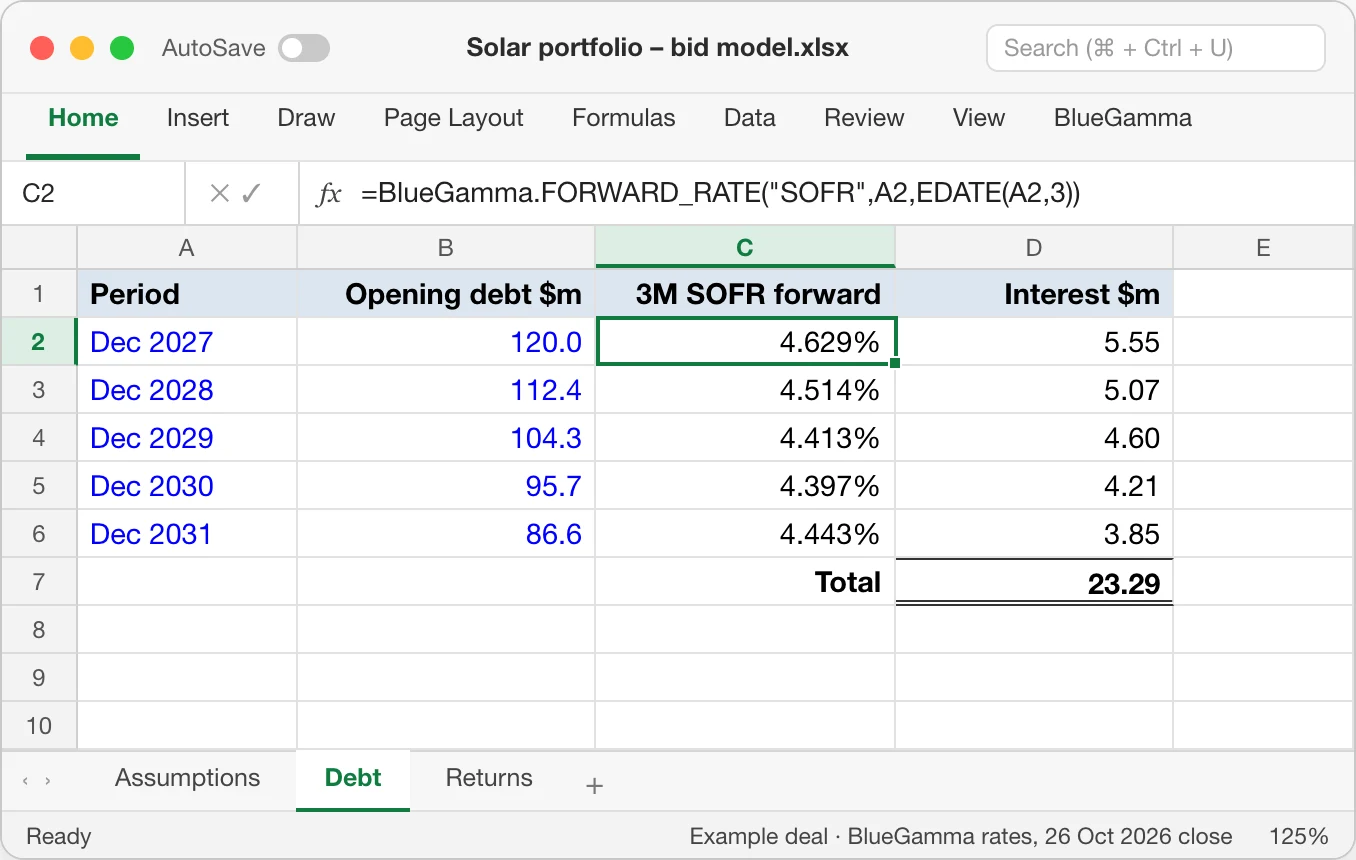
Forward rates and swap rates in Excel cells, refreshed on demand, on the exact benchmark and dates of your debt.
The Excel add-inAt financial close
Live mid on the sculpted swap profile, refreshed every 30 seconds, so you can check the hedge bank on the day.
The swap pricerAt every quarter end
Curves as of the valuation date and a mark-to-market for each swap, with a report the auditor can file.
The MtM calculatorQuestions teams ask
Can BlueGamma price a swap on a sculpted project finance debt profile?
Yes. Upload the notional schedule from your model and the swap pricer returns the mid swap rate on that exact profile, the number the hedge bank computes before adding its spread. You can reprice it at each investment committee gate.
Which benchmarks do renewable developers use most on BlueGamma?
SOFR and EURIBOR for most project debt, plus SONIA, BBSW, JIBAR, EIBOR, CORRA and other regional benchmarks across 30+ currencies.
Can I get the forward curve as of a past date for a quarter-end valuation?
Yes. Every curve is available as of any historical close, in the web app, in Excel or from the API, so the valuation and its audit trail use the same curve.
Do I need a terminal to use BlueGamma?
No. BlueGamma runs in the browser and inside Excel. Most teams are set up on the first day of the trial and check the numbers against their bank's in the first week.
Put a real curve behind the next bid
Pull SOFR or EURIBOR forwards into your model, price the hedge on your debt, and check the bank on closing day.